
Natural Language Testing Could Change The Case For Viavi Solutions Stock
- Viavi Solutions has integrated a Model Context Protocol Server Framework into its NITRO AI portfolio, allowing engineers to configure, run and analyze TestCenter, CyberFlood and TeraVM workloads using natural-language prompts and autonomous error correction.
- This shift toward intent driven, AI mediated testing could reshape how complex network and security environments are validated, reducing reliance on deep scripting skills and potentially changing the cost and speed profile of lab operations for Viavi’s customers.
- We will now see how this AI driven natural language testing framework might influence Viavi Solutions' broader investment narrative and risk profile.
Scan how Viavi Solutions’ AI driven testing move compares with other potential beneficiaries of this theme by reviewing a curated set of 53 AI infrastructure stocks in the broader network stack.
Viavi Solutions Investment Narrative Recap
To own Viavi Solutions, you need to be comfortable with a network test and optical technology specialist that is still loss making, yet tied to multi year data center and fiber upgrade cycles. The big swing factor near term is how quickly demand from data center and fiber projects translates into higher utilization of its Network and Service Enablement tools.
The largest near term risk remains sluggish wireless infrastructure and cyclical spending from service providers, which can keep earnings volatile. The new NITRO AI natural language testing framework looks directionally helpful but does not yet change the fact that integration of recent acquisitions and higher debt are still key execution watchpoints.
Among recent developments, the integration of the Model Context Protocol Server Framework into NITRO AI is most relevant. It lets Viavi Solutions plug TestCenter, CyberFlood and TeraVM directly into AI agent workflows. This matters if customers are standardizing around AI driven operations for lab and production environments over the next few years.
Operationally, that shift could make Viavi’s test platforms more embedded in data center, hyperscaler and security validation flows. This ties in with the existing catalyst around end to end network instrumentation demand. The main risk is execution. The firm must prove that AI mediated testing actually reduces complexity and downtime for customers, rather than adding another layer of tools to manage.
Viavi Solutions' current analyst narrative points to US$2.5b revenue and US$503.0m earnings by 2029. This implies 18.0% yearly revenue growth and a swing in earnings of about US$533.4m, from a loss of US$30.4m today to US$503.0m in that forecast year.
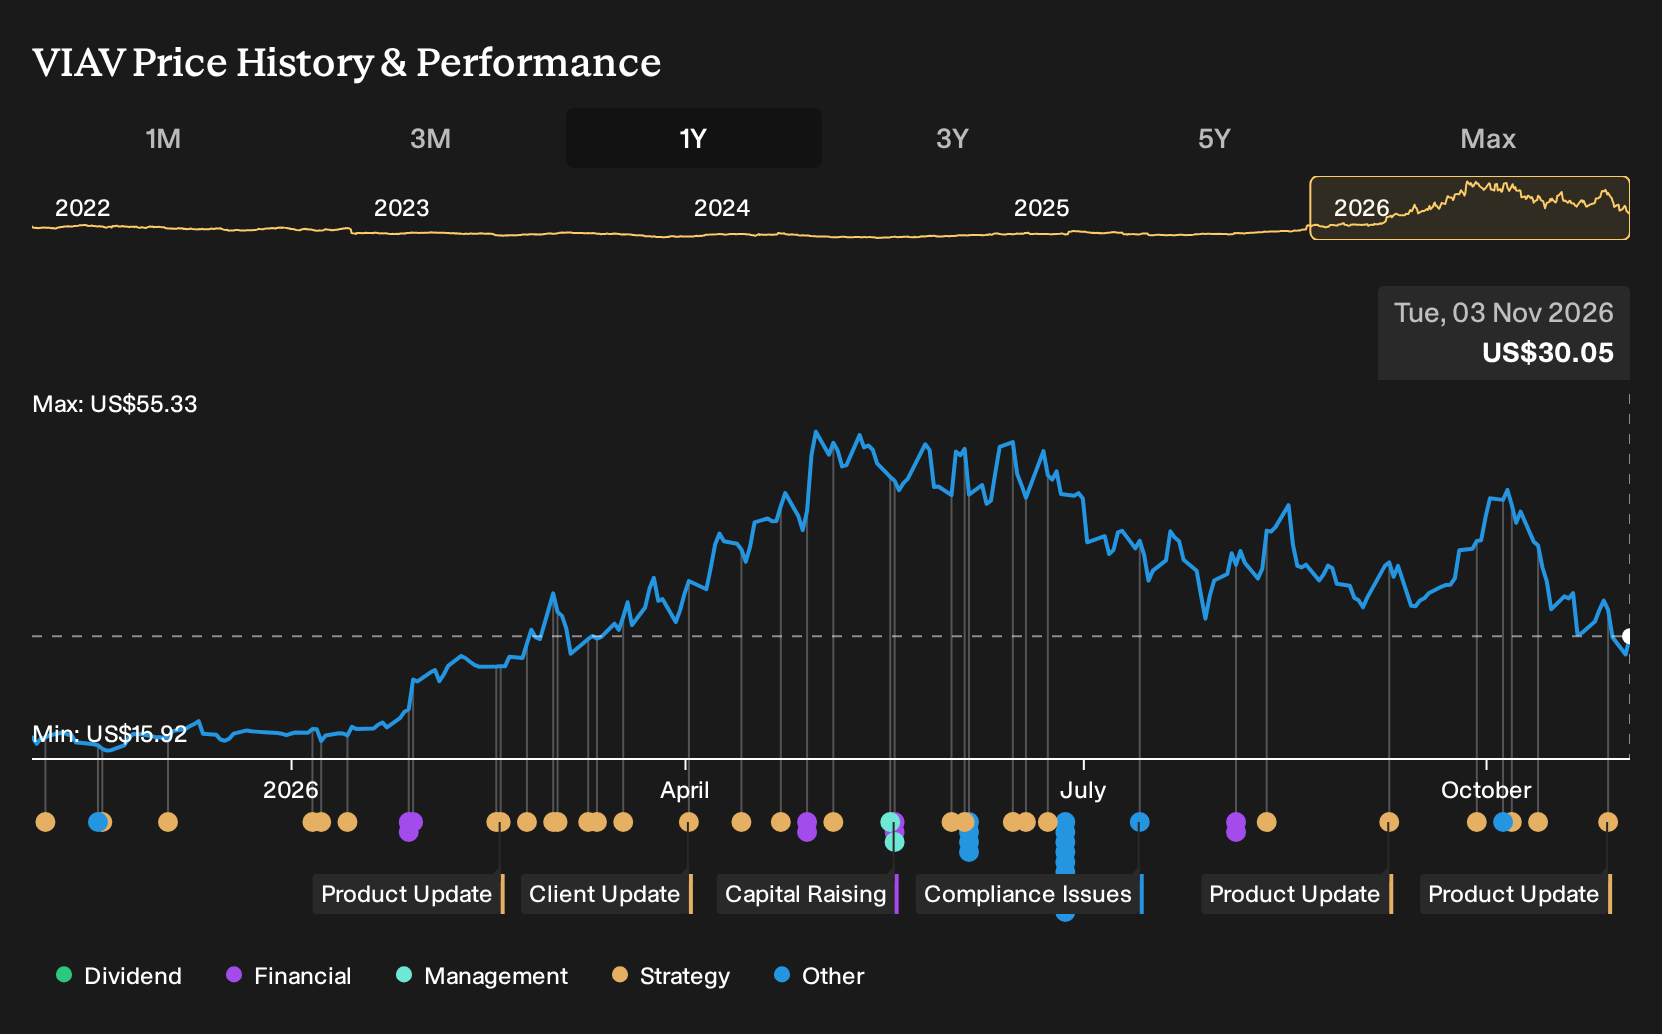
Uncover why Viavi Solutions' fair value indicates a 104% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One bullish twist on Viavi Solutions focuses on the AI centric test platforms as a possible earnings engine. The most optimistic analysts were already penciling in about US$2.6b of revenue and roughly US$499.5m of earnings by 2029 before this NITRO AI news. You can treat this MCP integration as a fresh reason to compare those upbeat forecasts with more cautious views and decide which perspective aligns more closely with your own.
Explore 3 other Viavi Solutions fair value estimates, including one that suggests up to 133% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Viavi Solutions research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Viavi Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Viavi Solutions' overall financial health at a glance.
Looking For More Investment Ideas Beyond Viavi Solutions?
If Viavi Solutions is on your radar, it can help to compare it with other companies that fit different risk and quality profiles. The Simply Wall St Screener offers several focused sets of stocks that you can use to stress test your thesis and broaden your watchlist.
- Prefer resilient balance sheets and steady fundamentals over excitement and headlines? Take a look at a curated list of solid balance sheet and fundamentals (24 results) that can help anchor the higher risk parts of your portfolio.
- Interested in shares that trade below their estimated worth with robust financial traits? Scan a focused group of 34 high quality undervalued stocks that might complement a position in Viavi Solutions.
- Rely on income as part of your strategy? Review a collection of 4 dividend fortresses that combine higher yields with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com