
Voya Financial (VOYA) Stock Climbs As Q3 Earnings Highlight Buyback Power
Voya Financial came into this earnings season with a reputation as a steady, capital-disciplined retirement and asset management platform. Q3 2026 results backed that up, with adjusted operating earnings of US$240 million, or US$2.60 per share, and a trailing 12‑month adjusted operating return on equity of 16.3%. The stock had already been grinding higher over the last month, then jumped another 3.7% to US$103.11 after the release. That reaction reflects investors rewarding one thing above all in this print: the power of excess capital generation and buybacks in a still fairly priced financial stock.
If you like how Voya Financial converts steady earnings into buybacks but want more options that show similar balance sheet discipline across the market, take a look at our list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$2,025 million vs. US$2,128 million (down about 5%)
- Net Income, Excluding Extra Items (Q3 2026 vs. Q3 2025): US$193 million vs. US$176 million (up about 10%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$2.13 vs. US$1.84 (up about 16%)
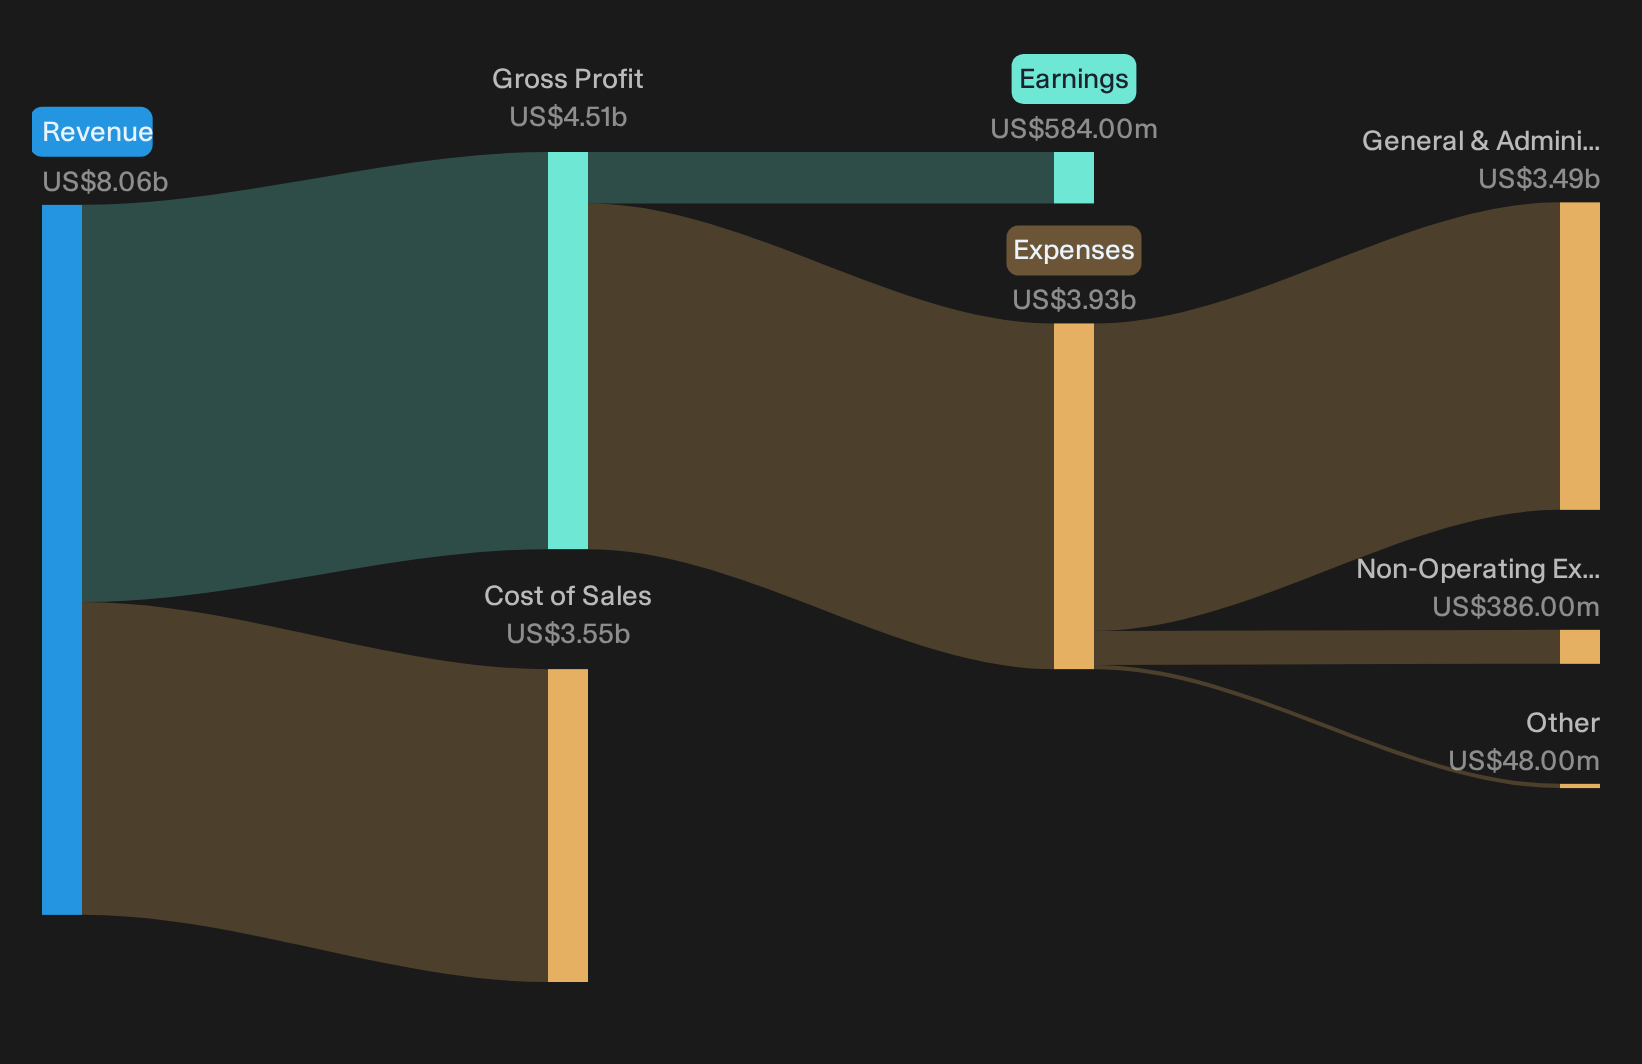
- Trailing 12-Month Net Income, Excluding Extra Items (Q3 2026 vs. Q3 2025 TTM): US$584 million vs. US$570 million (up about 2%)
Earnings only tell part of the story, since headline profit can move around while the underlying cash engine stays relatively steady. Investors who care about what they are actually paying for usually focus on the cash coming through the door.
On Voya Financial's numbers, if you look past the income statement and focus on the cash that could support buybacks and dividends, the stock could be a hefty 31% undervalued.
Voya’s Capital-Light Ambition Meets Hard Q3 Milestones
The bullish story centers on Voya Financial turning workplace relationships into a high margin, capital light engine.
"High recurring deposits in Retirement, strong client retention and a healthy pipeline in both Retirement and Investment Management, together with a consistent focus on expense discipline, can support relatively stable margins and returns on equity."
Q3 goes a long way toward supporting that view. Retirement delivered a roughly 38% operating margin with fee revenue now above 60% of segment sales. Participant accounts reached 10.3 million and plan retention stayed near 98%. Group wide, 16.3% trailing adjusted operating ROE and excess capital equal to about 95% of after tax operating earnings illustrate the cash conversion central to this thesis.
One Narrative disagrees with today's price. → See where this Narrative says Voya Financial should trade.
Voya Bear Case: Stop Loss Concerns Versus Q3 Reality
Bearish investors worry that Employee Benefits, especially Stop Loss, remains a problem child for Voya Financial rather than a repaired engine.
"Management describes a 2 year journey to restore Stop Loss profitability. However, faster claim emergence, a wider range of outcomes and the need to reserve at the high end of reasonable estimates signal that loss ratio volatility may persist, creating ongoing uncertainty for net margins and earnings quality in this line."
Q3 does not fully clear that hurdle. Stop Loss experience on the 2026 accident year is described as improving and reserves still sit at the high end of best estimate ranges. However, adjusted EPS only met expectations by a hair and followed a weak Q2. Loss ratios across life, supplemental health and voluntary benefits remain in flux, so earnings quality looks better, but not fully de risked.
Hunt Quiet Disconnects In Plain Sight
Voya Financial just showed how steady cash generation and disciplined capital use can reshape a quarter’s story. The real opportunity could sit in stocks that trade below what their underlying engines appear to justify.
- Company 1 - 43% below our estimate - turn rising orders for large LED display systems into higher margin software, services and improved factory utilization.
- Company 2 - 42% below our estimate - expand protective film capacity so carmakers and dealers access coatings and installation services from one supplier.
- Company 3 - 48% below our estimate - grow a dense network of app driven coffee outlets while testing whether newer stores sustain enough traffic.
Three companies from the same screener. Open all 34 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com