
Alamo Group (ALG) Stock Sinks As Q3 Earnings Absorb Restructuring Hit
The market came into Alamo Group’s Q3 2026 release already cautious, with the stock down over the past three months and closing at about US$148.49 after a 2.8% slide today. Traders reacted quickly to the headline gap between reported GAAP earnings per share of US$0.17 and adjusted EPS of US$2.06, focusing on the weaker figure and pushing the share price lower.
The key development, however, is in the margin profile. Adjusted EBITDA of US$52.4 million at a 13% margin indicates the core equipment franchise is still generating solid returns, while one-off divestiture and restructuring items affect the headline profit line and contribute to the sharp initial selloff.
Like the Alamo Group margin profile but uneasy about headline earnings noise from one off items and restructuring? See how other equipment makers stack up in our list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$403.1 million vs. US$420.0 million (top line lower year on year, partly reflecting divestiture related sales loss)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$2.0 million vs. US$25.4 million (profitability sharply lower compared with the prior comparable period)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.17 vs. US$2.11 (earnings per share fell significantly year on year)
- Adjusted EBITDA Margin (Q3 2026 vs. Q3 2025): 13.0% vs. prior year level not specified (current margin shows the underlying equipment operations generating double digit profitability despite lower reported earnings)
Earnings paint one picture, but if you care about what NYSE:ALG might actually be worth, the cash moving through Alamo Group's operations matters more than a single soft quarter. On Alamo Group's cash flows alone, the stock could be a whopping 45% undervalued.
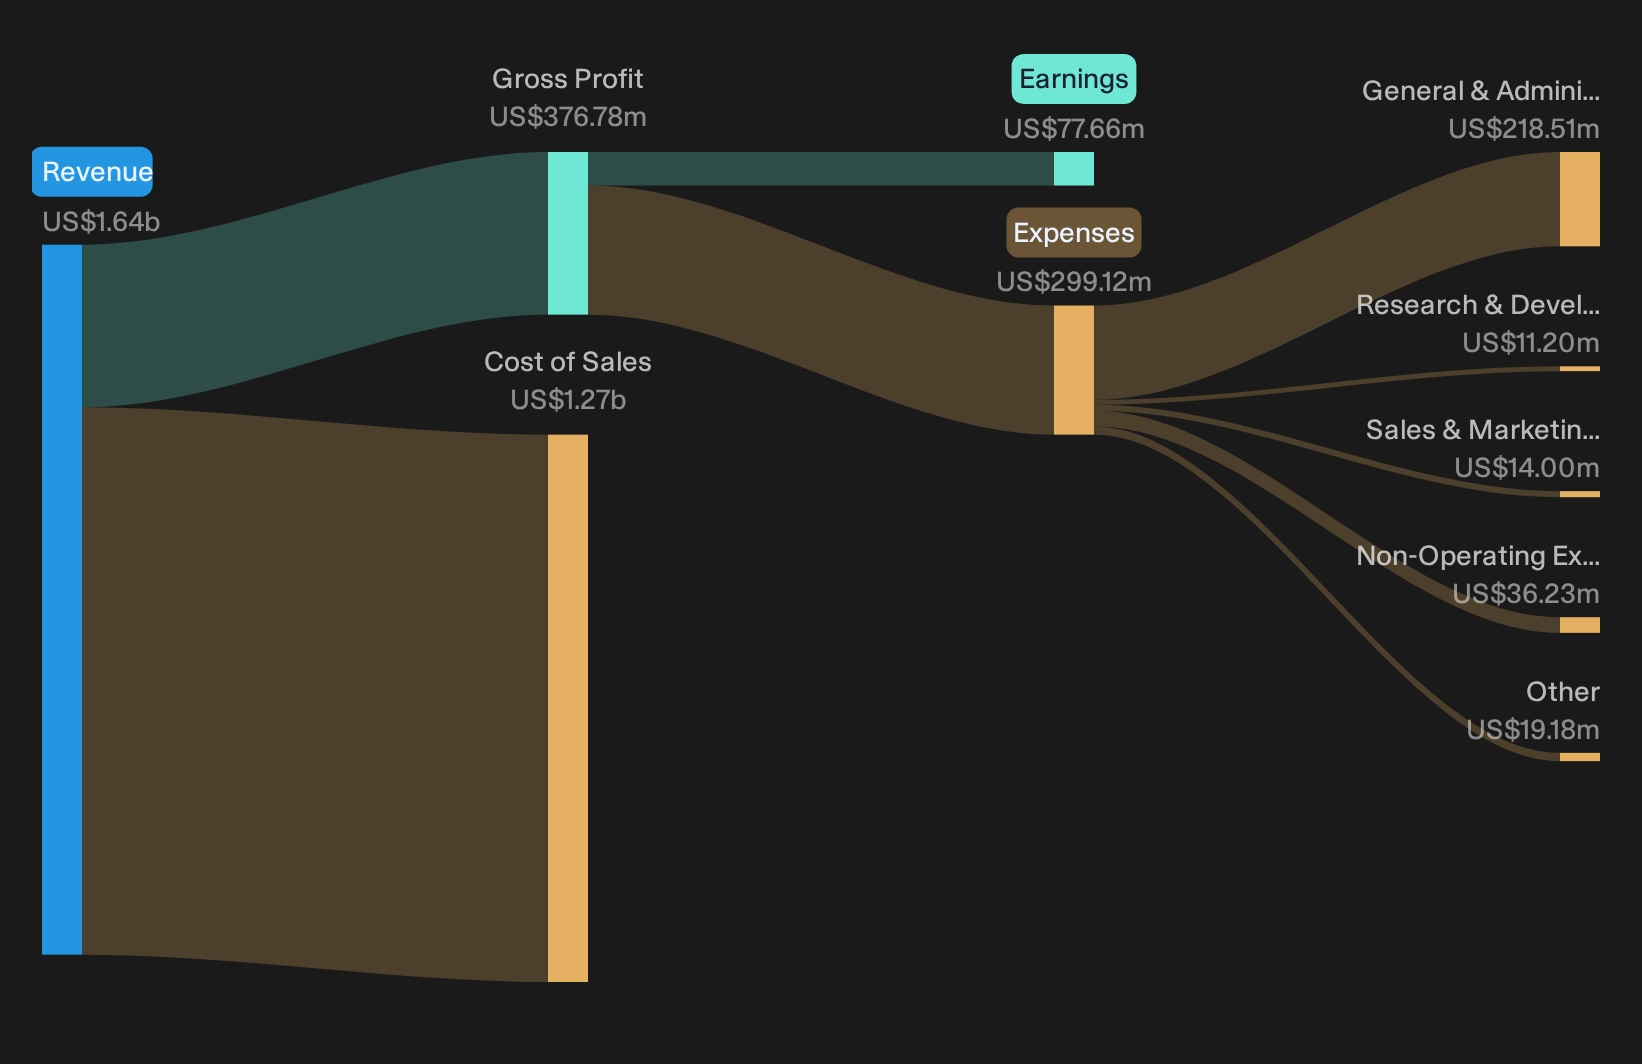
Alamo Group margin thesis meets a mixed reality check
Bulls argue that Alamo Group can turn product mix, procurement and aftermarket levers into a structurally better earnings engine.
"The main factor that has to go right is that Alamo Group converts its margin programs, procurement savings, aftermarket initiatives and tuck-in acquisitions such as Petersen and Ring O Matic into lasting improvements in profitability across both divisions."
Q3 gives partial support. Vegetation Management moved toward its margin ambition, with adjusted EBITDA margin rising to 12.5% and helped by pricing, procurement and parts mix. Group adjusted gross margin ticked up to 24.7%. At the same time, Industrial Equipment margin slipped to 13.4% and adjusted EPS fell versus last year, so profitability progress is uneven and not yet broadly "lasting."
Bear case on acquisitions and margin risk still on the table
Skeptics focus on whether acquisitions and restructuring could drag on profitability rather than help it.
"Alamo Group’s capital deployment plan depends heavily on a pipeline of tuck in acquisitions such as Petersen and Ring O Matic. However, recent deals have brought higher interest expense, restructuring costs and facility consolidations, so any acquisition that fails to integrate smoothly or falls short of the 23% to 24% adjusted EBITDA margin profile cited for Petersen could dilute margins, reduce free cash flow conversion that recently ran at 134% of net income and leave earnings and cash generation below the levels implied in the current narrative for the stock."
Q3 results show this concern is live. Reported GAAP EPS dropped to US$0.17, weighed down by US$33.3 million of divestiture and restructuring charges tied to portfolio cleanup. Econ and Petersen are framed as accretive, and free cash flow over the last twelve months remained strong at US$137.1 million. Still, lower Industrial Equipment margin and a step down in adjusted EPS versus last year indicate the integration and restructuring phase is hitting earnings before the anticipated acquisition benefits are fully visible.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Hunt For Mispriced Earnings Power
Alamo Group just showed how a messy quarter can blur what is actually changing under the surface. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 28% below our estimate - turns rising digital engagement and underpenetrated credit demand into fee and lending income across multiple financial services lines.
- Company 2 - 39% below our estimate - converts high volume lidar shipments into scaled hardware programs as customers move from pilot phases into full production adoption.
- Company 3 - 18% below our estimate - shifts NAND output toward higher density enterprise drives as data center and edge device workloads demand more storage per unit.
Those are three of them. See every one of the 34 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com