
Inspire Medical Systems (INSP) Stock Sinks As Q3 Results Expose Margin Strain
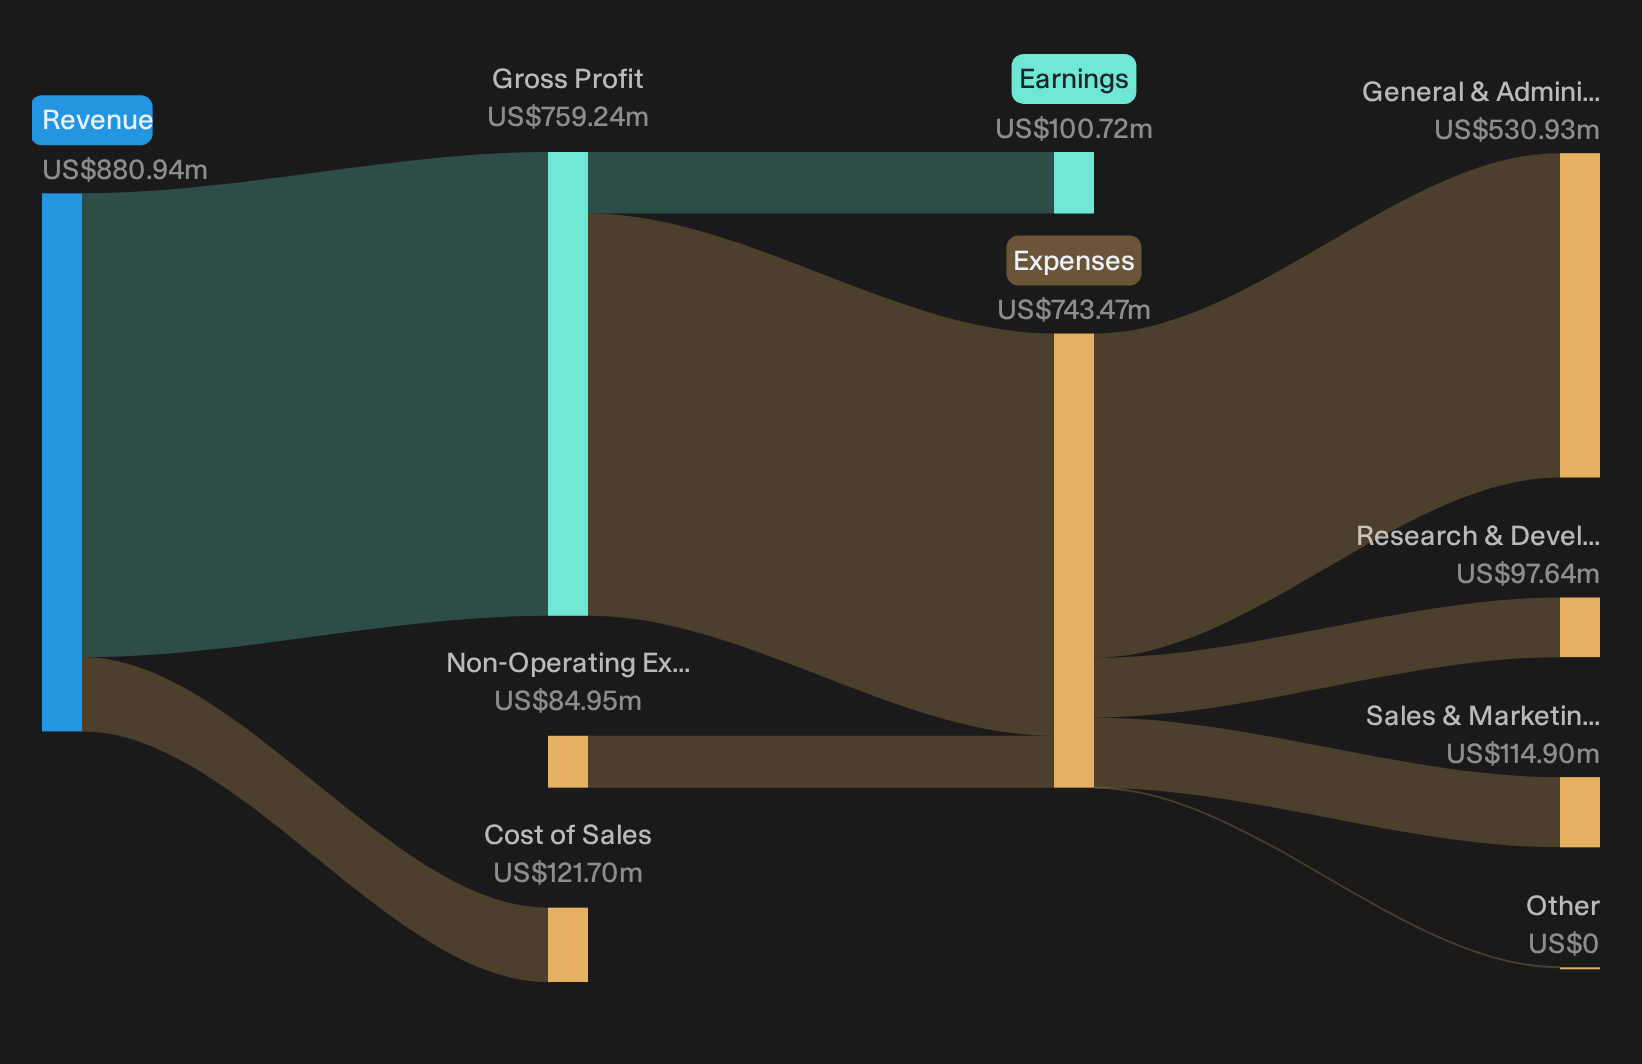
Inspire Medical Systems just handed investors a rough wake up call. The stock dropped about 8% to US$61.90 after the Q3 2026 report, extending a weak run over the past month. On the surface, a GAAP loss per share of US$0.84 and revenue of US$206.7m looked harsh.
The real story sits in the margin squeeze. Operating loss hit US$28.7m as legal and restructuring costs pressed on profitability, even as gross margin held at 86%. Traders focused on the hit today. Anyone thinking in years will focus on whether those costs clear and the earnings power underneath can re emerge.
Love Inspire Medical Systems' 86% gross margin but concerned about operating losses and one off legal and restructuring hits? Compare it with a screener of profitable companies with stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$206.7m vs. US$224.5m (fell 7.9% year over year)
- Net Income/Loss (Q3 2026 vs. Q3 2025): loss of US$24.4m vs. profit of US$9.9m (moved from profit to loss, affected by legal and restructuring charges)
- Basic EPS (Q3 2026 vs. Q3 2025): loss of US$0.84 per share vs. profit of US$0.34 per share (shifted from positive to negative earnings per share)
- Gross Margin (Q3 2026 vs. Q3 2025): 86% vs. roughly 85.8% (remained very high and increased slightly year over year)
INSP bull case hinges on execution milestones
The optimistic pitch on Inspire Medical Systems rests on execution turning a product ecosystem into better economics, not just on future promises.
"The main requirement is that Inspire Medical Systems executes on Project Horizon and the new reimbursement and coding framework so that the planned capacity to reinvest in growth translates into higher quality patient flow and more efficient procedures."
Q3 shows partial progress. Project Horizon is freeing an estimated US$30m of annual capacity and adjusted operating expenses fell to US$176m. Adjusted operating income stayed positive at US$1.9m and operating cash flow reached US$46.4m in the quarter. At the same time, revenue still declined 7.9% year over year and coding headwinds cut an estimated US$30m from Q3 sales, so the reinvestment flywheel is not yet visible in top line trends.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Inspire Medical Systems bear case meets real margin strain
Bears argue that legal exposure could siphon cash away from growth and into cleanup. The latest quarter gives that worry something concrete to point to.
"The investigations into potential fiduciary breaches around the Inspire V launch introduce a risk that management attention and future cash could be diverted to legal and remediation costs, which may weigh on net margins and earnings."
Q3 featured US$7m of legal settlement and fees alongside US$24.1m of restructuring charges, swinging Inspire Medical Systems from prior year operating profit to a loss. Operating cash flow of US$46.4m still appears healthy, yet margin volatility and the 7.9% revenue decline mean this concern is not yet disproved.
Hunt For Dislocated Fundamentals
Inspire Medical Systems recently showed how one quarter can reshape expectations without resolving the long term debate. The real opportunity is finding stocks that could be undervalued before the market potentially closes any gap.
- Company 1 - 42% below our estimate - target higher margin films and services as manufacturing and supply chain expansion reshapes capacity.
- Company 2 - 45% below our estimate - convert a record backlog of technology heavy projects into revenue as data center and modular construction demand absorbs crews.
- Company 3 - 48% below our estimate - use a fast expanding store base and digital ordering to test new drinks that increase visit frequency across the network.
Three companies from the same screener. Open every one of the 34 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com