
Toromont Industries (TSX:TIH) Stock Price Slides As Q3 Earnings Beat Meets Premium P\E
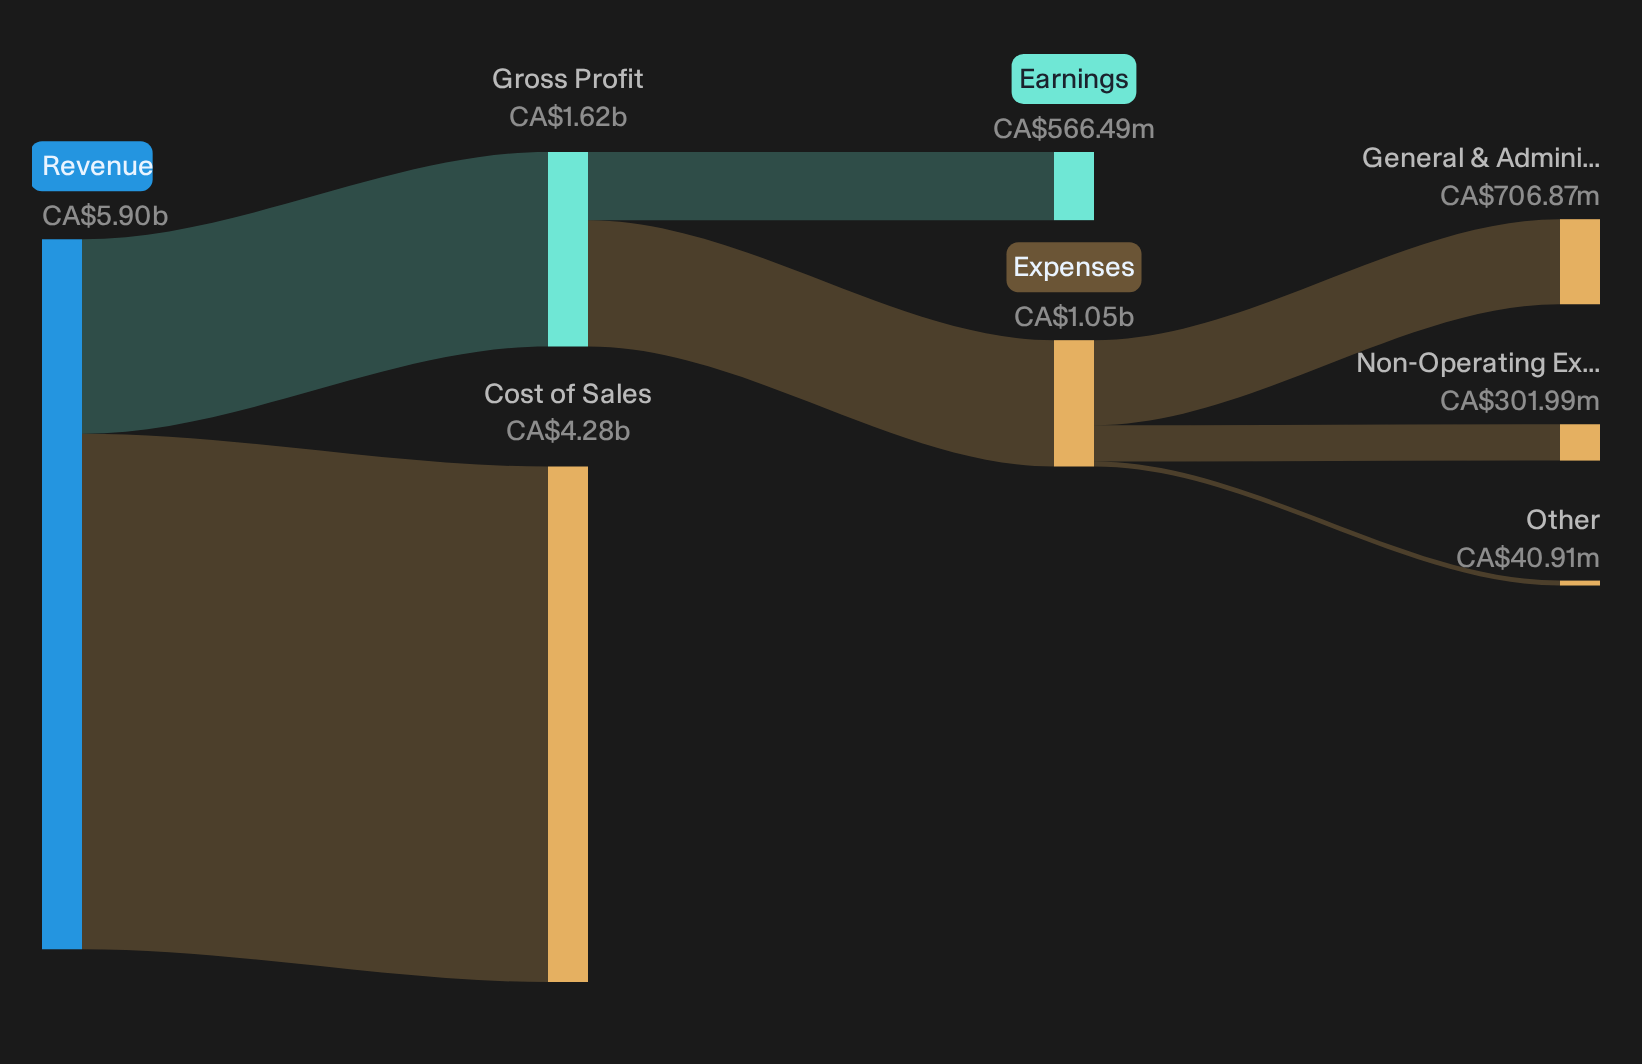
Toromont Industries came into this earnings release with a premium reputation and a premium P/E of 30.2x, yet the share price has slipped 11.5% over the past month and 7.6% over the past quarter. That pullback met a Q3 2026 report that delivered heavy equipment fundamentals investors usually want to see. Revenue reached about CA$1.65b and basic earnings per share hit CA$2.35, both firmly supported by a larger backlog that management expects to convert over the next year. The gap between a softer stock and these stronger operating numbers is now the core question for holders.
Love Toromont Industries’ solid Q3 order book but uneasy about paying a premium P/E while the share price drifts? Consider a basket of industrials that pair resilient demand with more grounded valuations in our 4 high quality undervalued stocks.
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs Q3 2025): CA$1,652.1m vs. CA$1,314.9m (up about 26%).
- Net Income, Excl. Extra Items (Q3 2026 vs Q3 2025): CA$192.1m vs. CA$140.6m (up about 37%).
- Basic EPS (Q3 2026 vs Q3 2025): CA$2.35 vs. CA$1.73 (up about 36%).
- Gross Margin (Q3 2026 vs Q3 2025): 29.1% vs. roughly 26.7% (up about 240 basis points).
Toromont bull case: AVL and services under the microscope
For the optimistic view on Toromont Industries, the key question is whether AVL and services are truly turning bookings and capital spend into durable earning power.
"The rapid ramp-up of AVL's production capacity, ongoing integration, and accelerated facility expansion in the U.S. positions Toromont Industries to capitalize on growing North American data center power demand."
Q3 results point in that direction. AVL revenue reached about CA$218m versus CA$78m a year earlier, and AVL contributed to the CA$892m of total bookings and CA$2.9b backlog. Gross margin expanded 240 bps, while product support revenue in the Equipment Group increased double digits, helped by more technicians. That combination suggests early progress on both higher capacity and recurring service activity.
Toromont bear case: CIMCO, charges and cyclicality tested
On the cautious side, you are weighing whether refrigeration softness and accounting noise are already eroding the quality of Toromont Industries’ growth.
"CIMCO is experiencing weaker profitability, with operating income down and operating margin lower due to softer package margins and higher costs."
Q3 shows only partial relief. CIMCO revenue advanced 23% and operating income was slightly higher in the quarter, yet gross margin fell about 410 bps and backlog declined 5% to roughly CA$324m. Large AVL purchase commitment expenses of CA$14.3m in Q3 and CA$82.5m year to date continue to weigh on reported earnings, while recent 30 day and 90 day share price declines of about 11% and 8% indicate that cyclical and execution worries remain in focus.
One Narrative disagrees with today's price. → See where this Narrative says Toromont Industries should trade.
Hunt For Quiet Fundamental Shifts
Toromont Industries just showed how a strong quarter and a softer share price can live side by side. The real opportunity could sit in stocks that the market has yet to fully reprice.
- Company 1 - 30% below our estimate - builds recurring engineering fee work by integrating acquisitions and channeling projects through shared digital delivery centers.
- Company 2 - 46% below our estimate - reaches higher spending shoppers via premium malls while a faster data driven supply chain keeps inventory tight and markdowns contained.
- Company 3 - 32% below our estimate - opens new boutiques that reportedly repay build costs quickly as a growing digital channel attracts more customers into the same brand ecosystem.
Three companies from the same screener. Open all 4 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com