
The Bet Johnson Controls Holders Made
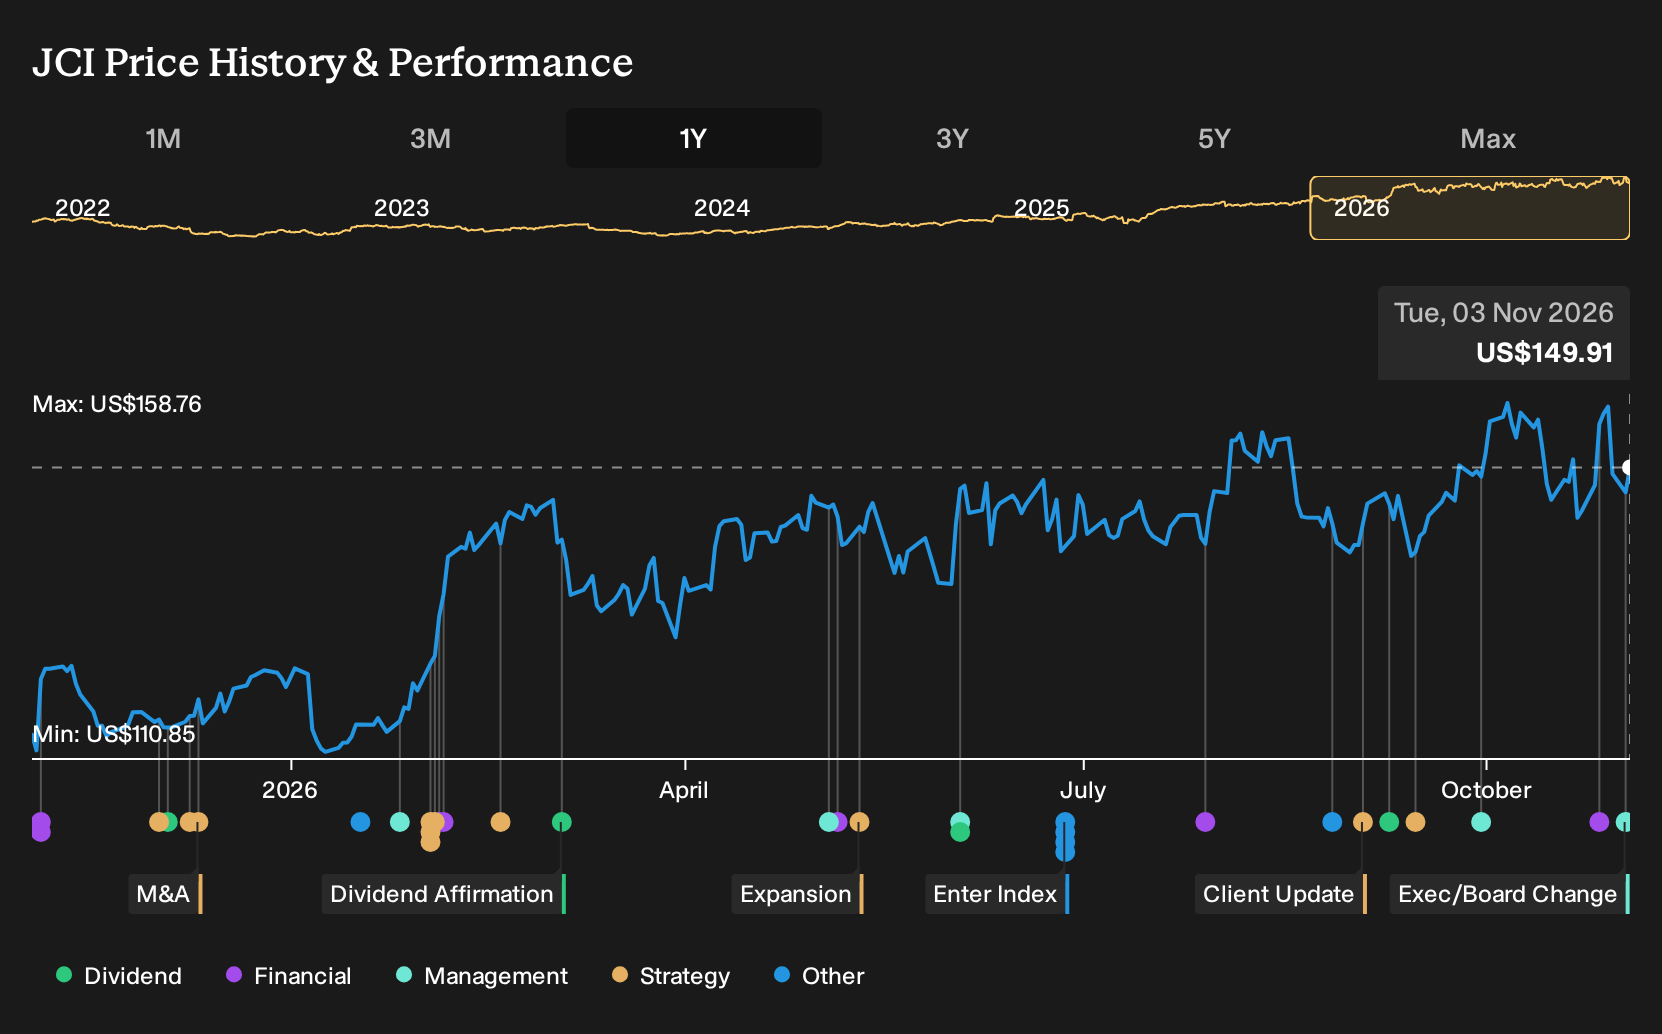
If Johnson Controls International was on your watchlist instead of in your portfolio, the past year may feel like a miss. Holding Johnson Controls International over the past year would have returned 36.6%, including dividends. That outcome invites a simple question. Back on 3 November 2025, when analysts disagreed sharply on how far OpenBlue, Lean adoption and data center cooling could reshape the business, what clues were already on record that these assumptions might prove too conservative or too cautious?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Johnson Controls International is not the only name tied to this theme. Zero in on 53 AI infrastructure stocks and compare how each one is priced.
The Argument Investors Had To Weigh On Johnson Controls International
The shares cost US$113 at the start of the period, and Johnson Controls International sat between two very different stories that both sounded reasonable.
The bullish Narrative put Fair Value at US$131, or 16% above the start price. It leaned on OpenBlue, smart cities, and data center cooling, plus an assumption that revenue could rise 5.8% a year with profit margins moving from 9.6% to 13.1% by around 2028.
The bearish view anchored Fair Value at US$79, about 30% below the start price. That storyline focused on mature markets, geopolitical risk, and pressure on building demand, even while assuming more modest 3.5% annual revenue growth and margins reaching 12.8% by 2028.
What The Results Changed For Johnson Controls International
Johnson Controls International spent the period backing the bullish story with hard numbers. Total revenue moved from US$6,442m in Q4 2025 to US$7,113m in Q4 2026, while net income excluding extra items went from US$267m to US$967m and net margin shifted from 4.1% to 13.6%. That combination supported the optimistic case more than the cautious one.
The debate that mattered was not about OpenBlue slogans; it was about whether efficiency and data center demand would show up in the income statement. When you test a similar claim elsewhere, track revenue, net income and margin together across several quarters rather than relying on guidance or commentary.
What Johnson Controls International’s Price Now Demands
Johnson Controls International trades at US$150 after a 36.6% gain over the past year, and the selected cautious Narrative now places its Fair Value below that level. The gap reflects concern that data center optimism and order strength already feature heavily in the valuation.
The Narrative argues that for today’s price to hold, you need confidence that order growth, AI cooling projects and service ambitions offset PFAS cash outflows and any delay in turning backlog into recurring high margin work.
"The main requirement is that Johnson Controls International converts its strong order growth, business system gains, and portfolio reshaping into sustained high single-digit organic revenue growth and 30%+ operating leverage, without material setbacks from issues such as PFAS remediation or data center project delays."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
How Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 28% below our estimate - uses recent acquisitions and deposit restructuring to build a broader lending and funding base.
- Company 2 - 33% below our estimate - supplies GPU platforms and software that major data centre operators rely on for AI workloads.
- Company 3 - 23% below our estimate - integrates acquired test and measurement operations to support utilities modernising grids and diagnostic systems.
That is three of the list. See the full list of 35 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com