
ReNew Energy Global (RNW) Stock Ignores Q2 Earnings Strength For Now
ReNew Energy Global barely budged on the screen today, inching up 0.6% to $6.89 after its Q2 FY27 report. The move feels modest next to the earnings print. Profit after tax reached ₹6,422m on revenue of ₹49,619m, locking in another quarter of solid profitability for a capital intensive renewables operator.
Short term traders might shrug at a flat chart over the past week. Long term holders will likely focus on the expanding adjusted EBITDA profile and the run rate cash flow potential implied by a 20.5 GW committed portfolio.
If you value the consistency in ReNew Energy Global's profitability profile but also want greater balance sheet strength and clearer cash flow visibility across your holdings, compare this quarter against our list of solid balance sheet and fundamentals stocks (23 results).
Q2 2027 Earnings Summary
- Revenue (Q2 FY27 vs Q2 FY26): ₹49,619m vs. ₹36,266m (up about 37%)
- Net Income (Excl. Extra Items) (Q2 FY27 vs Q2 FY26): ₹6,422m vs. ₹4,675m (up about 37%)
- Basic EPS (Q2 FY27 vs Q2 FY26): ₹17.61 vs. ₹12.87 (up about 37%)
- Trailing Net Profit Margin (Last 12 Months vs Prior Year): 8.4% vs. 6.9% (margin improved)
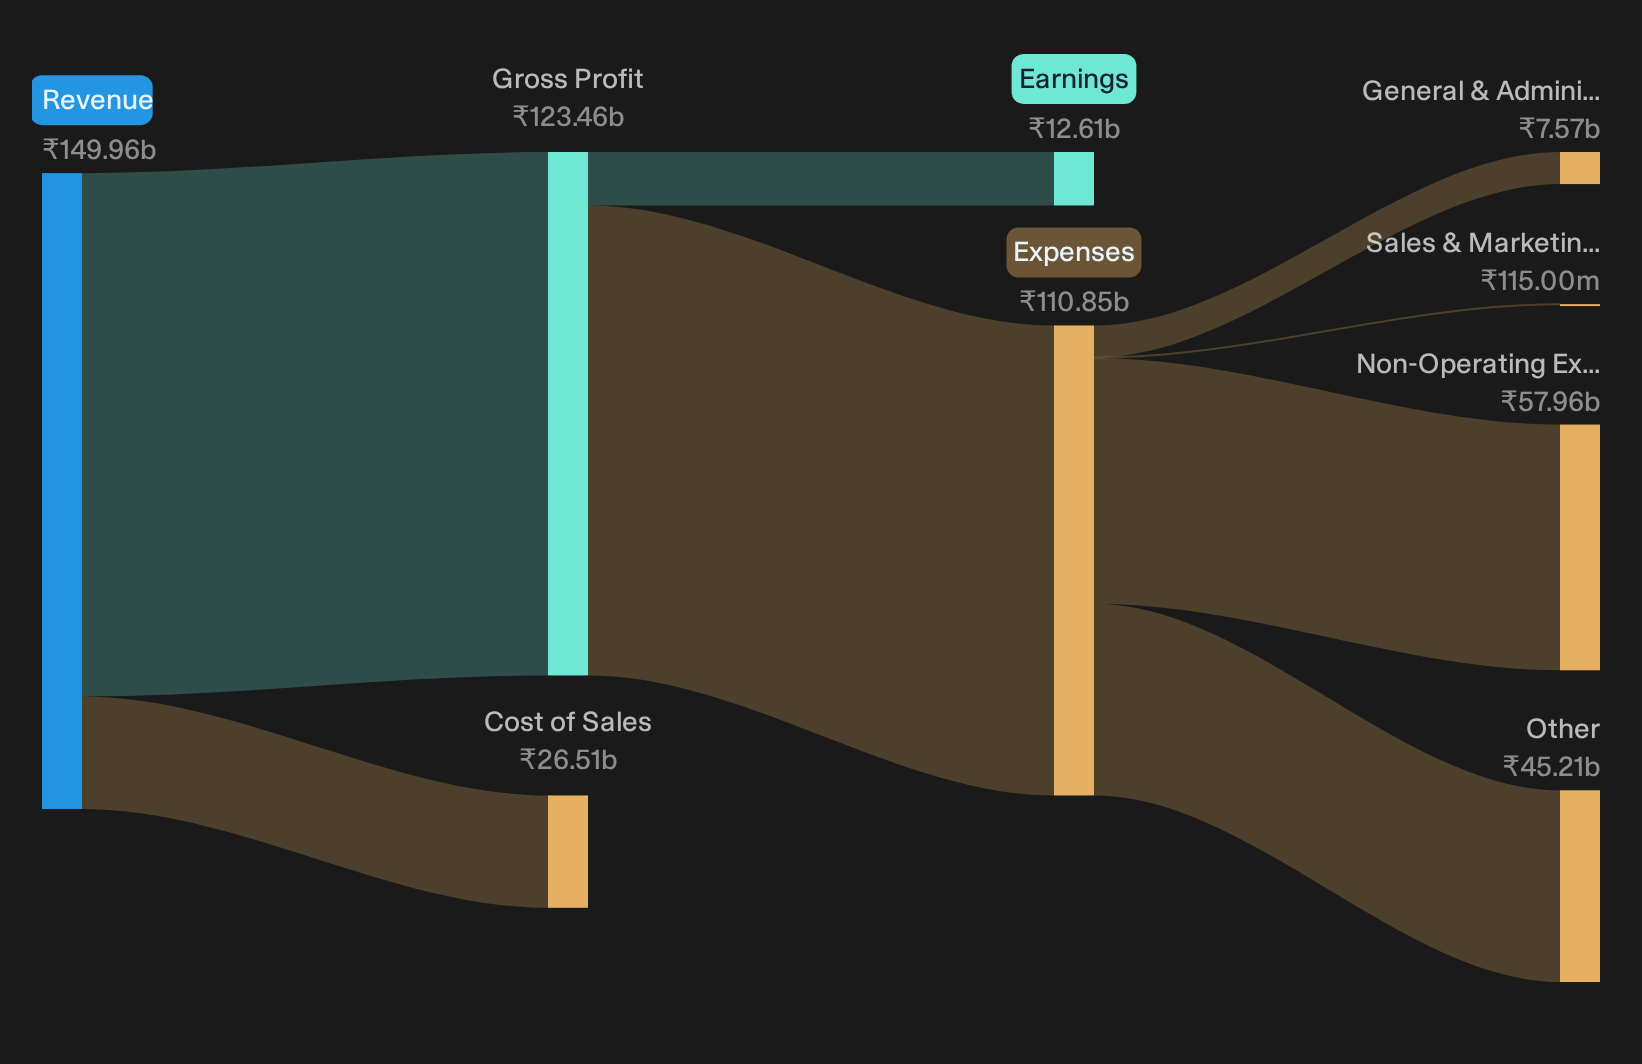
Tired of scrolling through paragraphs of earnings commentary and raw figures for ReNew Energy Global? See the full visual picture of the business, with a clear focus on its profitability and earnings trend, in the company report for ReNew Energy Global.
ReNew Energy Global’s Capital Efficiency Story On Trial
The bullish pitch is that ReNew Energy Global can turn a smarter project mix and a scaled factory footprint into steadier earnings power.
"The main requirement is sustained execution on the shift toward solar plus BESS, along with ongoing balance sheet deleveraging, so that cash flow remains predictable despite project, grid and regulatory risks."
On execution, Q2 adjusted EBITDA of ₹33.6b with ₹4.1b from external manufacturing shows the solar platform already pulling its weight. Cash flow to equity above ₹23b in H1 and a lower 5.3x debt to EBITDA ratio for operating projects indicate early progress on the deleveraging and cash conversion side of that thesis.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
ReNew Energy Global: Earnings Quality Concerns Not Fully Closed
The bearish worry is that ReNew Energy Global can grow megawatts and revenue while earnings stay fragile and erratic.
"Although ReNew Energy Global is adding utility scale capacity and building a 27 GW pipeline, the recent quarter where revenue of ₹39.55b exceeded estimates yet EPS still came in at a loss of ₹14.41 per share and missed expectations by ₹4.53 points to a project mix that can generate volume without converting into stable earnings, which could challenge future net margins and EPS quality."
This quarter does undercut that exact pattern. Q2 FY27 profit after tax of ₹6,422m and trailing 8.4% net margin show capacity is now translating into earnings. Yet the share price barely moved and guidance leans on capital recycling and manufacturing gains, so investors still do not have a long track record that proves this higher quality mix will hold through DSM costs, curtailment risk and upcoming manufacturing margin normalization in FY27.
Hunt Quiet Mispricings Before Consensus
ReNew Energy Global just reported a solid quarter that coincided with a muted share price reaction. The real opportunity is finding stocks that could be undervalued before the market closes the gap.
- Company 1 - 39% below our estimate - turns years of pilot lidar projects into large scale production shipments embedded in vehicle programs.
- Company 2 - 30% below our estimate - uses an AI focused networking and cloud stack to push more of its hardware footprint into recurring service contracts.
- Company 3 - 17% below our estimate - extends a solar tracker platform into storage, inverter and software offerings that deepen stickiness with utility scale project developers.
Three companies from the same screener. Open all 35 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com