
3 Trucking Stocks Investors Are Watching As Freight Rates And Diesel Costs Rise
Freight capacity keeps tightening, diesel sits above $6 a gallon, and transportation prices are climbing, which puts pressure on shippers but reshapes the playing field for carriers. That mix of strain and opportunity is where potential mispricing can appear. This article walks through three North American trucking and logistics stocks that appear closely tied to these shifts so you can decide whether they deserve a closer look on your watchlist.
The three trucking and logistics stocks below are only a starter set from this theme. The full screen surfaced another 20 North American carriers and freight specialists with equally compelling business stories that are not covered here.
If you want to move straight from ideas to actionable research, head into the North American Trucking & Logistics Carriers screener to identify, compare, and analyze the highest conviction plays for your watchlist.
Old Dominion Freight Line (ODFL)
Old Dominion Freight Line is the pure trucking carrier many investors look for in this theme, with its network of less than truckload routes and value added freight services giving direct exposure to tight capacity and rising transport rates across North America.
Old Dominion Freight Line runs a North American less than truckload network, handling regional, inter regional, and national freight plus expedited and related logistics services. All US$5.8b of revenue comes from these LTL operations and the company has a market value of roughly US$36.5b.
Old Dominion Freight Line is focused on maximizing operating efficiencies and reducing discretionary spending to protect their operating ratio, and the company now reports a 450 basis point improvement to a 70.1% operating ratio in Q2 2026 with direct operating costs 200 to 250 basis points better than a prior record quarter.
The real swing factor is how that efficiency focused freight network handles one unresolved pressure that could sharply shift pricing power and profitability.
That unresolved pressure is exactly where things can start to decouple for Old Dominion Freight Line, and the full narrative for Old Dominion Freight Line lays out how that tension could reshape its edge.

Saia (SAIA)
Saia is one of the purest expressions of the trucking and logistics theme, with a nationwide less than truckload network that feels every shift in freight capacity and pricing power as industrial demand, diesel costs, and supply constraints ripple through North American shipping.
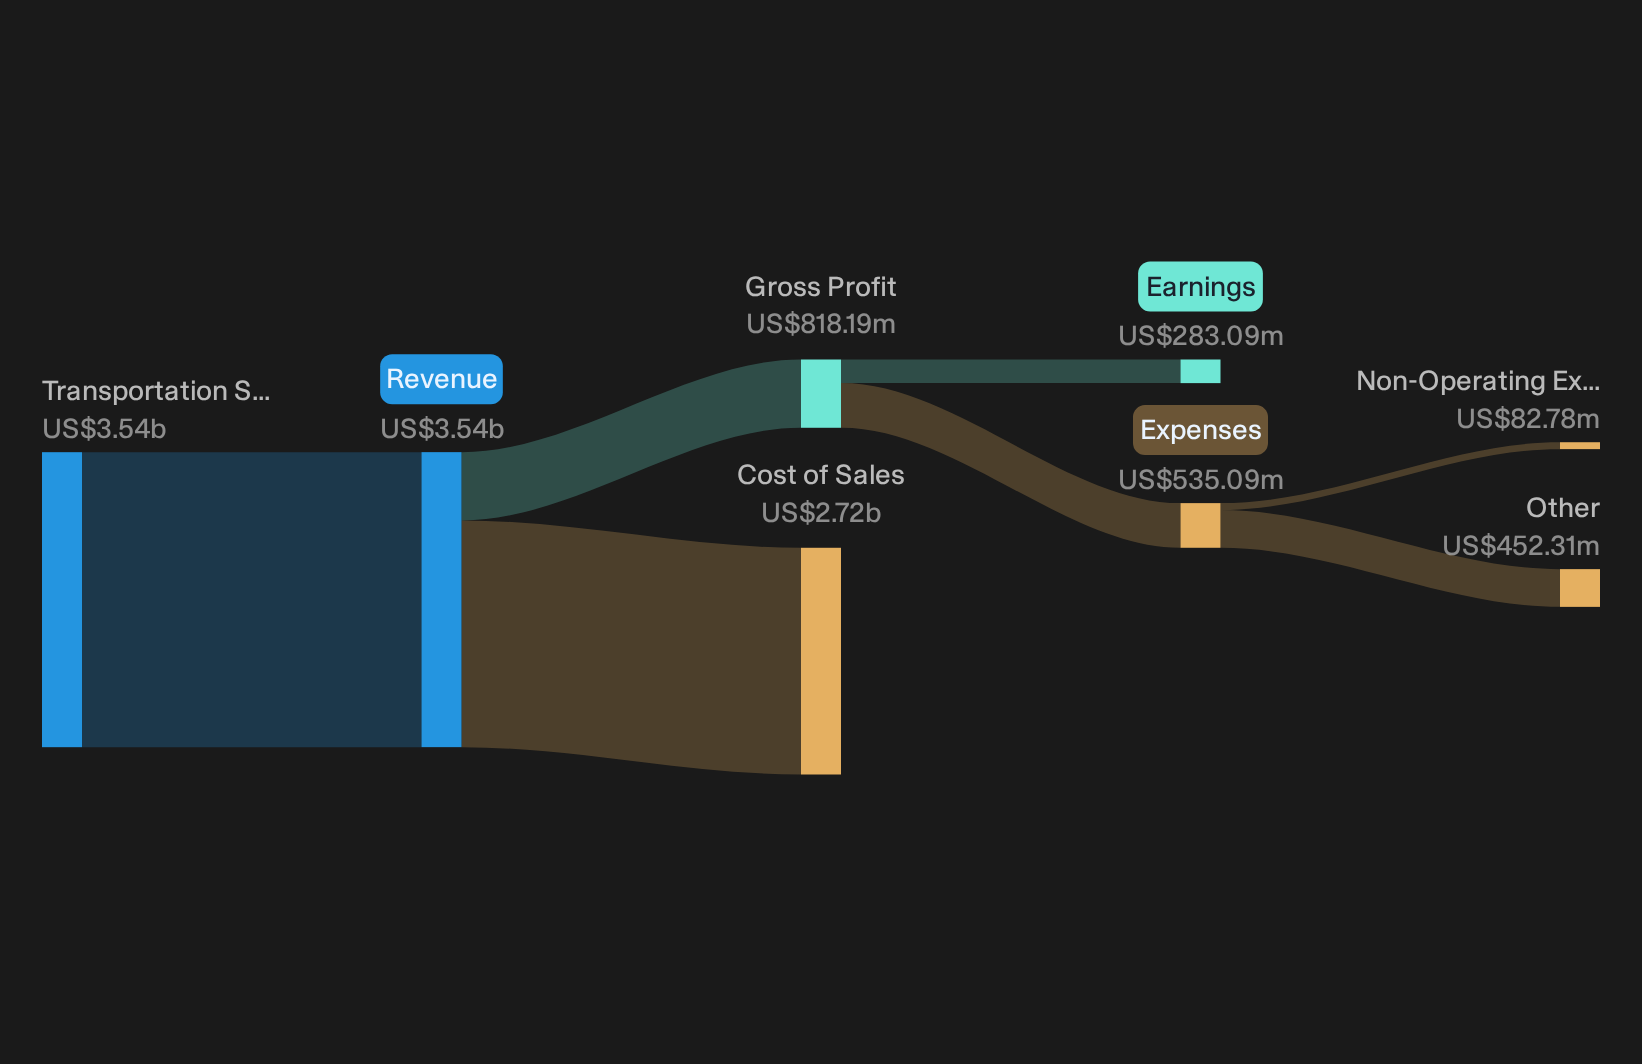
Saia runs a North American less than truckload freight network moving shipments between 100 and 10,000 pounds, with brokered truckload, expedited moves, and logistics services layered on top. It generated about US$3.5b from transportation services in the United States and has a market value near US$9.2b.
The ongoing expansion and maturation of Saia's national terminal network, combined with densification of the 218 plus facilities added or upgraded since 2022, is still early in its ramp. It is beginning to show operating ratio improvement at newer sites. This could support higher shipment volumes, revenue growth and better net margins as more terminals move from the low 90s operating ratio toward mature system levels.
What investors really have to watch is how a single cost pressure interacts with that expanding footprint to decide where future margins settle.
That cost pressure is the fulcrum. The full narrative for Saia traces how Saia's expanding network could turn that into either accelerating operating leverage or a margin squeeze risk.
Marten Transport (MRTN)
Marten Transport gives this trucking and logistics screen direct exposure to tight refrigerated capacity, with a temperature controlled truckload fleet across the U.S., Mexico, and Canada. It produced about US$445 million from truckload, US$264 million from dedicated services, and US$152 million from brokerage, and the stock carries a market value near US$957 million.
For tight capacity and higher freight rates, Marten Transport provides trucking heavy exposure through temperature controlled truckload and dedicated fleets that run directly into those pricing trends. Recent Q3 results showed higher truckload rates and better operating income even as fuel and health costs pressed on margins. This makes what happens when that pressure either eases or intensifies especially important for this freight story.
That turning point is exactly where the Marten Transport story could accelerate, and the analysis report for Marten Transport breaks down how fuel, healthcare costs, and pricing power really interact.

Seeking Alternatives Before The Crowd
Fresh opportunities move fast as momentum builds, prices break out, and weaker ideas start dropping. Scan under the radar for now, before the edge fades, and act promptly.
- Spot cash generative leaders early by sorting through a curated list of solid balance sheet and fundamentals (24 results) before the strongest balance sheets get fully priced by the crowd.
- Consider specialized miners with early upside potential by reviewing the hand picked 33 best rare earth metal stocks while sentiment is still mixed and liquidity remains reasonable.
- Follow structural demand trends by scanning the focused 42 power grid technology and infrastructure stocks while grid spend is building momentum and the best operators remain under followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com