
Marvell (MRVL) Stock Looks Reasonable Following Its 237% Three Year Run
Marvell Technology has surged over the past few years, then sold off sharply in recent weeks, which puts fresh focus on a simple issue for investors: whether the current share price can still be squared with the earnings power of the business. With sentiment whipsawing around AI infrastructure plays, the central question is what portion of that excitement Marvell’s profit stream can realistically support.
- Over the past 3 years the stock has returned 237.3%, so a lot of future profit and cash generation may already be reflected in the valuation investors are debating today.
- The planned all stock acquisition of Lumentum, valued at about US$115b, could reshape Marvell’s earnings profile by adding optical assets while also increasing share count and potentially affecting how much profit is attributable to each share.
- Your read on Marvell Technology is one view; the desks covering it have another. See what analysts think Marvell Technology's shares could be worth.
The issue now is whether that kind of price performance and deal activity is justified by what Marvell’s earnings currently support and what they are expected to deliver over time.
If you are weighing Marvell Technology against other ways to play AI infrastructure, it can help to compare it with companies in 53 AI infrastructure stocks.
Where Does Marvell Technology Sit on Earnings?
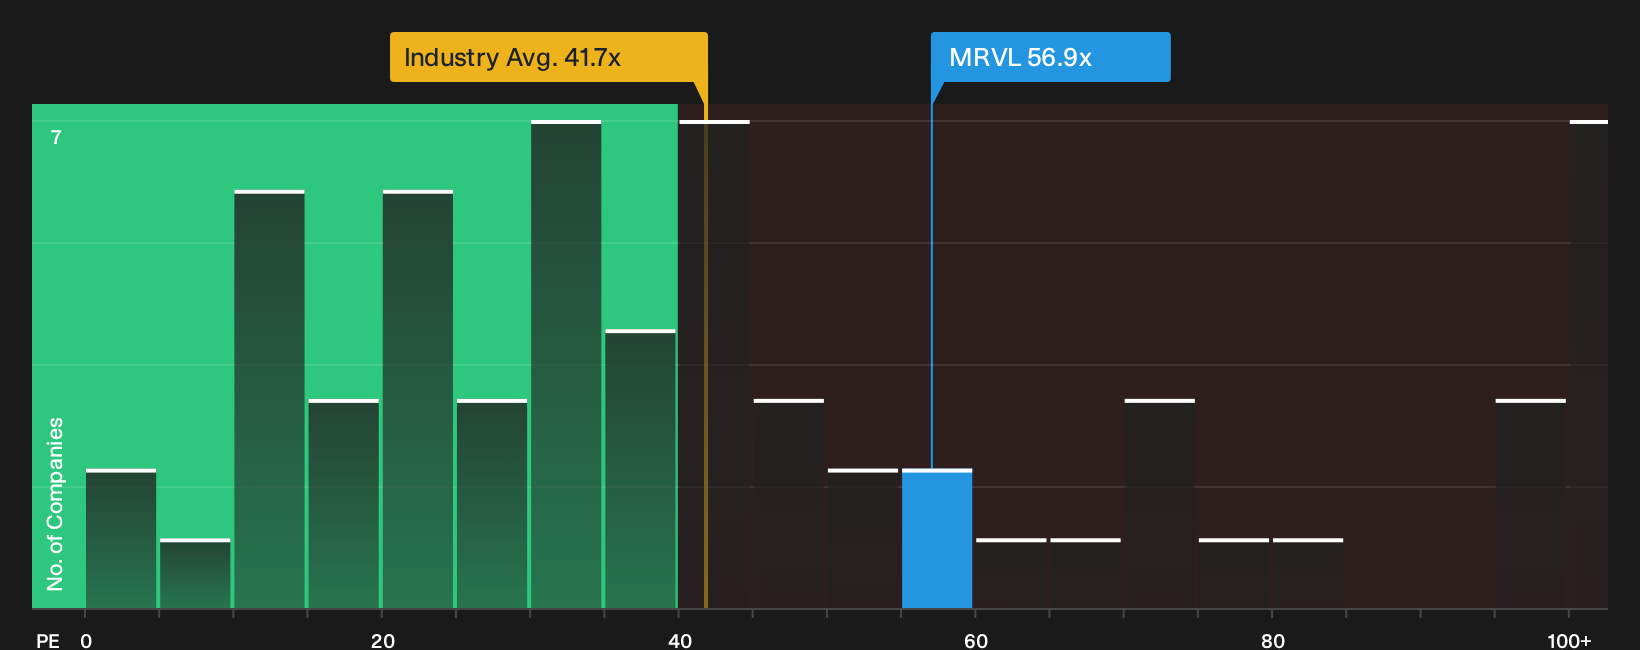
The P/E ratio is a useful lens for Marvell Technology because earnings remain the main anchor for how investors value its role in AI infrastructure. On this metric, the stock trades on about 56.9x earnings, compared with roughly 41.7x for the broader semiconductor industry and a peer average near 43.5x. That puts Marvell on a clear premium to sector and direct rivals, which indicates that buyers are willing to pay more for each dollar of profit than they pay elsewhere in the group.
The Fair Ratio model, which adjusts for factors like margins, scale and risk, points to a level slightly below the current P/E. As a result, the market price appears broadly in line with those fundamentals rather than obviously stretched or cheap. Because the planned all stock Lumentum deal has pulled the share price down while also raising questions about future earnings per share, this valuation now reflects both enthusiasm for Marvell’s AI exposure and a growing debate about how much dilution and integration risk investors should accept at this premium. Explore the numbers behind Marvell Technology's P/E valuation.
The Marvell Technology Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Marvell Technology's valuation puzzle leaves off by spelling out the specific future paths for growth, margins and earnings that would need to hold for the stock to be worth meaningfully more or less than it is today on the Community page. Instead of a single output from a ratio or model, these scenarios lay out the conditions behind that figure so you can watch how real world progress lines up with what the price assumes.
Community views on Marvell Technology split between those who think AI connectivity and custom chips still leave meaningful upside and those who see the story already well reflected in the price.
Bull case: 49% undervalued
"The expanded commercial agreement with a major hyperscaler, which includes a warrant tied to up to US$120b of cumulative revenue over 6.5 years for TPU attached custom silicon…"
Discover why this Narrative puts Marvell Technology at 49% undervalued.
Bear case: 22% overvalued
"At ~$134, the stock is priced for FY2028 execution. The investment thesis requires believing Marvell can deliver ~$15B in FY2028 revenue (+40% YoY)…"
Explore why this Narrative puts Marvell Technology at 22% overvalued.
One more Marvell Technology check before you call it done
Price ratios and deal headlines tell part of the story, but the analyst playbook for where Marvell Technology could be a few years from now offers a different lens to compare with today’s pricing. Explore where analysts expect Marvell Technology to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com