
Reddit Is Fighting Back Against AI. What That Means for RDDT Stock.
Some companies across the internet are beginning to push back against artificial intelligence (AI), and for good reason. AI tools can scrape their content, summarize it, and deliver answers without necessarily sending users to the original websites. Great for someone looking for a quick answer, but not so great for businesses that depend on website traffic, advertising, and user engagement. Apparently, getting your content used without getting the visitors is not everyone’s idea of a fair deal.
Now, Reddit (RDDT) is joining that fight. The company’s Q3 results were impressive, but beneath those numbers was a growing concern about how people discover Reddit. According to its shareholder letter, search referral traffic declined meaningfully during Q3, with the weakness accelerating toward the end of the quarter. Things got worse in October, when Reddit recorded more than one million fewer search referrals per week on average.
CEO Steve Huffman believes Alphabet's (GOOG) (GOOGL) Google AI Overviews and AI Mode are partly responsible. As Google increasingly provides AI-generated answers directly on its search pages, users have less reason to click through to websites like Reddit. Huffman argued on the earnings call that Google’s AI Mode is not driving traffic, either to Reddit or other websites.
Investors were hardly amused. Reddit shares plunged 29% on Friday after CEO Huffman warned that daily active unique visitors could decline by a low double-digit percentage in Q4 from approximately 130 million if referral traffic continues weakening.
Reddit is fighting back by testing a primarily signed-in experience in select markets outside the U.S. in Q4, requiring users to log in to access most content. The move aims to curb unauthorized data scraping, protect its user-generated content, improve ad targeting, and drive deeper engagement. If implemented broadly, it would end nearly two decades of free, account-free browsing. The CEO noted that logged-in users already account for over 80% of monetization.
Reddit already licenses its data to OpenAI and Google but has also sued Anthropic, Perplexity AI, and three data-scraping companies over alleged unauthorized collection of its content.
But will restricting access to Reddit protect its business from AI, or could the login requirement end up driving away the very users it is trying to retain?
About Reddit Stock
Known for being a go-to place for online discussions, San Francisco, California-based Reddit brings together people from all walks of life to share opinions, exchange ideas, and talk about almost anything under the sun. From sports, gaming, and movies to news, technology, and everyday interests, the platform has communities called subreddits, each built around a particular topic. Users can share posts, links, pictures, and videos, while others can upvote or downvote content, influencing what gets noticed first. Each community also has moderators who keep discussions organized and ensure members follow its rules.
Behind the platform, Reddit’s employees manage its technology, safety policies, and overall operations. The company makes money primarily through advertising and data licensing, including commercial agreements that allow AI companies to access its content. It has a market capitalization of approximately $17.7 billion.
Reddit’s stock performance has been anything but a friendly discussion lately. Investors who once cheered its rapid growth are now questioning how much of that growth can survive Google’s AI-powered search results. And the market has not exactly been patient.
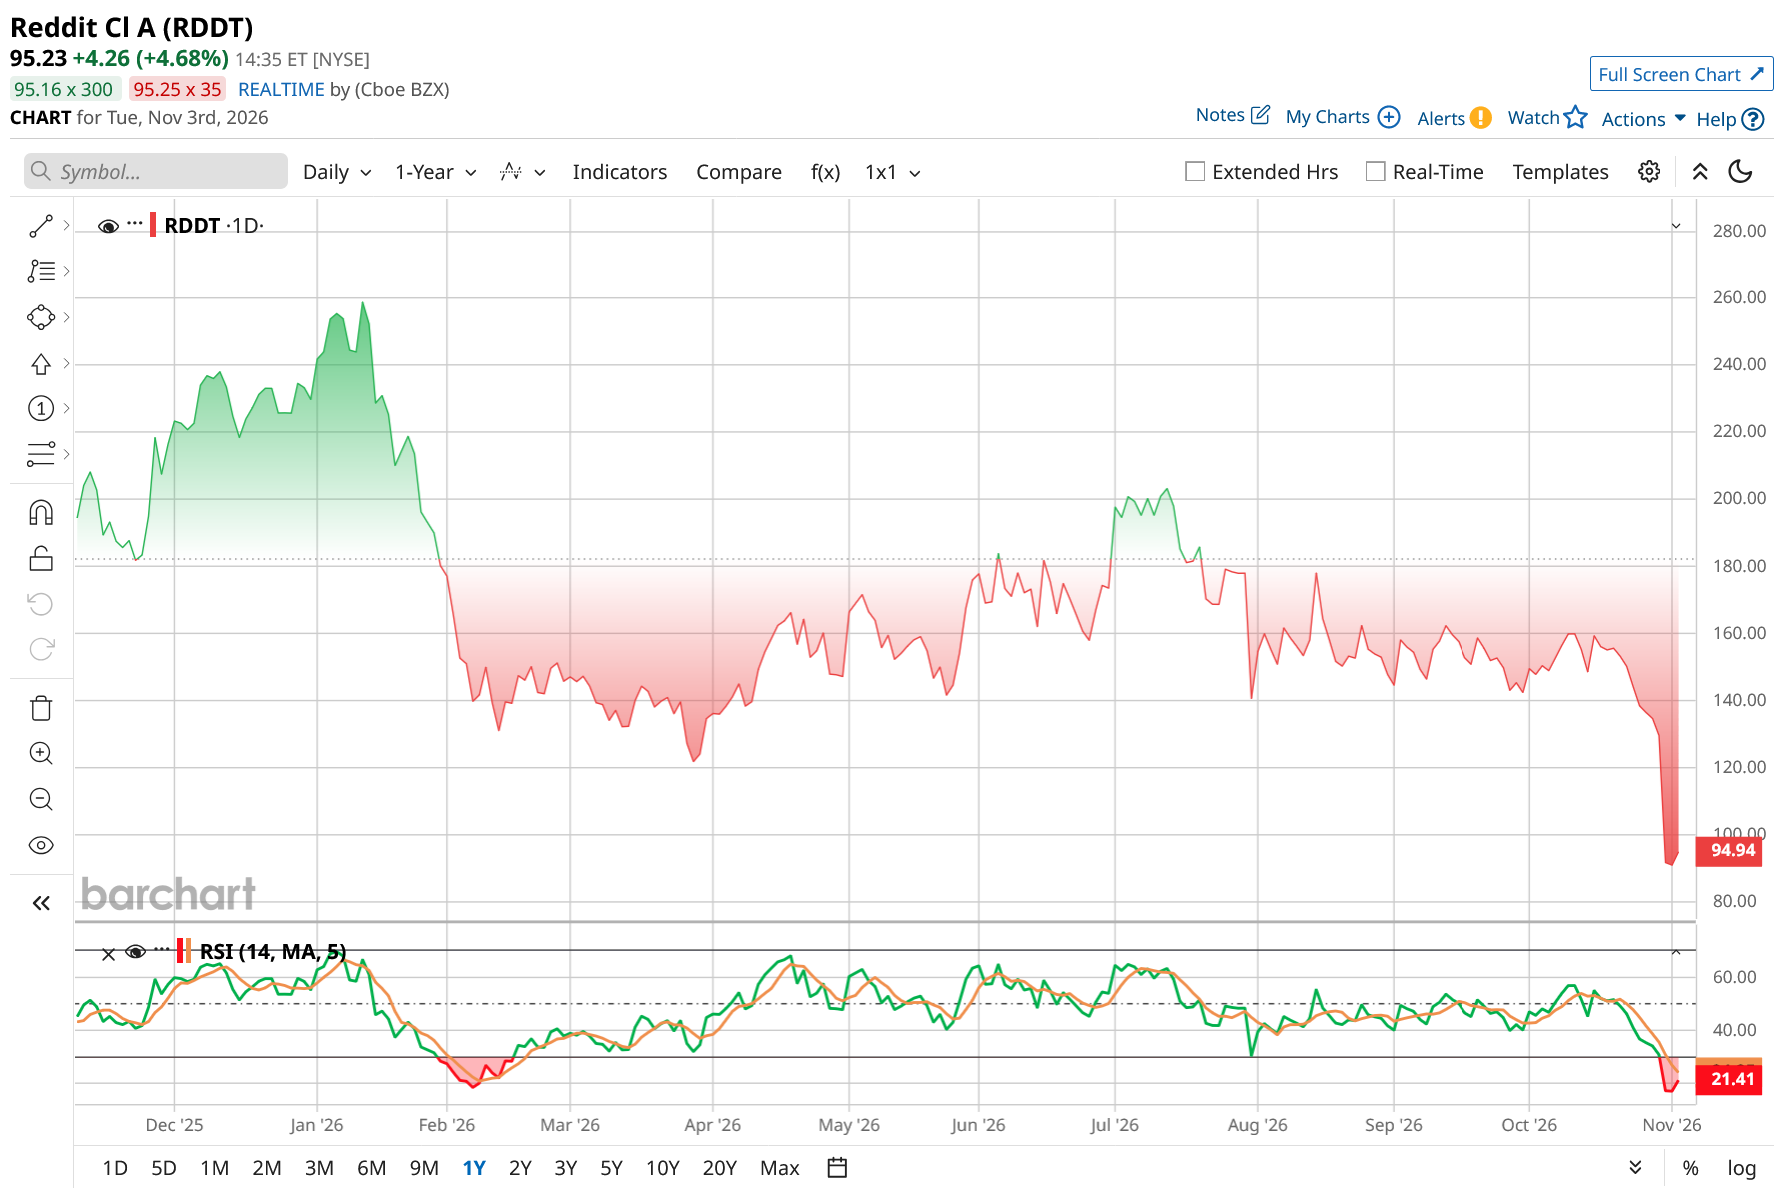
For the second consecutive quarter, shares of the online community and discussion platform took a beating immediately after earnings, falling 21% following its Q2 report before suffering an even nastier 29.2% plunge after reporting its Q3 results, marking its worst single-day performance since going public in 2024.
This was triggered by weakening search referrals and a softer-than-expected Q4 revenue outlook. Consequently, RDDT has shed 54% over the past 52 weeks and 59% on a year-to-date (YTD) basis, touching a 52-week low of $89.28 on Oct. 30. Apparently, impressive earnings are not enough when investors start questioning what comes next.
RDDT’s technicals look battered, with heavy red trading-volume bars pointing to intensified selling pressure. Meanwhile, its 14-day RSI has plunged to 21.41, deep into oversold territory (below 30), suggesting aggressive selling may have pushed the stock well below its recent momentum range.
Despite the recent selloff, Reddit’s valuation has not exactly entered bargain territory. RDDT still trades at 5.23x forward sales, comfortably above the sector average, indicating that investors are continuing to price in strong future revenue growth.
However, the picture looks slightly different on the earnings front. Its forward non-GAAP price-to-earnings (P/E) ratio stands at 11.87x, below both sector peers and its historical median. Apparently, Wall Street is willing to pay up for Reddit’s growth story, but the recent traffic concerns have made that premium a little harder to justify.
A Snapshot of Reddit’s Q3 Earnings Report
Reddit’s third-quarter 2026 earnings report, released on Oct. 29, gave investors plenty of reasons to smile, at least initially. The company reported EPS of $1.40, up 75% year-over-year (YoY) and comfortably ahead of estimates. Revenue jumped 53% annually to $895 million, beating Wall Street’s expectations. Strong advertising demand, higher pricing, and better monetization did much of the heavy lifting.
Advertising remains Reddit's biggest money-maker, and the numbers make that pretty clear. Ad revenue climbed 54% to $847 million, supported by higher ad impressions and improved pricing. U.S. revenue increased 50% to $718.9 million, while international revenue grew an even faster 67% to $176.1 million. So, Reddit is not relying entirely on its home market to keep the cash registers ringing.
User growth, however, tells a slightly more complicated story. Global daily active uniques (DAUq) averaged 130.3 million, up 12%, while weekly active uniques (WAUq) increased 16% to 515.2 million. International markets drove much of the growth, with daily active users rising 24% to 79.6 million and weekly users jumping 28% to 326.7 million. Meanwhile, U.S. daily active users slipped 2% annually to 50.7 million, and weekly users remained nearly flat at 188.5 million. In other words, overseas growth is doing some serious work here.
Reddit also made more money from each visitor. Global average revenue per unique user (ARPU) rose 36% to $6.87. U.S. ARPU jumped 53% to $13.82, while international ARPU increased 32% to $2.43.
Its advertising business showed strength across the board. Click volume grew more than 50%, while conversion volume more than tripled YoY. Shopping and app-install ad revenue each surged over 95%. Scaled revenue climbed more than 80%, and mid-market active advertisers increased over 50%, with demand across North America and Europe. Reddit Max adoption more than tripled sequentially as automation improved.
Profitability was equally encouraging. Adjusted EBITDA rose 70% to $402.3 million, with margins expanding 460 basis points to 44.9%.
Reddit ended September with $3.03 billion in cash, equivalents, and marketable securities. Operating cash flow almost doubled, rising 96% to $363.8 million, while free cash flow climbed 98% to $362.6 million, representing a 40.5% margin. The company also repurchased 670,000 shares for $100 million, leaving roughly $660 million under its existing buyback authorization.
Looking ahead, Reddit expects another strong revenue quarter, although the traffic situation could make things a little less celebratory. For Q4 2026, management forecasts revenue of $1 billion to $1.03 billion, translating to roughly 40% YoY growth at the midpoint. Adjusted EBITDA is expected to land between $480 million and $510 million, implying a healthy 49% margin at the midpoint. Not bad for a company dealing with an AI-driven traffic headache.
However, there is a catch. Management warned that continued weakness in search referrals could push daily active users down by a low-double-digit percentage sequentially. To address this, Reddit plans to test a primarily logged-in experience in select international markets during Q4. Whether users will happily log in or simply click away remains the bigger question.
Analysts are extremely optimistic about Reddit’s earnings growth trajectory, estimating EPS growth of 41.9% YoY to $1.76 in Q4, while revenue is expected to be $1.03 billion. For fiscal 2026, EPS is expected to surge by 101.5% to $5.28, followed by an increase of 31.6% to $6.95 in fiscal 2027.
What Do Analysts Expect for RDDT Stock?
Wall Street is clearly having a divided conversation about Reddit, and the latest analyst revisions show just how much uncertainty surrounds its growth story. Needham slashed its price target to $150 from $300 but maintained a “Buy” rating. The brokerage firm acknowledged the search traffic problem but believes Reddit’s move toward a login-based experience could reduce churn, improve ad targeting, and protect its valuable data from AI companies. It also sees an opportunity for Reddit to monetize a more controlled platform better than an open internet business.
Guggenheim was also less generous with its valuation, cutting its price target to $170 from $255 while retaining a “Buy” rating. Its concerns largely revolve around declining search referrals, accelerating traffic pressure, and the risks associated with restricting access to content.
Cantor Fitzgerald, meanwhile, is not quite ready to join the optimists. The brokerage firm lowered its target to $120 from $170 and maintained a “Neutral” rating. It called the quarterly performance mixed, pointing to user growth shortfalls, softer-than-expected guidance, and questions about how much monetization growth Reddit can sustain.
With RDDT stock already under pressure, analysts seem to agree that Reddit has a business worth watching, but its next growth chapter comes with plenty of unanswered questions.
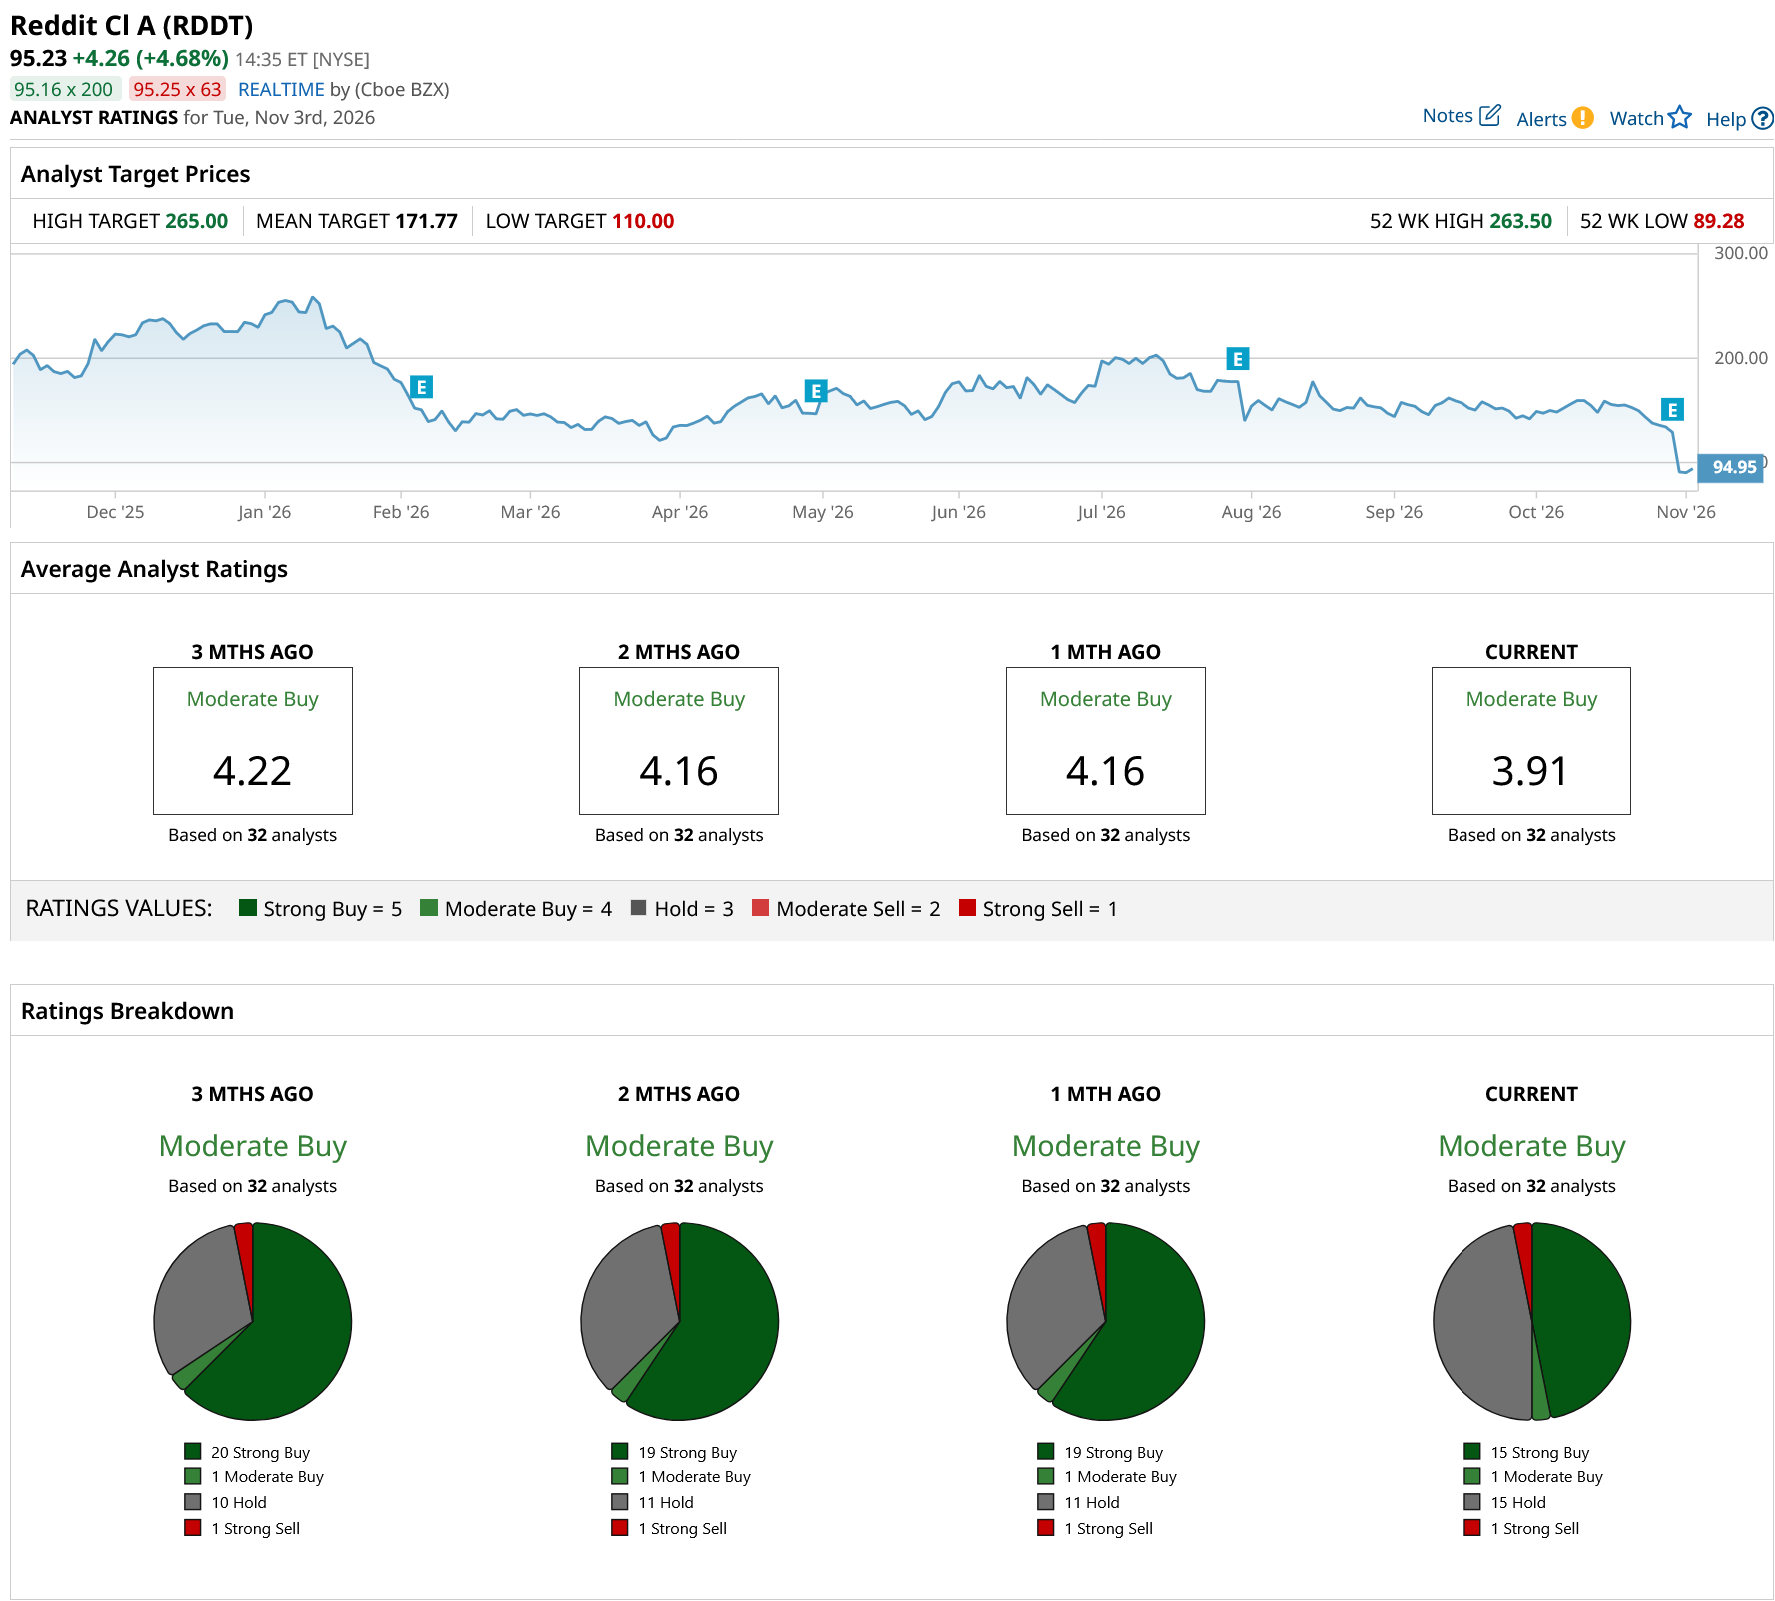
Wall Street has not given up on Reddit just yet, but the optimism comes with a few raised eyebrows, earning RDDT a consensus “Moderate Buy” rating. Of the 32 analysts rating the stock, 15 have rated it a “Strong Buy,” one suggests a “Moderate Buy,” 15 analysts are playing it safe with a “Hold” rating, and the remaining one analyst recommended a “Strong Sell” rating.
The consensus price target of $171.77 represents a rebound potential of 80%, while the Street-high price target of $300 reflects that RDDT stock could rise as much as 215% from current price levels.
Final Thoughts on RDDT Stock
Reddit’s 2026 journey has been volatile, with strong advertising growth, improving monetization, and impressive earnings initially winning investors over. But concerns about weakening traffic and future growth have changed the mood. Despite healthy profitability and cash generation, Wall Street is increasingly questioning its long-term growth story.
The bigger challenge lies in Reddit’s attempt to protect its content without alienating the very people who make the platform valuable. For years, users have treated Reddit as an open library of real-world opinions, casually following discussions without needing an account. A mandatory login could disrupt that habit, particularly among casual visitors who may not find another sign-up process worth the trouble.
A login wall could limit Google’s ability to crawl and index restricted pages, weakening search visibility and organic discovery. Reddit must keep AI scrapers out without making genuine readers feel unwelcome and frustrated. After all, protecting the library means little if readers stop walking through its doors.
On the date of publication, Sristi Suman Jayaswal did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.