
Missed EZCORP's Run? What Holders Had To Believe
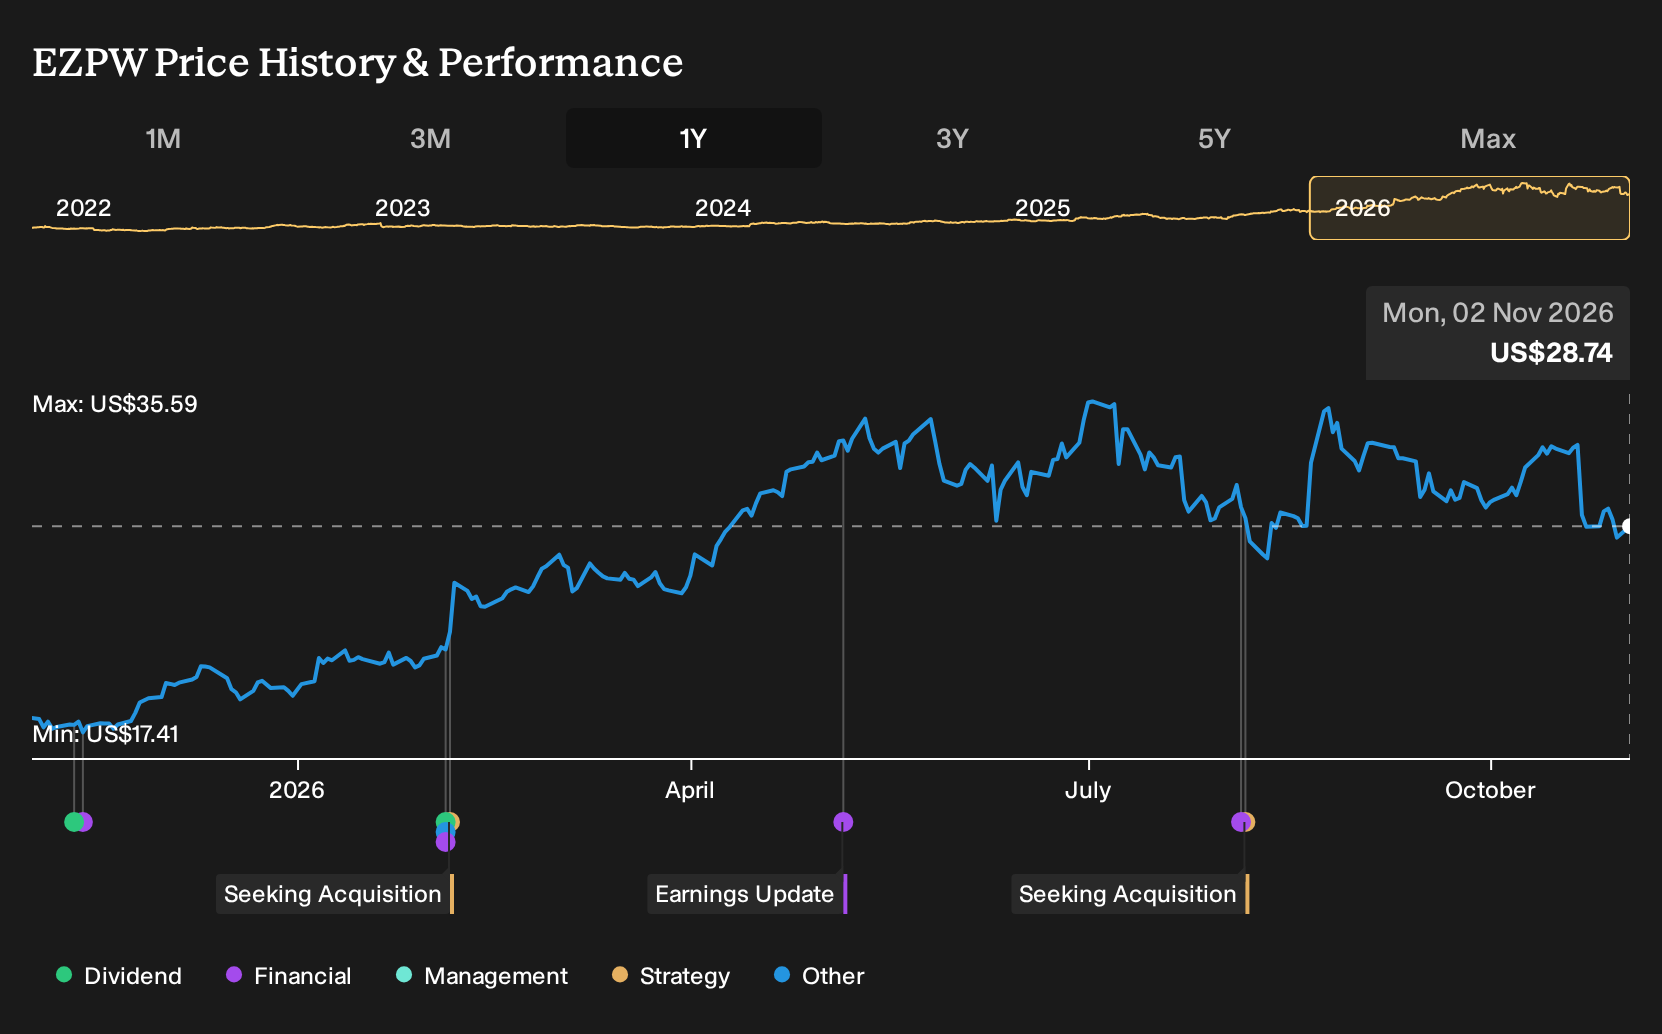
Start with one concrete move. EZCORP just launched a fresh US$50m share repurchase program alongside record quarterly earnings, a combination that tends to focus attention on what existing holders actually walked away with. For EZCORP shareholders, the return over the past year was 58.4%, including dividends. If you were deciding back on 2025-11-02, what did you need to believe about underbanked demand, Latin America expansion, and digital tools like Instant Quote to be comfortable buying in before this run?
The easy part of this move is behind EZCORP. Zero in on 34 high quality undervalued stocks for companies trading below our estimates.
The Two EZCORP Stories Investors Were Arguing About
The shares cost US$18.26 at the start of the period, and EZCORP sat between two clear storylines that both sounded plausible.
On the optimistic side, the bullish narrative pointed to a fair value of US$25, a price level implied by confidence in aggressive Latin America expansion and faster adoption of tools like Instant Quote to lift margins and earnings stability.
The bearish view anchored on a fair value of US$17 and focused on regulatory tightening and rising financial inclusion gradually squeezing pawn lending returns, even as EZCORP invested heavily in digital projects.
What The Results Changed For The EZCORP Debate
The clearest development for EZCORP was the Q3 2026 report, with revenue of US$418.748m and net income of US$38.199m, both above Q3 2025 levels, and net margin rising from 8.5% to 9.1%. That tilt in profitability supported the optimistic case that scale and expansion could improve earnings quality. Higher costs and valuation worries in later coverage gave the cautious camp fresh concerns, so the evidence cut both ways.
The lesson is simple. When a thesis leans on margin expansion and growth, track net income and net margin side by side, quarter by quarter, to see whether the story in management’s playbook is actually showing up in the numbers you can verify.
What EZCORP’s 58% Run Now Asks You To Believe
EZCORP trades at US$28.74, and the selected Narrative sees Fair Value above that level based on core pawn profitability rather than scrap gold swings or one off factors.
This view argues the price still does not fully credit sustained pawn earnings from U.S. and Latin America stores supported by a cash rich balance sheet.
"Continued focus on core pawn profitability, with most recent EBITDA and gross profit growth coming from pawn operations rather than scrap gold, positions future earnings and net margins to depend more on recurring loan demand and merchandise sales than on gold price movements."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Where EZCORP’s Story Connects
EZCORP focuses on customers who sit between traditional banking access and urgent cash needs. That gap is no longer served only by pawn loans.
Another financial platform is trying to keep similar customers from needing short term fixes at all. It folds checking, saving, borrowing and investing into a single digital hub.
One login supports several tools instead of scattered apps and accounts. That setup can lower marketing costs whenever a user adds another product.
The same business also rents its core banking software to other providers. That mix of direct access and embedded technology leaves an open question about where underbanked demand might go next.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 38% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com