
Ally Financial (ALLY) Awards Spotlight Puts Valuation Back In Focus
Ally Financial: What the latest earnings and buyback activity signal
Ally Financial (ALLY) has investors’ attention after a busy stretch of news. Third quarter 2026 results landed, a fresh tranche of buybacks wrapped up, and a string of national awards highlighted the brand’s reputation.
Over the past year, Ally Financial shares have moved around a fair bit, with a 90 day share price return that declined 14.18% even as the 1 year total shareholder return was slightly positive at 1.03%. This hints that recent momentum has faded, while longer term holders have seen more resilience.
The latest 1 day share price gain of 1.15% and the completion of a US$484.71m buyback program arrived alongside third quarter earnings news and national awards for trust and customer value. Together, these developments indicate that investors may be reassessing both growth potential and perceived risk around the stock.
Compare Ally Financial’s mix of earnings progress, buybacks, and reputation with a curated list of 29 resilient stocks with low risk scores that could offer a different balance of resilience and upside potential.
Bulls point to Ally Financial’s earnings progress, buybacks and industry recognition. Bears focus on the choppy share performance. Which side do the current numbers lean toward as you weigh valuation next?
Most Popular Narrative: 19% Undervalued
Ally Financial closed at $38.61, while the most followed narrative anchors fair value closer to $47.45. That gap frames the current debate around whether recent earnings strength and capital returns are fully reflected in the price.
The accelerating demand for digital banking and app-based financial services is enabling Ally Financial's all-digital business model to acquire and retain customers more efficiently. This supports ongoing net customer growth and drives higher deposit stability, which can support long-term revenue and net margin expansion as the cost advantages of digital scale deepen.
See why 43 investors see Ally Financial as 19% undervalued.
Result: Fair Value of $47.45 (UNDERVALUED)
Still, higher retail auto charge offs and the Stellantis recall related lease losses risk putting fresh pressure on Ally Financial’s credit costs and net interest margin story.
Find out about the key risks to this Ally Financial narrative.
Another View: How Ally Financial Screens On P/E
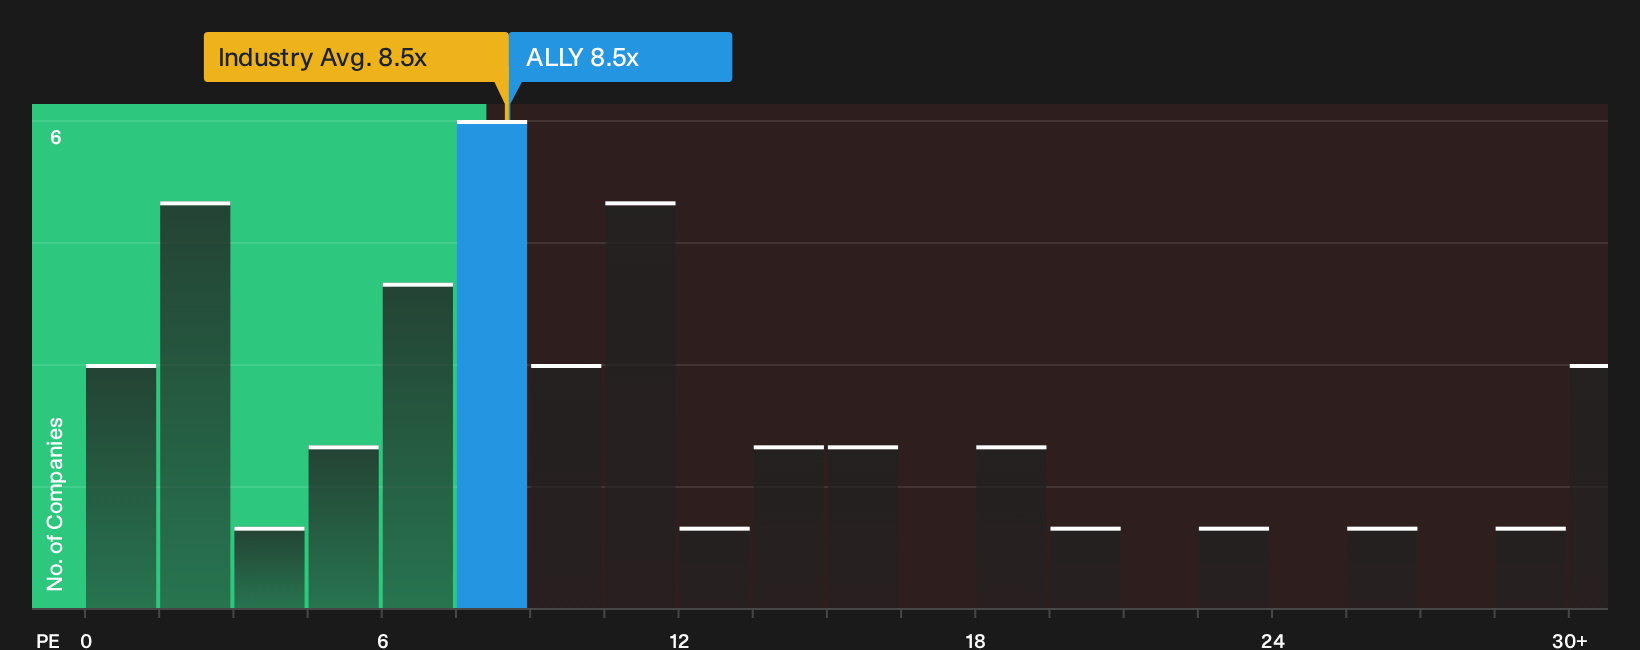
The earlier fair value of $47.45 leans on future earnings forecasts and discount rates. A simpler lens uses today’s P/E of 8.5x. That level matches the US Consumer Finance industry at 8.5x, yet it sits well below the 15.5x peer average and the 13.6x fair ratio the market could move toward. For investors, that mix can look like either a valuation cushion or a sign that expectations remain muted. Which reading matches your own view of Ally Financial’s risk and reward?
To test how much weight to put on this kind of comparison, it helps to look directly at the detailed valuation work behind it, then judge whether the assumptions feel realistic for Ally Financial’s cycle and credit profile today. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Optimistic about Ally Financial or still cautious after the recent swings? Act quickly, review the full reward profile, and decide where you stand with 5 key rewards.
Looking for more investment ideas beyond Ally Financial?
If Ally Financial is on your radar, you may want to widen your opportunity set with other targeted ideas that match different goals for return potential, resilience, and income.
- Target potential mispricing by scanning a curated pool of companies that pair quality fundamentals with appealing valuations through 34 high quality undervalued stocks.
- Strengthen portfolio durability by focusing on businesses with robust finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for future leaders early by reviewing a focused shortlist of under-the-radar opportunities via 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com