
CrowdStrike Stock Is Climbing, but 1 Risk Could Derail the Rally
CrowdStrike (CRWD) shares have delivered an impressive performance, gaining more than 112% year-to-date (YTD). The rally reflects growing investor optimism about the company's ability to capitalize on rising cybersecurity spending as artificial intelligence (AI) adoption accelerates.
The rapid expansion of AI models, autonomous agents, and AI-powered applications is creating a broader and more complex cybersecurity threat landscape. As organizations deploy more AI-driven systems, the number of data assets, digital identities, access permissions, and interconnected endpoints that require protection continues to grow. This is making cybersecurity an increasingly critical layer of the AI infrastructure ecosystem, creating a sustained demand opportunity for security providers.
CrowdStrike is strategically positioned to benefit from this structural shift. Its cloud-native cybersecurity platform, combined with growing demand for AI-related security solutions, provides an opportunity to capture a larger share of enterprise security budgets. Furthermore, the accelerating trend toward platform consolidation strengthens its competitive position, supports customer retention, and creates additional cross-selling opportunities.
However, despite its favorable growth outlook and exposure to long-term AI-driven cybersecurity demand, CrowdStrike's valuation remains a significant risk.
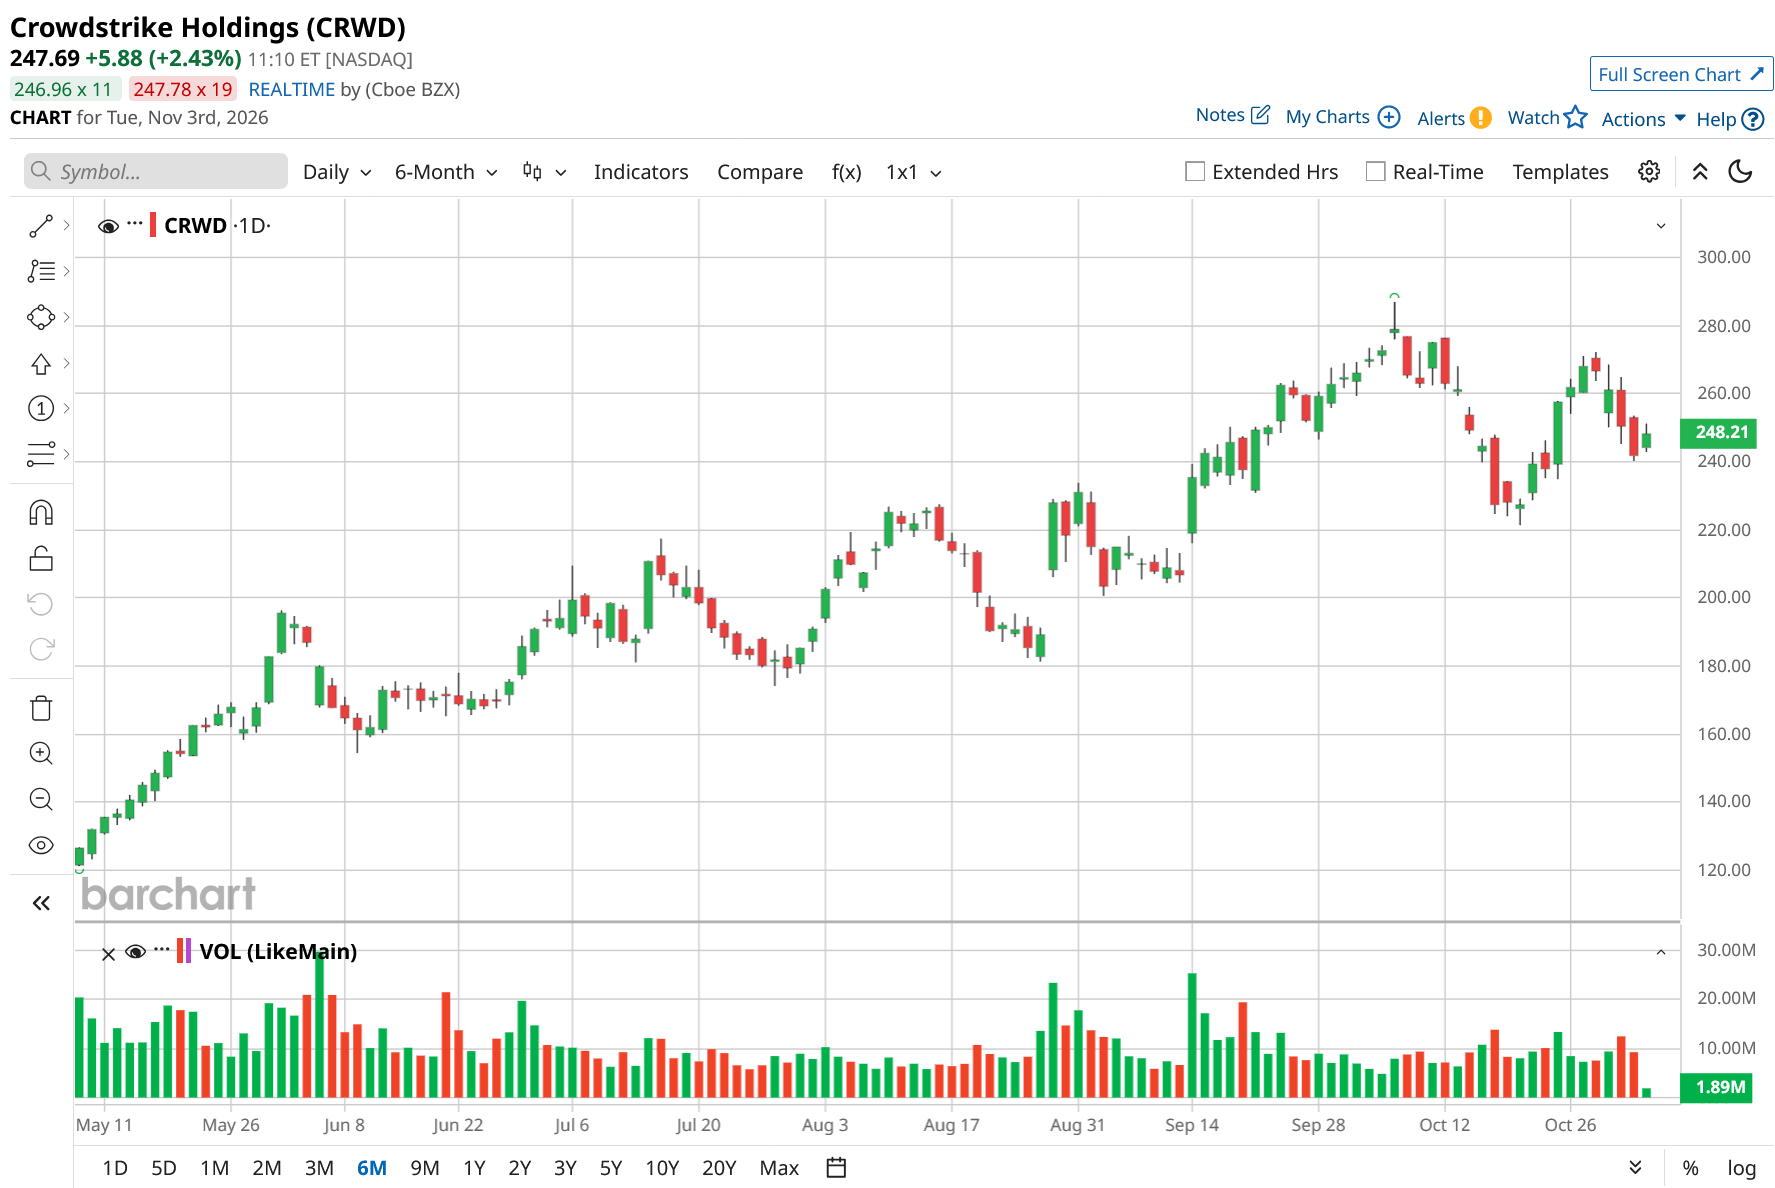
Outlook Is Solid Amid Rising Cybersecurity Demand
CrowdStrike delivered a strong second-quarter performance, reflecting increasing platform adoption and its ability to capitalize on the growing demand for cybersecurity solutions. CRWD’s growth trajectory continues to strengthen, supported by rising cyber threats, accelerating AI adoption, and increasing enterprise demand for integrated security platforms.
Revenue increased 26% year-over-year (YoY) to $1.47 billion, marking the fifth consecutive quarter of sequential revenue acceleration. Subscription revenue rose 27% to approximately $1.40 billion, while professional services revenue reached a record $71 million.
CrowdStrike’s net new annual recurring revenue (ARR) reached an all-time high of $333 million, up 51% YoY. Ending ARR increased to $5.84 billion, up more than 25% YoY, marking the fourth consecutive quarter of accelerating growth.
Platform consolidation remains another important driver of growth. 51% of subscription customers adopted seven or more modules, while 35% and 26% adopted eight or more modules, respectively.
Falcon Flex has emerged as an significant contributor to this trend, allowing customers to consolidate their cybersecurity requirements within a unified platform. ARR from customers adopting the Falcon Flex subscription model surpassed $2.29 billion, increasing 101% YoY. This rapid growth supports more in-depth customer relationships, higher retention rates, and greater revenue opportunities over time.
Looking ahead, a robust Q3 pipeline, broad-based demand across customer segments, and continued traction of the Falcon platform indicate an increasingly favorable demand environment.
Reflecting this improved demand, management has further upgraded its FY2027 net new ARR guidance to $1.35 billion at the midpoint, up $116 million over the initial full-year outlook. The revised guidance implies YoY net new ARR growth of about 34%, up from the initially projected 22.5%.
Overall, rising demand for integrated security solutions, strong Falcon Flex adoption, and an improved ARR outlook position CrowdStrike for sustained growth.
CRWD Stock’s Valuation: A Key Risk
Although CrowdStrike continues to witness strong demand, its valuation raises concerns. Following a sharp rally, CRWD stock appears to reflect considerable optimism regarding its long-term growth trajectory.
This premium is evident in its valuation multiple. CrowdStrike currently trades at a price-to-sales (P/S) ratio of 55.6, significantly above Palo Alto Networks’ (PANW) multiple of 27.1, highlighting the substantial valuation premium relative to its industry peer.
From a long-term perspective, CrowdStrike’s growth outlook remains compelling. Increasing enterprise adoption of AI is likely to drive demand for advanced security solutions. Furthermore, CrowdStrike's integrated platform strategy provides opportunities to deepen customer relationships, cross-sell additional products, and drive higher revenue per customer. However, the stock's elevated valuation suggests the market has already priced in these positives.
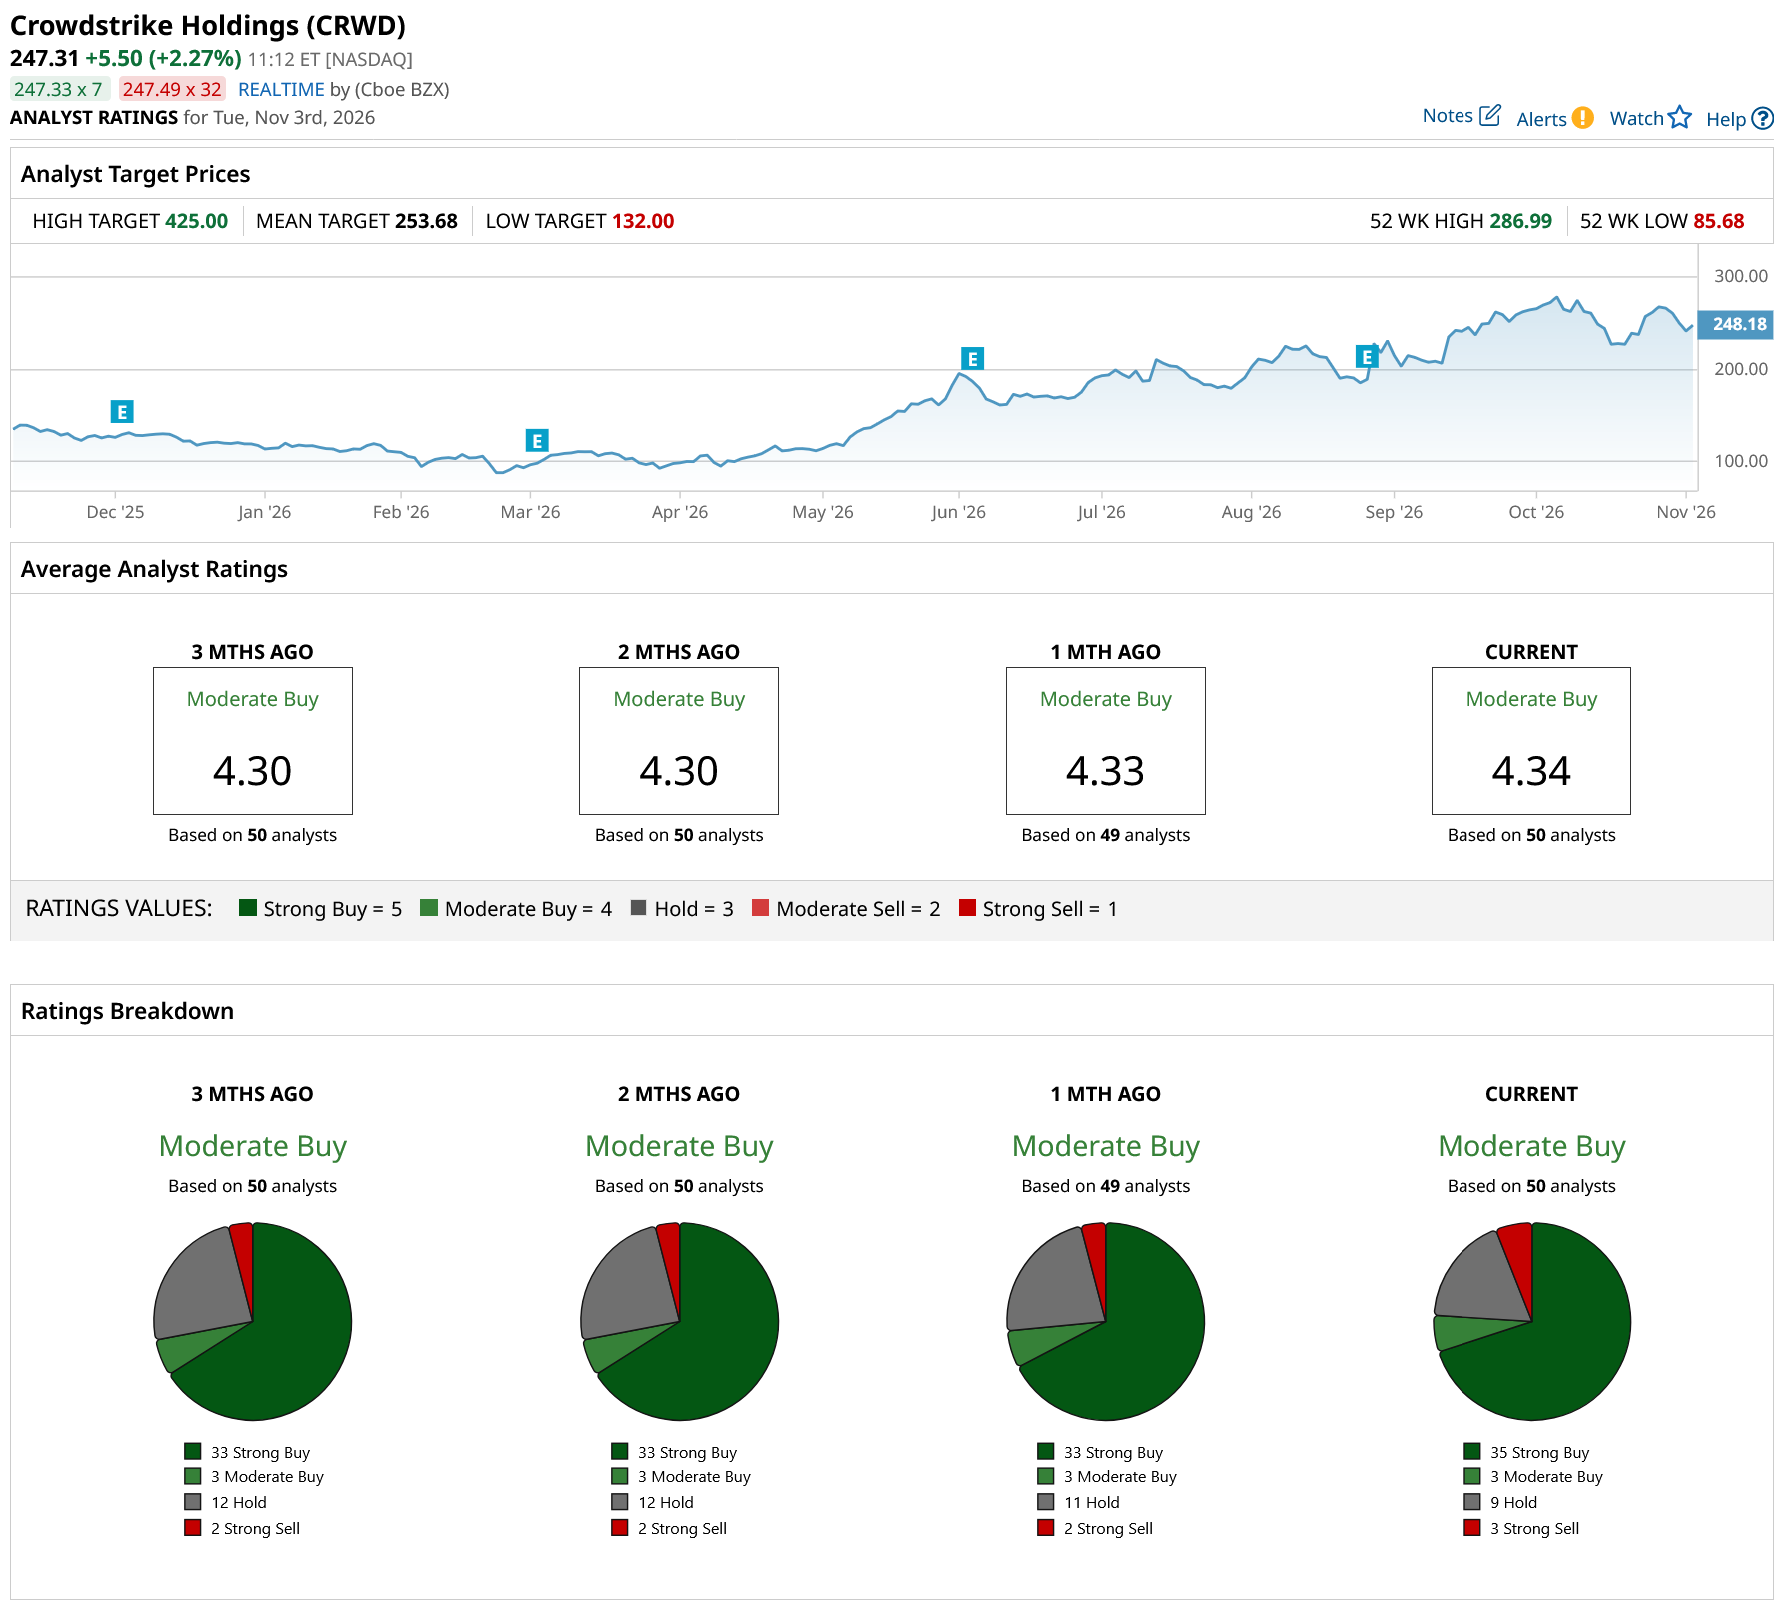
Given CRWD’s high valuation, Wall Street maintains a “Moderate Buy” consensus rating.
CrowdStrike's Growth Story Remains Intact, but Valuation Warrants Caution
CrowdStrike's strong revenue growth, accelerating ARR, and rising adoption of its Falcon platform strengthen its long-term growth prospects amid increasing AI-driven cybersecurity demand. However, its elevated valuation remains a key concern, especially as the stock trades at a substantial premium to industry peers.
With much of its growth potential seemingly priced in, investors should remain cautious about entering CRWD stock at current valuation levels.
On the date of publication, Amit Singh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.