
Is Oklo (OKLO) Undervalued Given Its Book Value And Pipeline?
Oklo has gone through a dramatic reset, with the share price down sharply over the past year. That puts fresh focus on whether the current market value still lines up with the company’s underlying book value. For investors watching a young nuclear developer with big ambitions, the core issue is how much of its balance sheet strength and project pipeline is already reflected in today’s price.
- Over the past 5 years the stock has delivered a total return of about 138%. That raises the question of how much balance sheet support remains at the current valuation.
- Recent coverage has highlighted Oklo’s customer agreements for advanced nuclear power projects, which can shape expectations for future asset build out, funding needs and ultimately the relationship between its share price and book value.
- There is a second opinion on Oklo worth weighing. See what analysts think Oklo's shares could be worth.
The issue now is whether Oklo’s current share price is adequately supported by the book value sitting on its balance sheet.
If you are weighing Oklo against other nuclear themed opportunities, it can help to see how a broader set of power grid related plays are valued through 43 power grid technology and infrastructure stocks.
Is Oklo Still Cheap on Book Value?
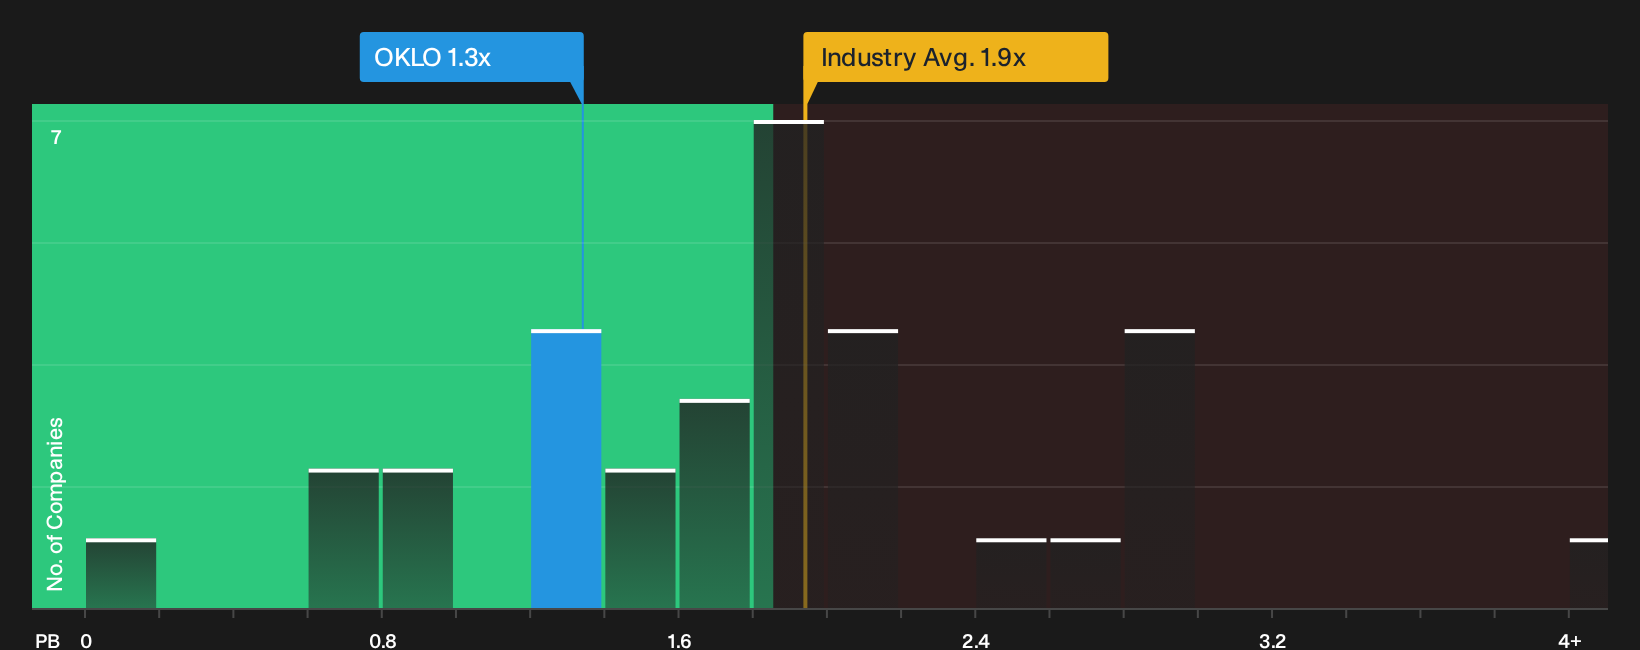
P/B is a useful lens for Oklo because the business is still loss making and investors are weighing the balance sheet against a long development runway. On this yardstick, Oklo trades on a P/B of about 1.3x, which is lower than the Electric Utilities industry average of roughly 1.9x and below the peer group on about 1.8x.
Because the recent news flow highlights a sizeable customer pipeline and regulatory progress, the current discount on P/B suggests the market is not fully pricing those ambitions into Oklo’s equity base. For you as a shareholder or potential buyer, the key question is whether the existing book value and funded project work justify a P/B that is closer to the industry pack, or whether balance sheet risks mean this lower multiple is appropriate for now. Explore the numbers behind Oklo's P/B valuation.
The Oklo Narrative: What Would Justify Today's Price?
Narratives pick up where Oklo's price to book puzzle leaves off. They spell out which paths for Oklo's growth, profitability and earnings would need to play out for the shares to be worth materially more or less than today, and each one links its number to a clear view on how growth, margins and key risks might evolve. This gives you something concrete to return to as new information comes through.
Oklo splits opinion, with some investors viewing it as a potential long runway power producer and others focusing on execution risk and rich expectations.
Bull case: 71% undervalued
"Oklo has already signed major agreements, e.g. with Switch for 12 GW through to 2044…"
Discover why this Narrative puts Oklo at 71% undervalued.
Bear case: 68% overvalued
"Oklo is building three interconnected business units (power, fuel and isotopes) at the same time…"
Explore why this Narrative puts Oklo at 68% overvalued.
One last Oklo check that belongs beside the book value story
Headline ratios only tell part of the Oklo picture, and the internal risk checks sitting behind them can point in a very different direction for your comfort level. Take a closer look at 6 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com