
Texas Instruments (TXN), Why Is It Drawing Fresh Attention Now?
Why Texas Instruments is in focus now
Texas Instruments (TXN) has just priced US$2.0b of senior unsecured notes across four maturities, with coupons ranging from 5.000% to 5.750%, to help fund its planned acquisition of Silicon Laboratories.
The new debt sits against a share price of US$302.02, with Texas Instruments posting a 6.48% 90 day share price return and a 70.13% year to date share price return. The 1 year total shareholder return of 91.13% points to strong, building momentum around the stock.
Spot how Texas Instruments’ funding move fits into a wider pattern in chips, and then run the same filter across 53 AI infrastructure stocks for other potential beneficiaries of rising compute demand.
Texas Instruments is issuing fresh debt into a roaring share price, which raises a simple puzzle. Are investors paying up for sturdier cash flows or for sentiment that has raced ahead of the business, and how does that show up in valuation now?
Most Popular Narrative: 31% Undervalued
The narrative fair value for Texas Instruments sits at $435.69, well above the last close at $302.02. This sets a clear valuation gap for investors to interrogate.
Texas Instruments is in the midst of a multiyear capacity-expansion cycle that is temporarily suppressing free cash flow but materially enhancing the company’s long-term competitive position. The buildout of U.S.-based 300mm analog manufacturing is expected to structurally improve cost efficiency, support higher gross margins, and increase supply-chain resilience. As these assets ramp and utilization normalizes, TXN should regain its historical free-cash-flow profile, supported by diversified end-market exposure across industrial, automotive, aerospace/defense, and energy infrastructure.
See why 22 investors see Texas Instruments as 31% undervalued.
Result: Fair Value of $435.69 (UNDERVALUED)
Still, the thesis around Texas Instruments can be hit if the capacity build keeps cash flows muted for longer than expected or if AI related demand materializes more slowly.
Find out about the key risks to this Texas Instruments narrative.
Another view on Texas Instruments’ valuation
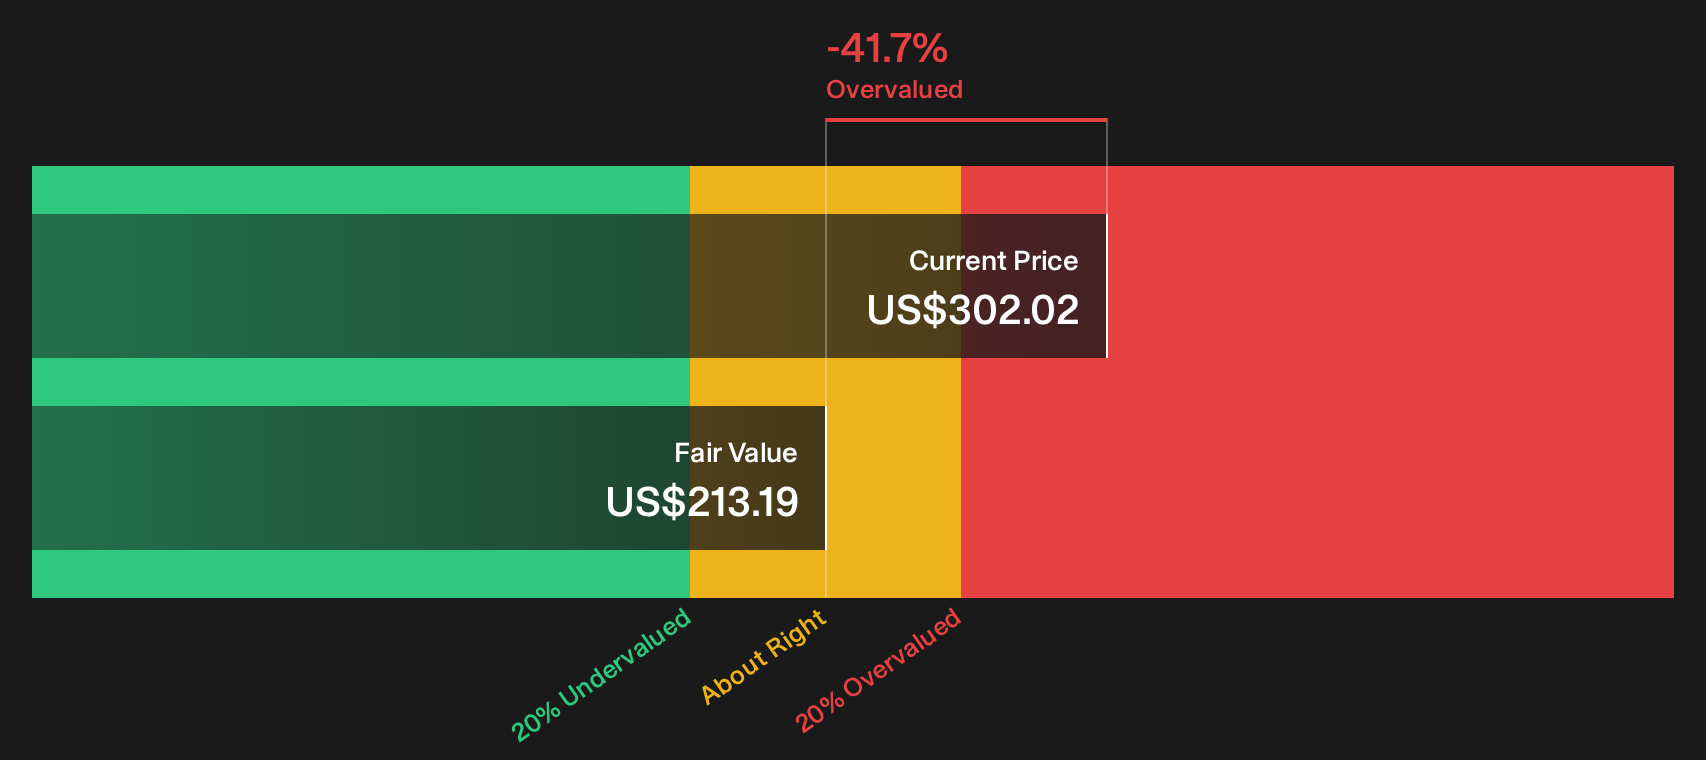
A second lens tells a different story. Our DCF model estimates Texas Instruments’ future cash flow value at $213.19 per share, well below the current $302.02 price, which screens as overvalued on this framework. Which perspective do you find more compelling: the narrative fair value or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals in Texas Instruments usually spark the most useful questions, so move quickly from reading to testing the data yourself and weighing both sides of the thesis. To see the full balance of potential upside and flagged issues, review the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Texas Instruments?
If Texas Instruments has sharpened your thinking, do not stop here. Broaden your watchlist now with data driven filters that surface fresh opportunities fast.
- Target dependable cash generators and stress test your watchlist against a list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced quality and compare Texas Instruments with a 34 high quality undervalued stocks that screens for strong fundamentals at compelling prices.
- Secure potential income streams early and size up yield focused candidates drawn from a 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com