
Will Interim CFO Appointment Change MasterBrand (MBC) Narrative
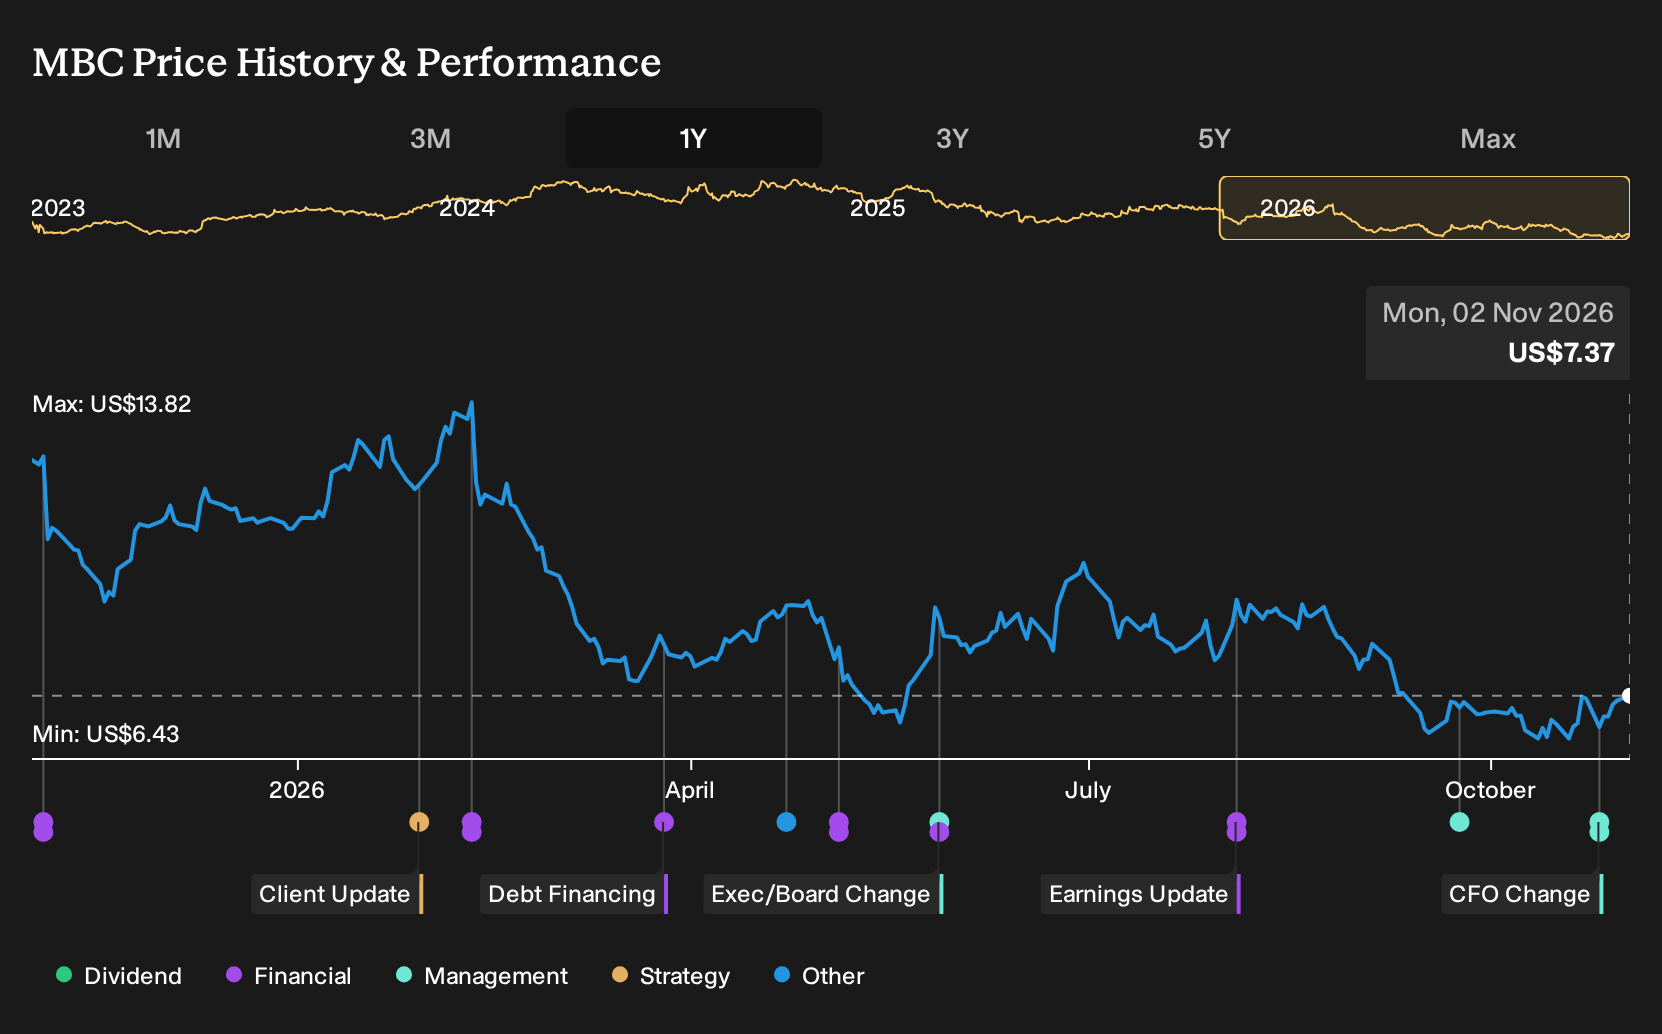
- MasterBrand announced that Chief Financial Officer Andrea Simon stepped down on October 23, 2026. Vice President and Chief Accounting Officer Mark Young is taking on the Interim CFO role while also retaining his accounting responsibilities during a transition period that runs through March 31, 2027.
- The move places MasterBrand’s long time accounting lead at the center of both external reporting and internal controls while the board conducts a broad search for a permanent finance chief. This approach helps keep operational finance continuity front and center even as the leadership structure evolves.
- We will look at how MasterBrand’s investment narrative could be influenced by concentrating CFO and chief accounting duties in Mark Young.
Scan how other manufacturers with seasoned finance leadership are positioned by reviewing the list of solid balance sheet and fundamentals (24 results), which may handle executive transitions with similar balance sheet resilience.
What Is MasterBrand's Investment Narrative?
To own MasterBrand, you have to believe the cabinet maker can turn strong top line potential into durable cash generation in a fairly capital intensive, cyclical housing market. The business sells into both remodeling and new build, so near term you are watching order trends, pricing discipline with dealers and retailers, and how well factory throughput matches demand. Revenue is forecast to grow 25.39% a year, yet the latest 1 year share performance, down 40.8%, shows investors still want clearer progress on profitability.
The CFO transition slots directly into those execution questions. Mark Young already ran financial reporting, controls, and accounting policy, and Andrea Simon staying through March 31, 2027 should limit disruption to day to day operations. The bigger near term swing factors remain interest costs, given earnings do not yet cover them well, recent shareholder dilution, and whether unprofitable economics can move closer to the value implied by a 0.5x P/S multiple and analyst targets.
Even so, there is one pressure point in the MasterBrand story that could matter far more than the CFO change itself...
There's only one way to know the right time to buy, sell or hold MasterBrand. Head to Simply Wall St's company report for the latest analysis of MasterBrand's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community only has two fair value estimates for MasterBrand, yet they sit far apart, from about US$1.48 to roughly US$9.63 per share. That spread signals sharply different expectations for earnings power. You are seeing opinions formed before the CFO transition, so reassess how new leadership may influence your own view.
Explore another MasterBrand fair value estimate, including one that suggests as much as 80% downside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your MasterBrand research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for MasterBrand. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MasterBrand's overall financial health at a glance.
Looking For More Investment Ideas Beyond MasterBrand?
Once you have a view on MasterBrand, it can help to compare it with other opportunities that fit different risk and income profiles using the Simply Wall St Screener. That way you are not relying on a single story, and you can see how the numbers stack up across a wider set of businesses.
- If you want potential mispricings with stronger fundamentals than the headline suggests, scan through the 19 high quality undiscovered gems and see which ones merit a closer look.
- For readers who prefer resilience and steadier balance sheets, filter for companies with stronger financial footing using the 29 resilient stocks with low risk scores.
- If income is a priority and you care about cash returns today, check out companies offering higher yields through the 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com