
Missed Out On Genco Shipping & Trading's Rally? Here's The Bet Holders Made
If you had bought Genco Shipping & Trading on 2 November 2025 and simply held through a year of takeover bids, proxy skirmishes and rich dividends, the outcome looks very different to what early headlines hinted at. Holding Genco Shipping & Trading over the past year would have returned 59.6%, including dividends. If that decision were in front of you again, would the known trade and emissions risks still outweigh the lure of tightening vessel supply and an aggressive bidder circling the fleet?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Genco Shipping & Trading has already moved. See which of 34 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing On Genco Shipping & Trading
The shares cost US$17.04 at the start of the period, and anyone looking at Genco Shipping & Trading then faced two very different stories that still both sounded reasonable.
The bullish narrative put fair value at US$20.16, built on tight Capesize vessel supply and expectations that Brazil and West Africa iron ore and bauxite volumes would lift utilization and earnings.
The bearish view set fair value at US$15.23, focused on stricter emissions rules, rising compliance costs, and a belief that more regional trade could cut tonne-miles and pressure margins.
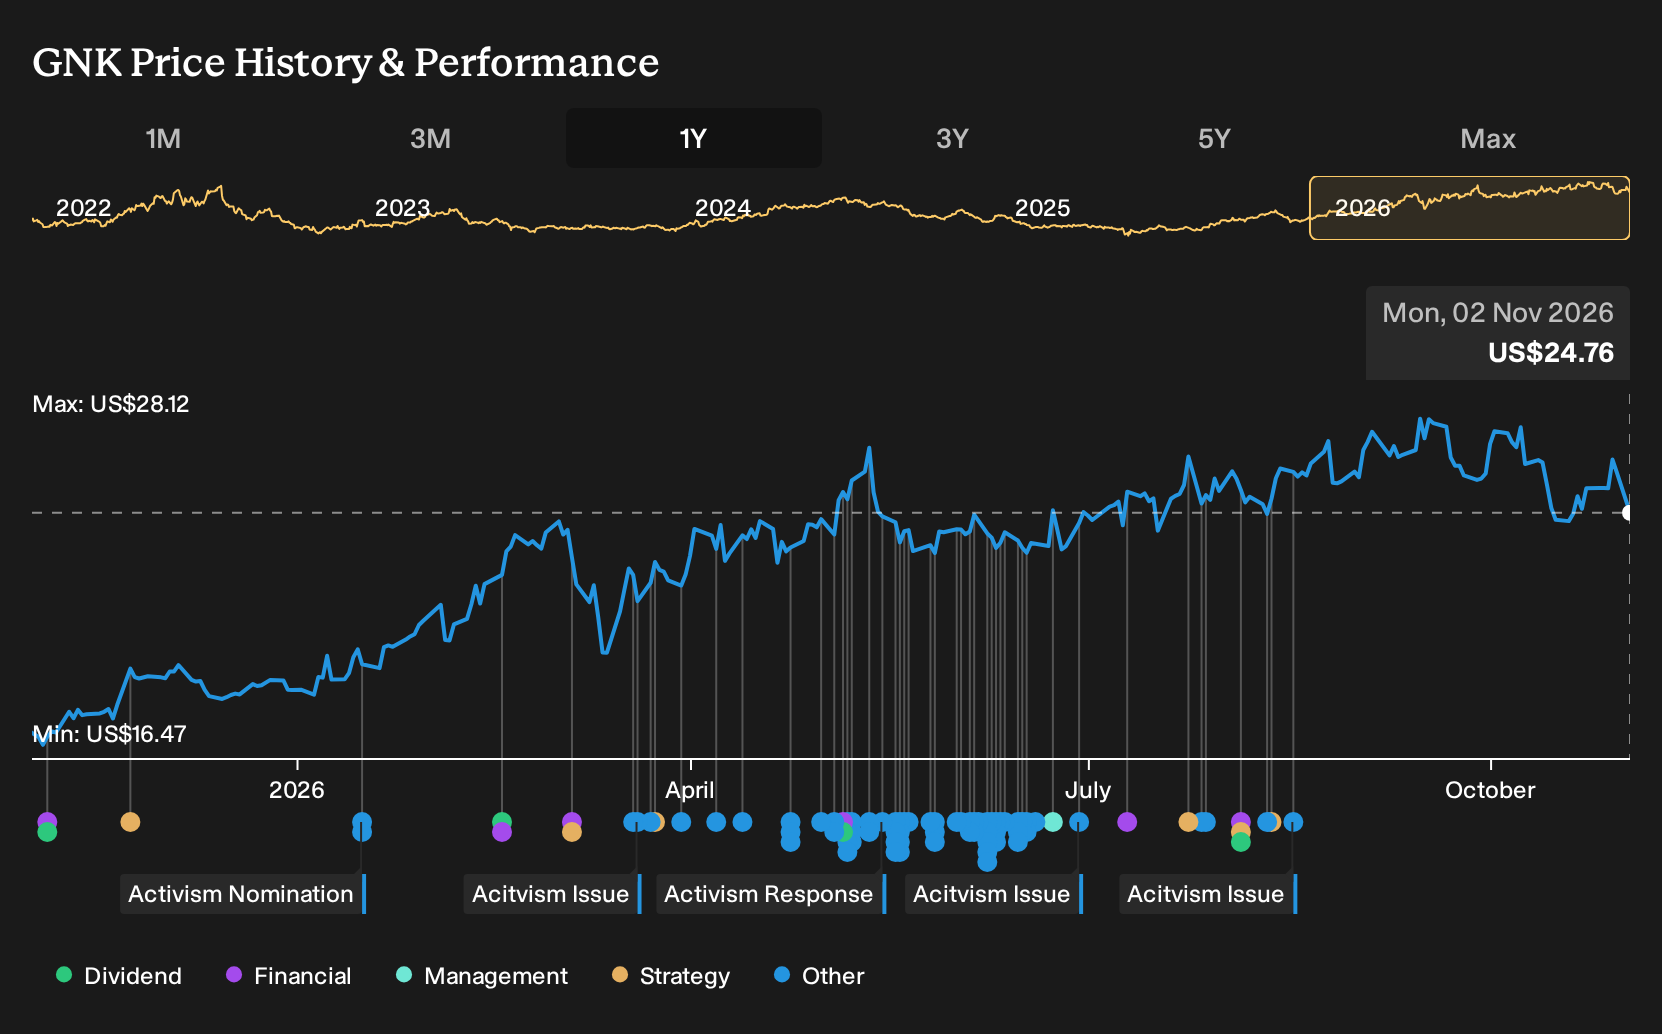
What The Results Changed For Genco Shipping & Trading
Q2 2026 put hard numbers behind the bullish narrative for Genco Shipping & Trading. Revenue rose from US$80.9m to US$136.4m, and a prior Q2 2025 loss of US$6.8m turned into a US$16.6m profit. Net margin moved from an 8.4% loss to a 12.2% gain, so profitability support leaned toward the optimistic case, even with takeover noise unresolved.
The lesson is simple. When a story leans on operating leverage and margins, check how net income and net margin move together in the results, not just where freight commentary or takeover headlines draw the eye.
What You Would Be Paying For In Genco Shipping & Trading Now
At today's share price of US$24.76, this Narrative's Fair Value sits above the current price, so the modelled case still sees more in Genco Shipping & Trading than the market is pricing in.
The argument leans on tight Capesize supply, a modern fleet and low leverage. A buyer now would need to believe that long haul dry bulk demand and freight rates stay strong enough for that fleet and balance sheet to keep doing the heavy lifting.
"The thesis on Genco Shipping & Trading has been reviewed and reaffirmed. The updated view gives more weight to tight Capesize supply, the company’s low net loan-to-value balance sheet and dividend-focused capital allocation, while acknowledging recent earnings and valuation risks more explicitly."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
How Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 37% below our estimate - turns shorter brownfield tieback cycles into higher margin subsea orders and services contracts.
- Company 2 - 30% below our estimate - ties AI workloads, subscriptions and usage-based services into one expanding cloud infrastructure footprint.
- Company 3 - 38% below our estimate - uses a large reserve base and ongoing exploration to extend mine life despite higher operating costs.
Three companies from the same screener. Open all 24 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com