
Marriott International (MAR) Earnings Beat Puts Its Valuation Back In Focus
Marriott International (MAR) just posted third quarter 2026 results, with revenue of US$7.01b and net income of US$794m, a backdrop that gives fresh context for the recent share price move.
The 4.3% 1 day share price gain to US$416.30 came as investors reacted to Marriott International’s Q3 beat and raised 2026 guidance. This reinforced an already strong run, with a 1 month share price return of 16% and a 1 year total shareholder return of 59.1%, suggesting momentum has been building rather than fading.
Scan how Marriott International’s earnings beat compares with other travel and leisure names showing strong trends using the hand picked 34 high quality undervalued stocks screener.
So is Marriott International’s sharp rally a clean read on a stronger hotel business, or has enthusiasm simply raced ahead of what the new numbers justify on valuation?
Most Popular Narrative: 3% Undervalued
Against Marriott International’s last close at $416.30, the most widely followed narrative pins fair value at $429.00. This frames the recent surge as only a modest stretch rather than a runaway move.
The main thing that has to go right is that Marriott International continues to execute on its asset light global expansion, technology and AI driven distribution upgrades, and owner friendly economics, so that net unit growth and fee revenue targets remain on track despite regional pressures such as the Middle East.
See why 1 investors see Marriott International as 3% undervalued.
Result: Fair Value of $429.00 (ABOUT RIGHT)
Still, the narrative can crack if Middle East RevPAR pressure spreads further, or if richer owner incentives drag on Marriott International’s fee margins more than expected.
Find out about the key risks to this Marriott International narrative.
Another View: Marriott International Through The Earnings Multiple Lens
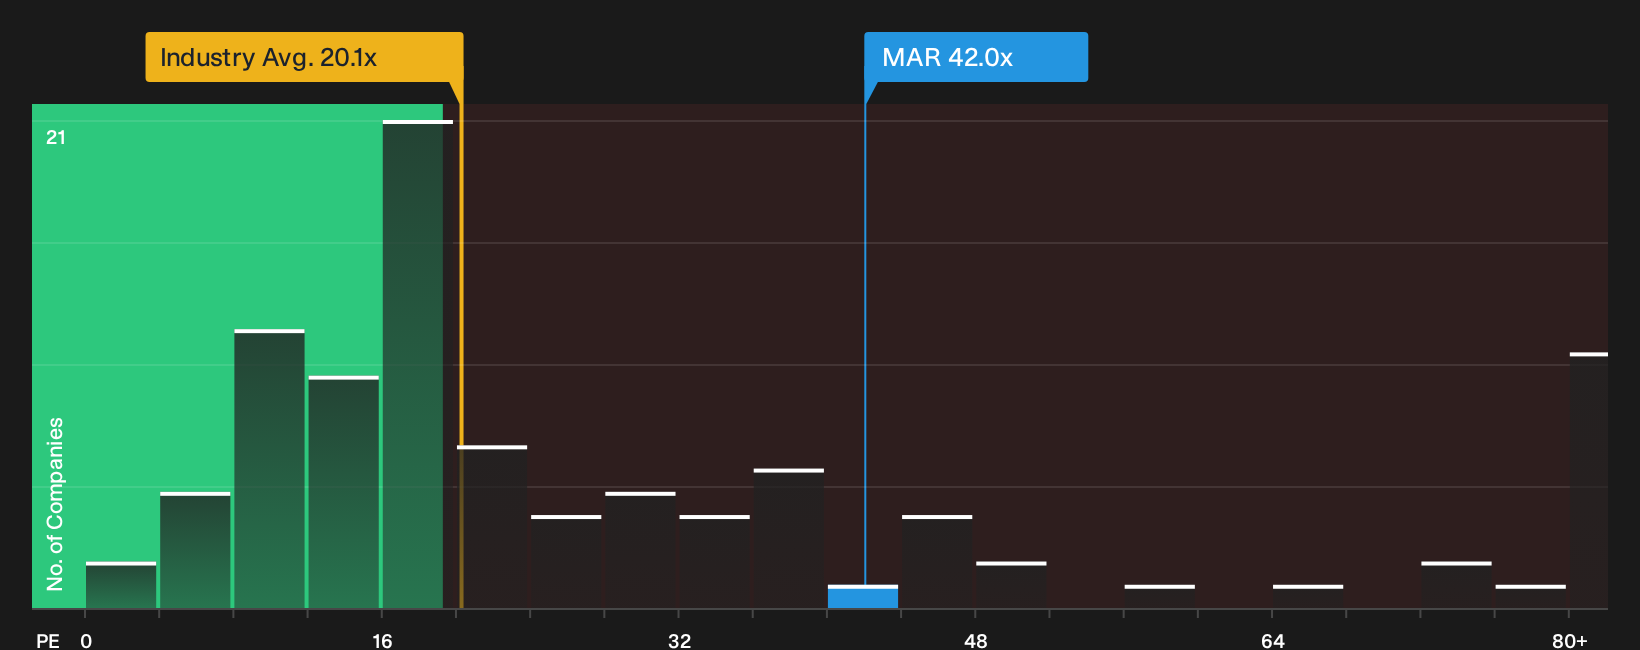
The bullish narrative frames Marriott International as roughly fairly priced around $429. Yet the P/E ratio of 42x tells a different story. It is much higher than both the US Hospitality sector on 20.1x and the peer group at 30x, and also above a fair ratio of 29.7x. This points to richer expectations baked into the current quote. That gap increases the risk that even solid execution might not be enough if sentiment cools.
See what the numbers say about this price in more detail by going through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Marriott International is confident but divided, and the gap between risk and reward may change quickly. To see both sides clearly and pressure test your own view against the data, look at the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Marriott International?
If Marriott International has sharpened your appetite for quality, do not stop here. Use the Simply Wall Street Screener to hunt for your next idea while this momentum is front of mind.
- Target reliable income streams by scanning companies that feature the 4 dividend fortresses.
- Hunt for potential bargains with solid business cases using the 19 high quality undiscovered gems.
- Protect your downside by focusing on companies in the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com