
What Dorman Products (DORM)'s Lower Sales Outlook Means For Shareholders
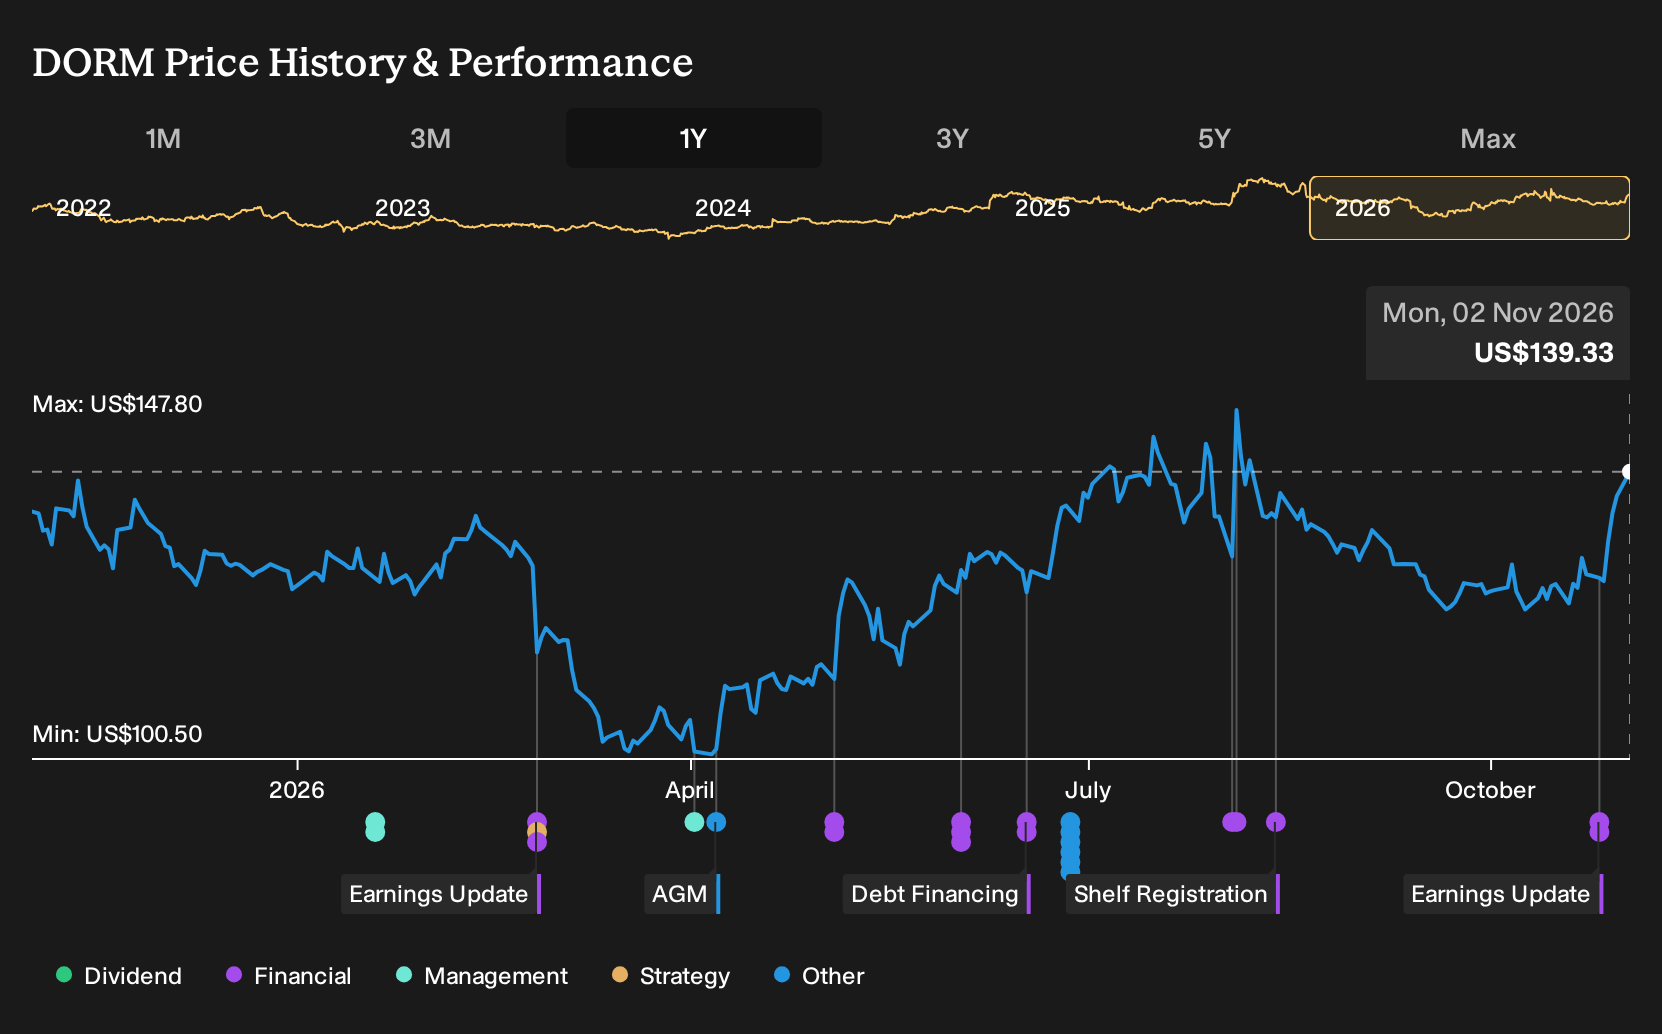
- Dorman Products reported past third quarter 2026 sales of US$561.72 million with net income of US$59.18 million, and reduced full year 2026 net sales growth guidance to 2% to 3% while keeping diluted EPS guidance broadly similar.
- The updated outlook points to pressure on revenue growth while management leans harder on cost control to hold earnings levels, even as new OE FIX products extend Dorman Products' higher value replacement parts offering.
- The focus now shifts to how Dorman Products' softer sales outlook and margin dependent earnings guidance may reshape the broader investment narrative.
Scan how Dorman Products stacks up against other parts suppliers that rely on cost control and product breadth by reviewing the hand picked list of solid balance sheet and fundamentals (24 results).
Dorman Products Investment Narrative Recap
To own Dorman Products, you need to believe its large aftermarket footprint and OE FIX focus can translate modest sales growth into steady earnings through margin discipline. The lowered 2026 net sales growth guidance to 2% to 3% places more emphasis on execution rather than volume as the key driver.
The near term catalyst is whether management can deliver the guided diluted EPS of US$7.95 to US$8.15 with only low single digit revenue growth. The biggest risk right now is that cost pressures or weaker order volumes erode margins, given Q3 net income and EPS were lower than a year earlier.
The most relevant update for that thesis is the new 2026 guidance issued on 26 October. Management now expects net sales growth of 2% to 3%, compared with the prior 3% to 5% range, while keeping the EPS outlook in a narrow band. That indicates profitability is expected to lean more on costs and mix.
For you as an investor, the question is whether Dorman Products can hold that EPS range if demand softens further or if tariffs or input costs increase again. Execution on catalog breadth and OE FIX launches, along with discipline on pricing and overheads, will likely influence how much room there is above or below that earnings corridor.
Dorman Products' current narrative projects US$2.5 billion in revenue and US$336.0 million in earnings by 2029. This projection is based on an assumed 5.2% yearly revenue growth and an earnings increase of about US$116.7 million from the current US$219.3 million level.
Uncover why Dorman Products' fair value indicates a 16% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Community fair value views on Dorman Products from 2 Simply Wall St Community members cluster between about US$141.78 and US$161.63 per share, yet those opinions do not reflect the latest earnings dip, softer 2026 sales guidance or new OE FIX launches. Treat that spread as a starting point, and compare it with your own thesis on margins, tariffs and long vehicle lives.
Explore another Dorman Products fair value estimate, including one that suggests it could be worth just $141.78.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Dorman Products research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Dorman Products. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dorman Products' overall financial health at a glance.
Looking for more ideas beyond Dorman Products?
If Dorman Products has sharpened your thinking about margins, balance sheets and long term earnings power, broaden that lens across other listed businesses using the Simply Wall St Screener.
- For potential mispriced opportunities with solid fundamentals, review a curated 34 high quality undervalued stocks that may warrant a closer look.
- If resilience matters most to you, filter for stability using a 29 resilient stocks with low risk scores that screens for sturdier financial profiles.
- When you want quality that is still flying under the radar, scan a 19 high quality undiscovered gems that focuses on under-followed companies with stronger numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com