
Seagate (STX) Stock Trades At A Discount After A 7x Run
Seagate Technology Holdings has delivered very strong long term share gains, even as the stock has recently pulled back, which raises a straightforward question for you as an investor: Is the current price giving you an earnings profile that makes sense for what this business is now expected to earn over time?
- Over the past 3 years, Seagate has returned about 7x, so a lot of future earnings power is already in focus when you look at the current valuation.
- Recent reports of stronger revenue, higher profitability and growing demand for HAMR based storage in data centers can support expectations for higher earnings and cash generation in the coming years, which directly feeds into how rich or thin today’s earnings multiple looks.
- The analysts covering Seagate Technology Holdings have run their own numbers. See what analysts think Seagate Technology Holdings's shares could be worth.
The issue now is whether Seagate’s recent share price, after a very strong multi year run and some sharp short term swings, is adequately supported by the earnings it is generating and expected to produce.
If you want a wider lens on AI and data storage, consider using a focused screen of 53 AI infrastructure stocks as another starting point for your research.
Is Seagate Technology Holdings a Bargain on Earnings?
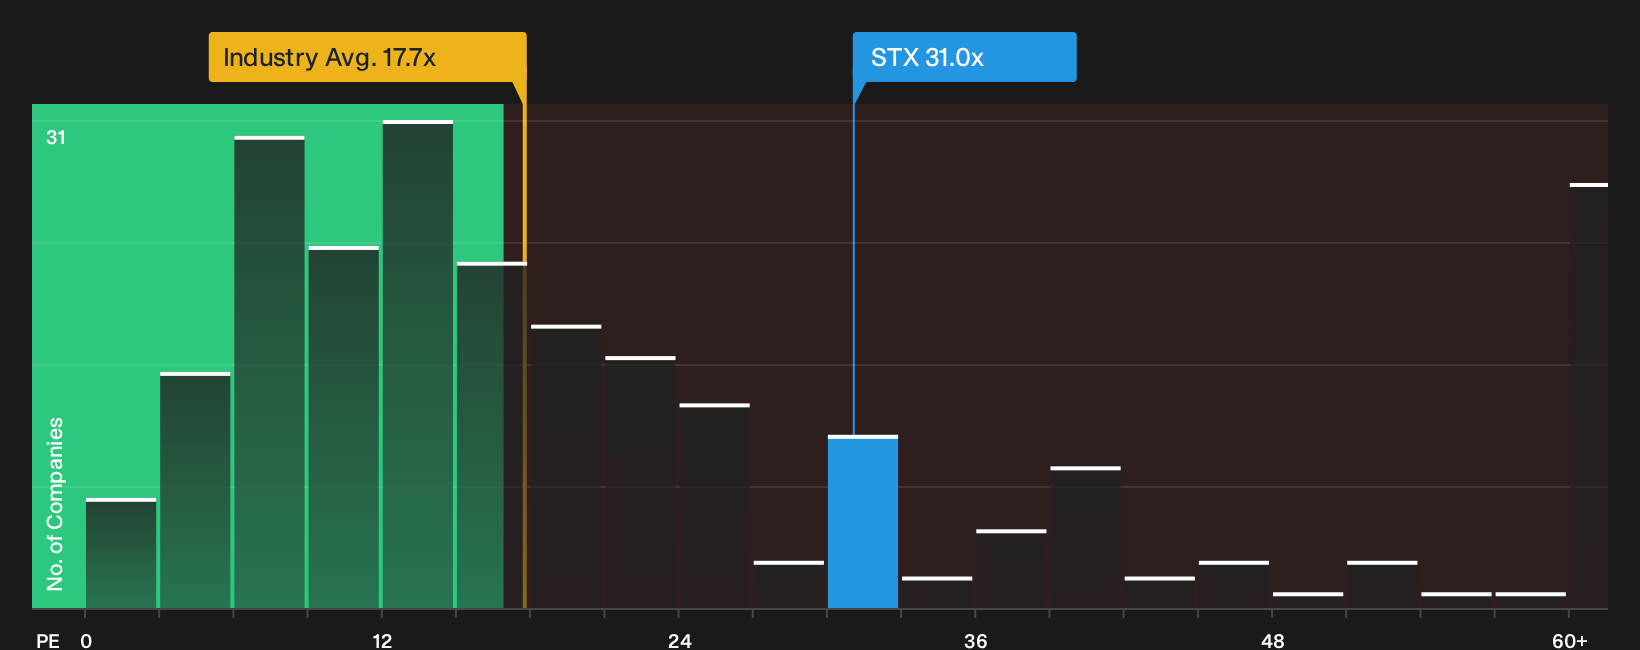
The P/E lens fits Seagate Technology Holdings because the story investors are paying for is primarily about earnings power from AI driven storage demand. On current numbers, the stock trades on a P/E of 31.0x, which is meaningfully richer than the broader Tech group on 17.7x and above peer hardware and storage players at about 17.0x. That gap tells you the market is already assigning a premium tag to Seagate’s income stream rather than treating it as a typical sector player.
Recent headlines around record quarterly revenue, strong profitability and HAMR adoption help explain why investors are willing to pay up, because those developments focus attention on earnings durability and cash generation. Even so, the current P/E still sits below a more tailored fair multiple that blends Seagate’s growth profile, margin structure, size and risk mix. This points to the stock screening as undervalued on this framework rather than stretched. For anyone assessing whether today’s valuation compensates for execution and sector cycle risks, this gap between price and implied fair P/E is the key figure to explore further. Explore the numbers behind Seagate Technology Holdings's P/E valuation.
The Seagate Technology Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Seagate Technology Holdings pick up where the P/E debate leaves off by explaining which potential paths for growth, margins and earnings would need to occur for the current share price to appear either too low or too high. Each narrative links a fair value estimate to a clear story about Seagate Technology Holdings' possible catalysts and key risks, so you can track over time which version of events seems to be taking shape on the Community page.
One of the top community narratives on Seagate Technology Holdings: 49% undervalued
"Nearline hard drives are different. They are the only economically viable way to store data at hyperscale; the cost-per-terabyte gap versus flash is widening…"
Discover why this Narrative puts Seagate Technology Holdings at 49% undervalued.
The Seagate Technology Holdings share price is only one decision point
Even if Seagate Technology Holdings looks interesting on earnings and narrative, the research checks have also flagged specific areas of concern that deserve your full attention before you commit fresh capital. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com