
3 Australian Undervalued Stocks To Own In November 2026
The Reserve Bank of Australia has just lifted interest rates to the highest cash rate since 2008, which is putting pressure on heavily indebted and cash hungry businesses. Companies that generate solid cash flows yet trade below fair value suddenly look a lot more interesting. This article walks through three Australian stocks that screen as underpriced on discounted cash flow analysis and explains why patient, value-focused investors may want them on the watchlist.
The three stocks covered below are only a starting sample, and the full discounted cash flow screen on Simply Wall St has revealed 4 more Australian companies with similarly compelling cash flow stories that are not included here.
Head straight into the Undervalued Stocks Based On Cash Flows screener to identify, filter and analyze the highest conviction ideas for your own watchlist.
Greatland Resources (ASX:GGP)
Overview: Greatland Resources is a gold and copper developer focused on the Havieron project in Western Australia, where future mine output underpins its cash-flow-based valuation.
Operations: Greatland Resources currently attributes A$2.3b of revenue to the Telfer Havieron segment, reflecting its concentrated exposure to this single project.
Market Cap: A$6.3b
Greatland Resources matters for this cash-flow-focused screen because Havieron is moving from concept toward production, where real output and costs will start to test the assumptions behind its discounted cash flow story.
"The primary driver of Greatland’s future is the gold price. As a single-asset developer moving toward production, it offers significant operational leverage to gold."
What happens if one key input shifts in the wrong direction could make a big difference to eventual free cash flow quality.
That cash flow swing factor is exactly what sits at the heart of the full narrative for Greatland Resources, where the gold leverage, funding path and downside cushions are all unpacked.
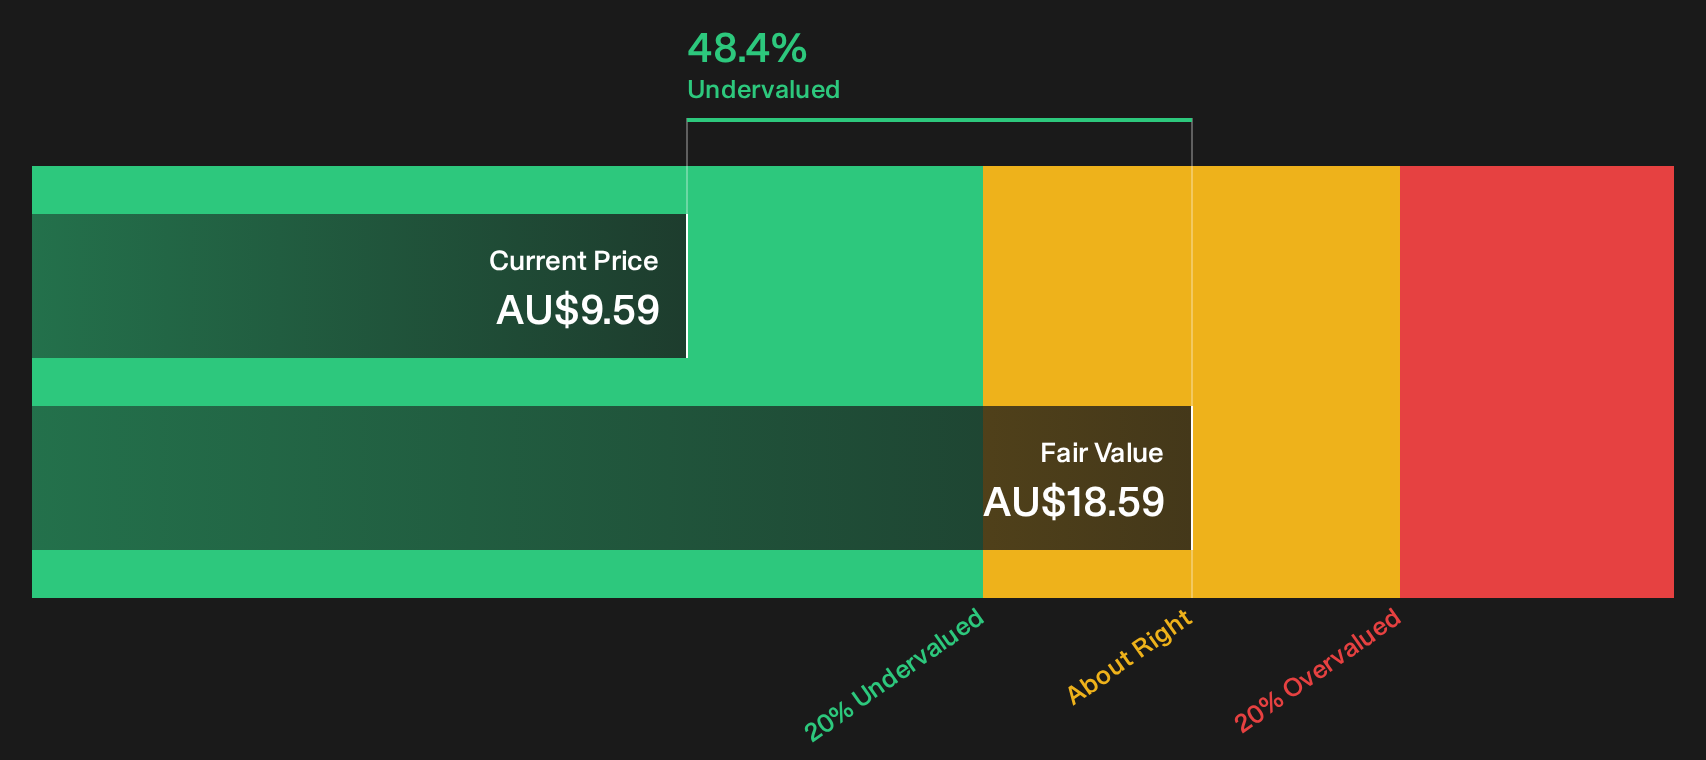
Ansell (ASX:ANN)
Overview: Ansell provides medical and industrial protective gear, with healthcare gloves and consumables supplying recurring, cash-focused exposure to global hospital demand.
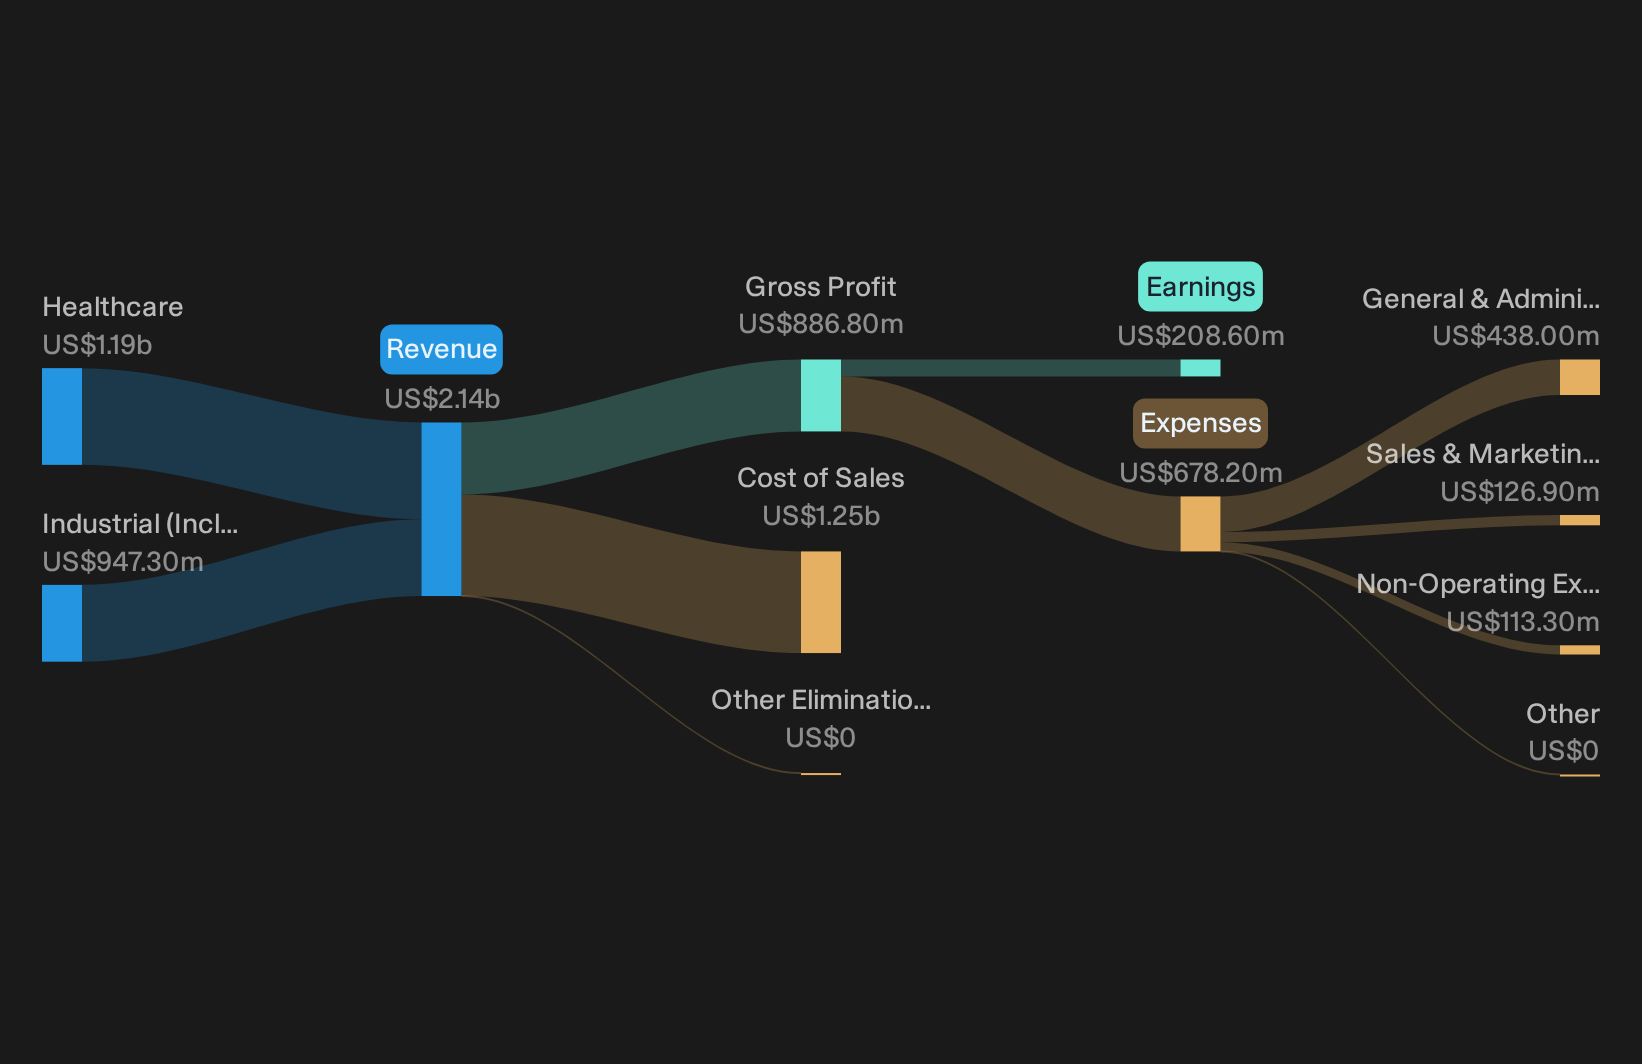
Operations: Ansell generates US$1.2b from Healthcare and US$947 million from Industrial products, with revenue spread across North America, Europe, Asia Pacific and other regions.
Market Cap: A$6.2b
Ansell appears on this undervalued-on-cash-flows screen because its glove and healthcare consumables portfolio turns regular hospital usage into repeatable cash generation that is not fully reflected in the current pricing.
"Ansell is positioned to participate in increased structural demand in PPE, driven by tightening workplace-safety regulation, rising healthcare and hygiene standards, and continuing industrialisation in emerging markets."
A shift in one unseen pressure on its healthcare consumables margins in an unfavourable direction could reshape that cash-flow profile quickly.
That pressure point is exactly what the full narrative for Ansell unpacks, revealing where margin risk may be masking accelerating cash potential in Ansell’s healthcare engine.
Woodside Energy Group (ASX:WDS)
Overview: Woodside Energy Group is a Perth based producer and marketer of LNG and other hydrocarbons, supplying global buyers from long-life assets.
Operations: Woodside Energy Group reports about $7.3b of revenue from Australia, $4.6b from International operations and $1.9b from Marketing activities.
Market Cap: A$63.5b
Woodside Energy Group matters for this cash-flow focused screen because its LNG projects feed long-term contracts that can support steady, model-friendly cash generation for discounted cash flow analysis, even as the wider portfolio stretches across oil, liquids and newer energy ventures.
"Investor optimism appears driven by robust expectations for long-term demand growth in Asian and emerging markets, with Woodside's global LNG expansion (Louisiana, Scarborough) positioned to capture this growth; however, these assumptions may underestimate the potential for rapid decarbonization policies or renewable adoption, risking future revenue and volume growth if LNG demand softens in key markets."
What happens if one unseen pressure on those long‑dated LNG contracts shifts in the wrong direction could reshape Woodside’s cash-flow story quickly.
If you want to see how that contract risk could flip into accelerating opportunity, the full narrative for Woodside Energy Group shows where Woodside Energy Group’s LNG cash flows may decouple.

Curious About What You Might Be Missing?
Fresh ideas move first, and laggards get caught watching as momentum builds, prices start flying, and entry points keep dropping out of reach. Scan the next wave and act now.
- Spot steady potential in companies built to weather shocks by reviewing a curated list of solid balance sheet and fundamentals (12 results) before they shift onto everyone else's radar.
- Ride powerful payout momentum by focusing on a hand picked group of 5 dividend fortresses while yields still look attractive relative to current prices.
- Track early movers in the energy transition by reviewing carefully filtered 16 nuclear energy infrastructure stocks before market attention crowds into the same trades.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com