
Avista (AVA) Could Be 7% Undervalued After Washington Rate Case Progress
Regulatory progress puts Avista in focus
Investors are reacting to progress on Avista (AVA)'s proposed electricity rate increase in Washington, as regulators move closer to approving most of the request and reshaping expectations around earnings stability and dividend support.
Avista's share price has picked up momentum in recent weeks, with a 1 month share price return of 8.67% and a 7 day gain of 3.06%, even though the 90 day move still shows a 2.14% decline. That short term shift sits on top of a 5.58% 1 year total shareholder return and 27.72% over three years. This suggests the latest rate case progress is feeding into a gradually improving sentiment around the utility's long run income and dividend profile.
Compare Avista's rate case driven momentum with a curated 43 power grid technology and infrastructure stocks that is also tied to grid investment and regulated returns.
After this sharp move, Avista now poses a simple trade off. Do you pay up for the improving regulatory picture today, or wait and hope for a cheaper entry later as valuation comes into focus?
Most Popular Narrative: 7% Undervalued
Avista's most followed narrative pins fair value at $41.33, which sits above the recent $38.37 close and frames the current move as a catch up rather than exuberance.
The multiyear capital investment plan for Avista Utilities has been updated from approaching US$3b in 2025 to 2029 to US$3.4b in 2026 to 2030, with additional potential US$350m of incremental investment tied to large-load connections and regional transmission needs, which can increase regulated rate base and support earnings growth if executed within allowed returns.
See why 7 investors see Avista as 7% undervalued.
Result: Fair Value of $41.33 (UNDERVALUED)
Still, wildfire exposure and power cost swings could pressure Avista’s allowed returns and push management into heavier debt or equity funding than investors currently expect.
Find out about the key risks to this Avista narrative.
Another View: Our DCF model paints a tighter picture
Analysts see Avista as undervalued using earnings and a fair value of $41.33, but our DCF model tells a different story. On a future cash flow basis, Avista screens slightly overvalued, with the share price at $38.37 versus an estimated value of $35.17. Which lens do you trust more when cash flows and earnings point in different directions?
For readers who want to see how cash flow assumptions drive that gap, and how sensitive Avista's value is to small tweaks in growth or discount rates, Look into how the SWS DCF model arrives at its fair value.
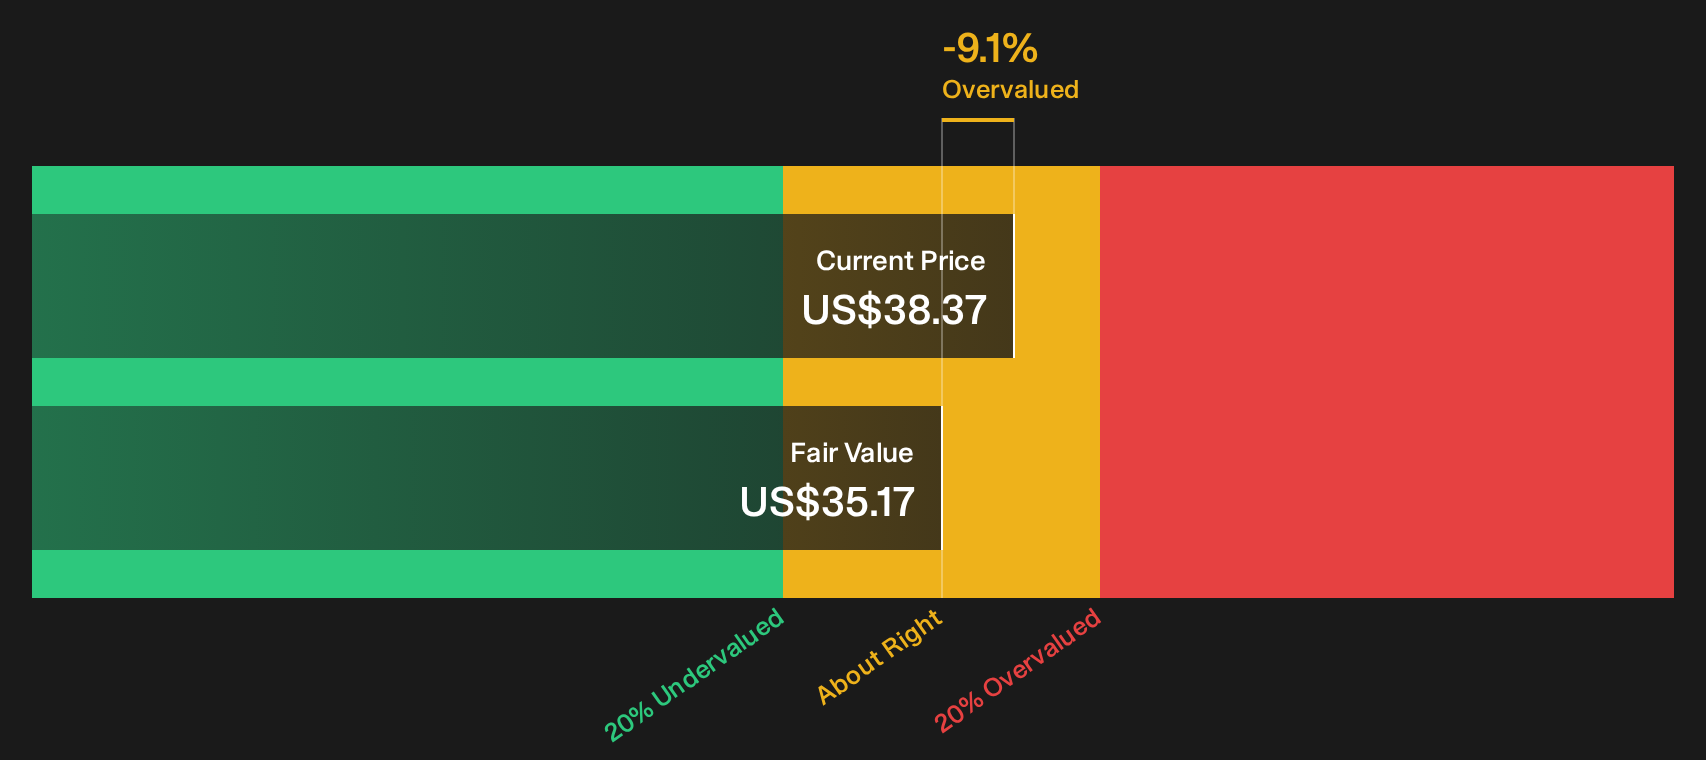
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Avista for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around Avista feels finely balanced, it may be worth acting promptly. Review the data and decide where you stand with 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Avista?
If Avista has sharpened your thinking, use that momentum. Test your thesis building skills on other opportunities that fit clear, disciplined criteria.
- Target stronger balance sheets by scanning a list of solid balance sheet and fundamentals (24 results) that filters for businesses with cleaner debt profiles and sturdier financial footing.
- Hunt for mispriced quality through a 34 high quality undervalued stocks that highlights companies where fundamentals and current market pricing appear out of sync.
- Prioritize resilience by checking a 29 resilient stocks with low risk scores focused on stocks with lower risk scores so potential setbacks do not blindside your portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com