
LGI Homes Stock In Focus Ahead Of Revenue Growth Return
- LGI Homes, an affordable single family home builder listed on Nasdaq as LGIH, is set to report earnings on the upcoming Tuesday, with the market expecting revenue to be 9.2% higher than the same quarter last year after a 39.2% decline in that prior period.
- The key shift is not just the anticipated revenue change for LGI Homes but also the stabilizing view that its current business trajectory and execution are broadly intact, reflected in analyst estimates that have held steady in the 30 days leading into the report.
- We will now look at how expectations for a 9.2% revenue uplift might reshape the existing investment narrative around LGI Homes for readers.
Scan how LGI Homes stacks up against other builders preparing for potential momentum shifts by reviewing our curated list of 34 high quality undervalued stocks.
LGI Homes Investment Narrative Recap
For LGI Homes, the core belief is that there is durable demand for affordable, entry level houses, and that its owned land bank and spec building model can convert that demand into steady closings. The expected 9.2% revenue uplift this quarter matters mainly as a test of whether order trends and cancellations are stabilising after recent pressure on payment sensitive buyers.
In the short term, the key catalyst is evidence that incentives and rate buydowns are turning more traffic into firm, funded buyers without eroding already thinner 3.9% net margins. The biggest immediate risk remains affordability and financing strain, which could force heavier discounts or slower community ramps even if headline revenue looks better.
With no fresh company announcements tied directly to this earnings date, the most relevant reference point is LGI Homes' existing multi year land pipeline and community rollout plans in states such as Texas, North Carolina and West Virginia. Those projects frame how investors might view any revenue swing this quarter.
If the upcoming numbers show that new and existing communities are converting backlog into closings while construction costs and tariffs are managed, that would speak directly to the current catalysts around unit growth and margin resilience. If instead the report highlights slower absorption or heavier incentives across that footprint, readers may focus more on liquidity, debt coverage by operating cash flow and the sensitivity of this model to prolonged affordability stress.
LGI Homes' current analyst script points to US$2.5b in revenue and US$117.1m in earnings by 2029, based on an assumed 14.8% yearly increase in revenue and an earnings increase of about US$50.9m from US$66.2m today.
Uncover why LGI Homes' fair value indicates a 96% potential upside to its current price that may not last much longer.
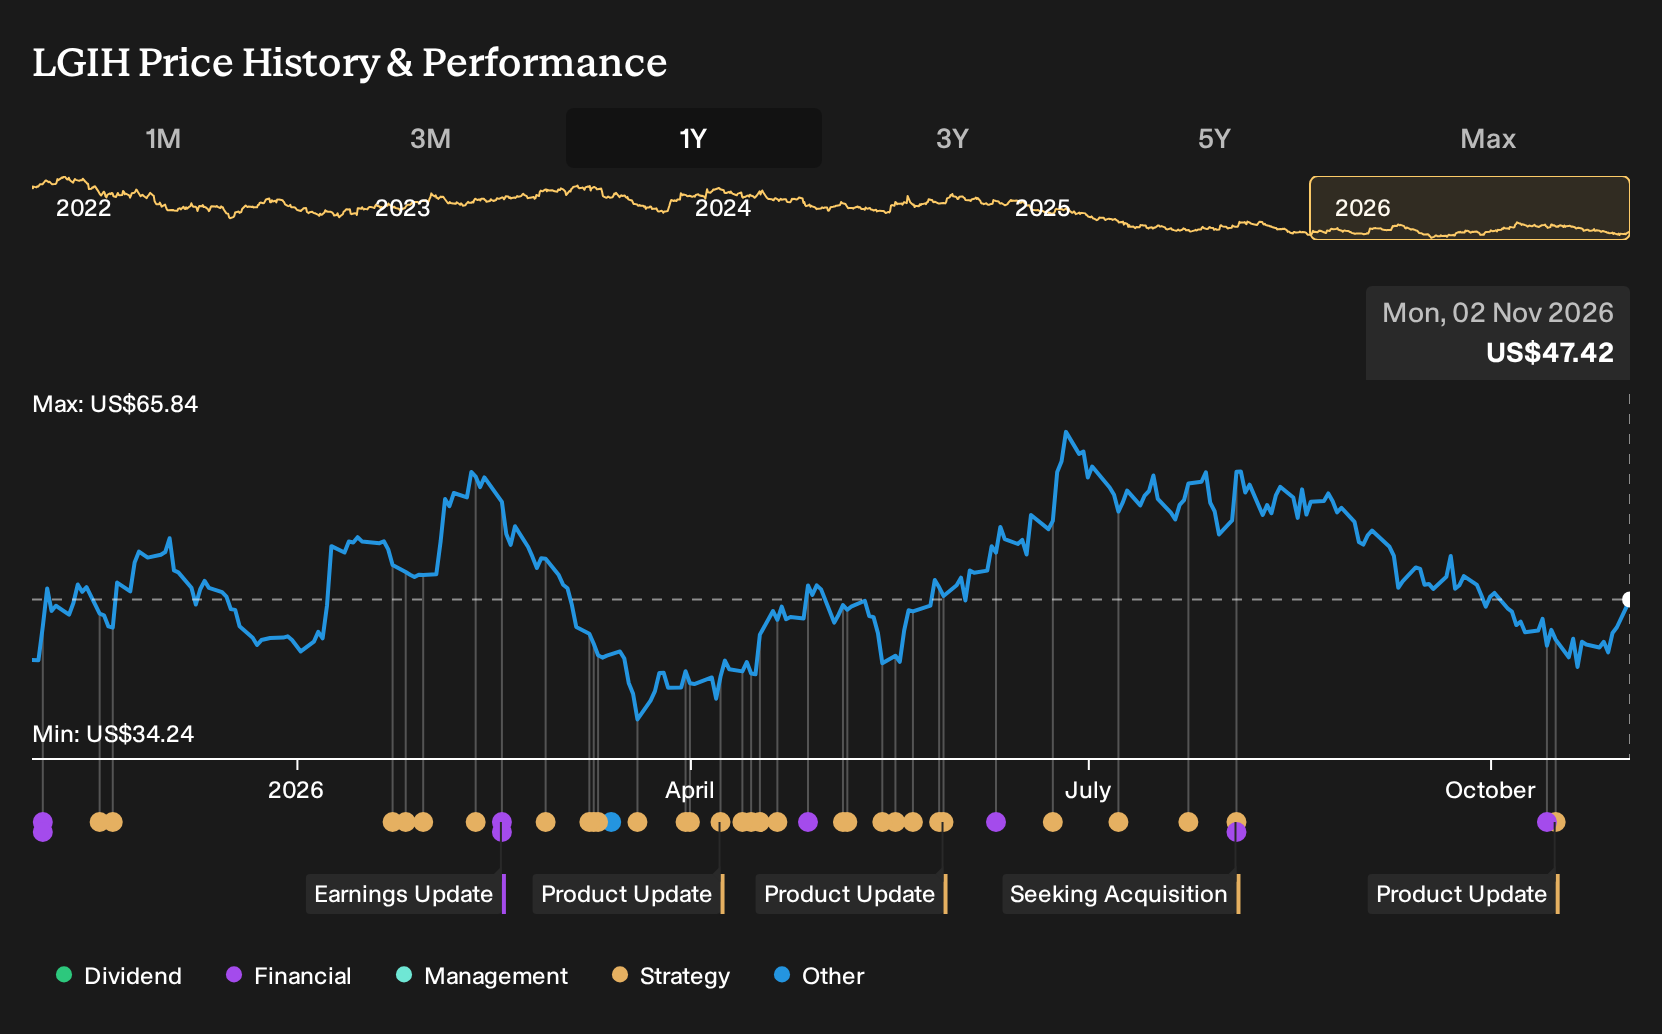
Exploring Other Perspectives
One alternate view on LGI Homes leans heavily on debt reduction as the real catalyst. The most optimistic analysts were modelling revenue of about US$2.7b and earnings near US$130.5m by 2029 before this earnings release. That is far more upbeat than baseline estimates, and fresh results could easily shift both narratives.
Explore 2 other LGI Homes fair value estimates, including one that suggests there may be as much as 96% upside from the current price.
Decide For Yourself
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your LGI Homes research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for LGI Homes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate LGI Homes' overall financial health at a glance.
Looking For More Investment Ideas Beyond LGI Homes?
Once you have a view on LGI Homes, it can help to widen the lens and benchmark it against other opportunities that fit different risk profiles and income goals. The Simply Wall St screener makes that process faster by letting you filter for specific traits instead of scrolling through tickers at random.
- For readers who care most about financial resilience, start with companies that pair sturdy balance sheets with solid fundamentals using our list of solid balance sheet and fundamentals (24 results).
- If capital preservation and smoother ride potential are higher on your list, focus on businesses that score well on stability metrics through the 29 resilient stocks with low risk scores.
- When you want to look earlier in the research chain, before the crowd catches on, search for under-the-radar opportunities with strong fundamentals using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com