
Is Tempus AI (TEM) Overvalued Even After Raised 2026 Guidance?
Tempus AI has seen its share price move sharply in 2026, which puts fresh attention on a simple question for investors who care about valuation: Is the current market value of Tempus AI stock supported by the scale and trajectory of its sales?
- The stock is up 25.8% year to date. This raises the question of whether that kind of gain is matched by the revenue base that now underpins the company.
- Recent contracts with large pharmaceutical partners and progress in regulatory clearances can influence expectations for future sales and the durability of Tempus AI's commercial pipeline.
- There is a second opinion on Tempus AI worth weighing. See what analysts think Tempus AI's shares could be worth.
The issue now is whether the revenue that Tempus AI is generating today, and what investors reasonably expect it to produce next, is enough to justify the latest share price when judged against its sales.
If you are weighing Tempus AI on its sales story, it can help to compare it with other healthcare AI businesses using 33 healthcare AI stocks.
Is Tempus AI Getting Expensive on Sales?
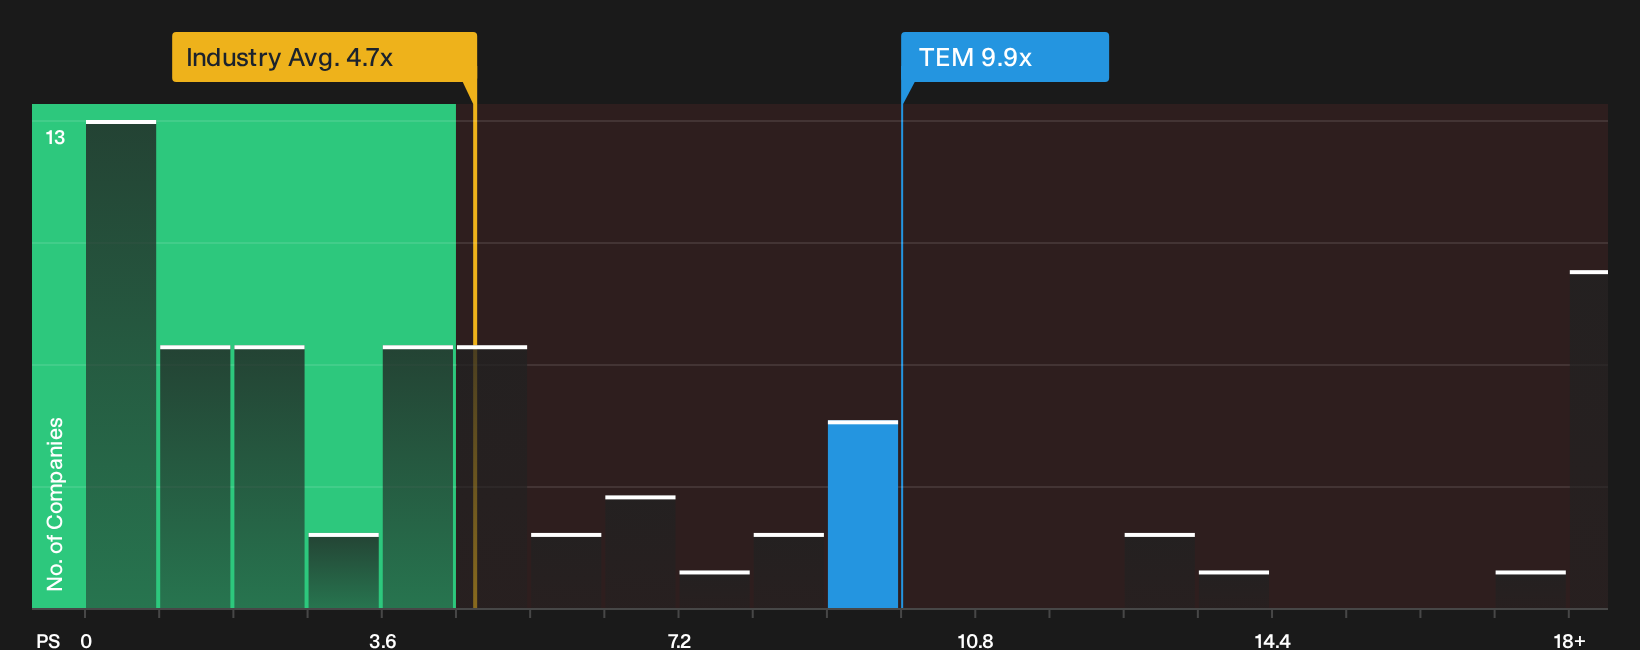
The P/S ratio fits Tempus AI because investors are mostly paying for its data assets and commercial reach rather than today’s profits. On this yardstick, the stock trades on a P/S of 9.9x, compared with a Life Sciences industry average of 4.7x and a peer group around 7.8x. That points to a valuation that is richer than both the wider sector and closer peers on each dollar of current revenue.
The fair-value model that blends Tempus AI's growth profile, margins, size and risk implies a lower P/S than the current level, which means the shares screen as overvalued on this sales-based lens. Because the company lifted full year 2026 revenue guidance after a strong Q3 print, the gap signals that recent contract wins and regulatory milestones are already heavily reflected in the price. For anyone assessing Tempus AI today, the key question is whether its commercial pipeline and data partnerships justify paying this kind of premium P/S multiple relative to what the model suggests as a more balanced figure. Explore the numbers behind Tempus AI's P/S valuation.
The Tempus AI Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Tempus AI pick up where the valuation puzzle leaves off. They explain which combinations of future growth, profit quality and earnings power would need to occur for Tempus AI's share price to sit meaningfully above or below where it trades today. Each narrative links its number to a clear view on how growth, margins and risk could evolve, giving you something specific to test as new information becomes available.
Community views on Tempus AI split between one group that sees extra upside and another that thinks the current setup already reflects much of the story.
Bull case: 22% undervalued
"The project to assemble 100,000 whole genomes with longitudinal clinical data, with a long term objective of one million genomes, sets up a proprietary multimodal dataset..."
Discover why this Narrative puts Tempus AI at 22% undervalued.
Bear case: roughly fairly valued
"Tempus has accumulated tens of millions of de-identified patient records and hundreds of petabytes of clinical and molecular data, assets that would take competitors years and enormous investment to replicate..."
Explore why this Narrative puts Tempus AI at roughly fairly valued.
One more piece on Tempus AI that could shift how you see the whole setup
Before you lean too hard on any current valuation lens, it helps to see where professional forecasters think this business might be a few years from now and how that compares. Explore where analysts expect Tempus AI to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com