
NNN REIT (NNN) Stock Still Looks Like A Bargain As Shares Returned 27%
NNN REIT has quietly put together a solid multi year run, which naturally raises a simple question for anyone looking at the stock today. Is the current share price asking too much of its earnings power, or does the income it generates still line up with what investors are paying?
- Over the past 3 years the stock has returned 27.3%, so anyone buying now has to judge whether that track record is already fully reflected in the price that the market assigns to its earnings.
- The business relies on long term net leases that can support relatively steady rental income. As a result, the key swing factor is how reliably that cash flow converts into earnings that justify the current P/E against the Fair Ratio benchmark.
- The analysts covering NNN REIT have run their own numbers. See what analysts think NNN REIT's shares could be worth.
For investors, the debate is whether NNN REIT's current valuation is adequately supported by the earnings the real estate portfolio is generating today and is expected to produce over time.
If you are weighing NNN REIT's recent 27.3% three year return against its current earnings based price, it can help to compare that decision with a focused list such as 34 high quality undervalued stocks.
Is NNN REIT Still Cheap on Earnings?
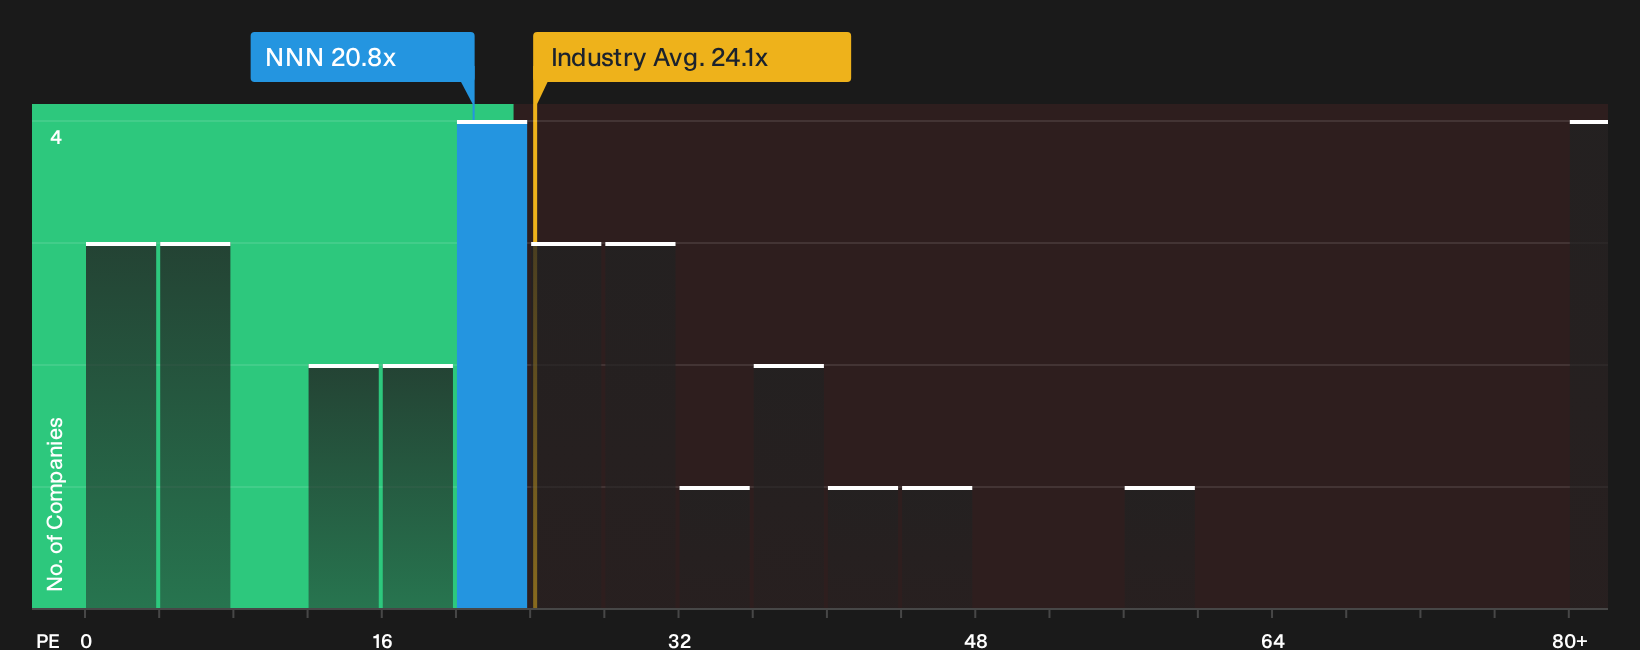
The P/E ratio fits NNN REIT because earnings are the cleanest link between its long term leases and what you pay for each share. On this lens, the stock trades at about 20.8x earnings, which is below the Retail REITs industry average of roughly 24.1x and also under the peer group at about 27.5x. For a landlord built around contracted rent, that kind of gap matters because it shows that investors are paying less for each dollar of current earnings than they are for many similar real estate businesses.
The Fair Ratio model, which aligns the P/E you might expect with NNN REIT's business quality, growth profile, scale and risk, points to a higher level than the present multiple. That places the current 20.8x in undervalued territory on this framework, even after factoring in the sector context. If you are weighing whether the share price is asking too much of today’s earnings power, this discount on the preferred P/E metric indicates it may be worth a closer look. Explore the numbers behind NNN REIT's P/E valuation.
The NNN REIT Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle leaves off for NNN REIT by spelling out which paths for growth, profitability and earnings would need to play out for the current valuation to look meaningfully too high or too low, and they sit on Simply Wall St's Community page. Each scenario links its number to a clear view on how NNN REIT's revenue trajectory, margins and risk profile might shift, giving you something concrete to revisit when fresh information comes through.
One of the top community narratives on NNN REIT: 6% undervalued
"Tenants pay rent and also carry most property costs, so NNN collects a long-term, largely predictable rent stream with minimal ongoing capital spending..."
Discover why this Narrative puts NNN REIT at 6% undervalued.
One more NNN REIT check that sits beside today’s price tag
Before you file NNN REIT away as fairly priced or not, it can be useful to see where professional coverage thinks earnings and cash flows might land a few years from now. Explore where analysts expect NNN REIT to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com