
Brazil Bank Stocks Under Pressure With Banco Do Brasil In Focus
Brazil’s post election selloff, with the real down 8.5% and the Bovespa falling about 18%, has turned domestic banks and financials into a stress test for Lula’s fiscal signals and the central bank’s next move. Volatility often rewrites price tags faster than fundamentals change, which can create mispriced risks and chances. This article walks through three Brazilian banking stocks exposed to these pressures and explains how the latest shock affects each one.
The stocks covered next are just a starter set, and the full screen surfaced 7 more Brazilian banks and financials with equally compelling stories that are not covered in this article. If you want to identify potential high conviction ideas quickly, head straight to the Brazilian Domestic Banks and Financials screener.
Banco Santander (Brasil) (BOVESPA:SANB11)
Overview: Banco Santander (Brasil) is a major Brazilian bank that provides everyday banking, lending, payments, insurance and investment services to individuals, small businesses and large corporates, closely tied to domestic credit demand and funding conditions.
Operations: The bank generates most of its income from Commercial Banking with about R$36.4b in revenue, alongside roughly R$10.1b from Global Wholesale Banking.
Market Cap: R$89.6b
Banco Santander (Brasil) sits at the intersection of this screener theme and the real economy, with its retail and SME engine directly exposed to rate moves and credit spreads. This is one reason why small changes in customer behavior can matter so much now.
"Santander Rewards, with 15% of eligible customers already enrolled and a 30% rise in registered Pix keys by 2Q26, can encourage a larger share of clients to use Banco Santander Brasil as their primary bank, which supports higher payments revenue and card fee income per customer."
What happens to margins and earnings will hinge on how one unresolved pressure in funding costs and loan quality ultimately plays out.
That funding squeeze is the real hinge, and the full narrative for Banco Santander (Brasil) lays out how Banco Santander (Brasil) could still turn this volatility into accelerating customer economics and fee momentum.

Banco do Brasil (BOVESPA:BBAS3)
Overview: Banco do Brasil is a large state controlled universal bank that channels deposits into loans and financial services for households, businesses, agribusiness, and public sector clients in Brazil and abroad.
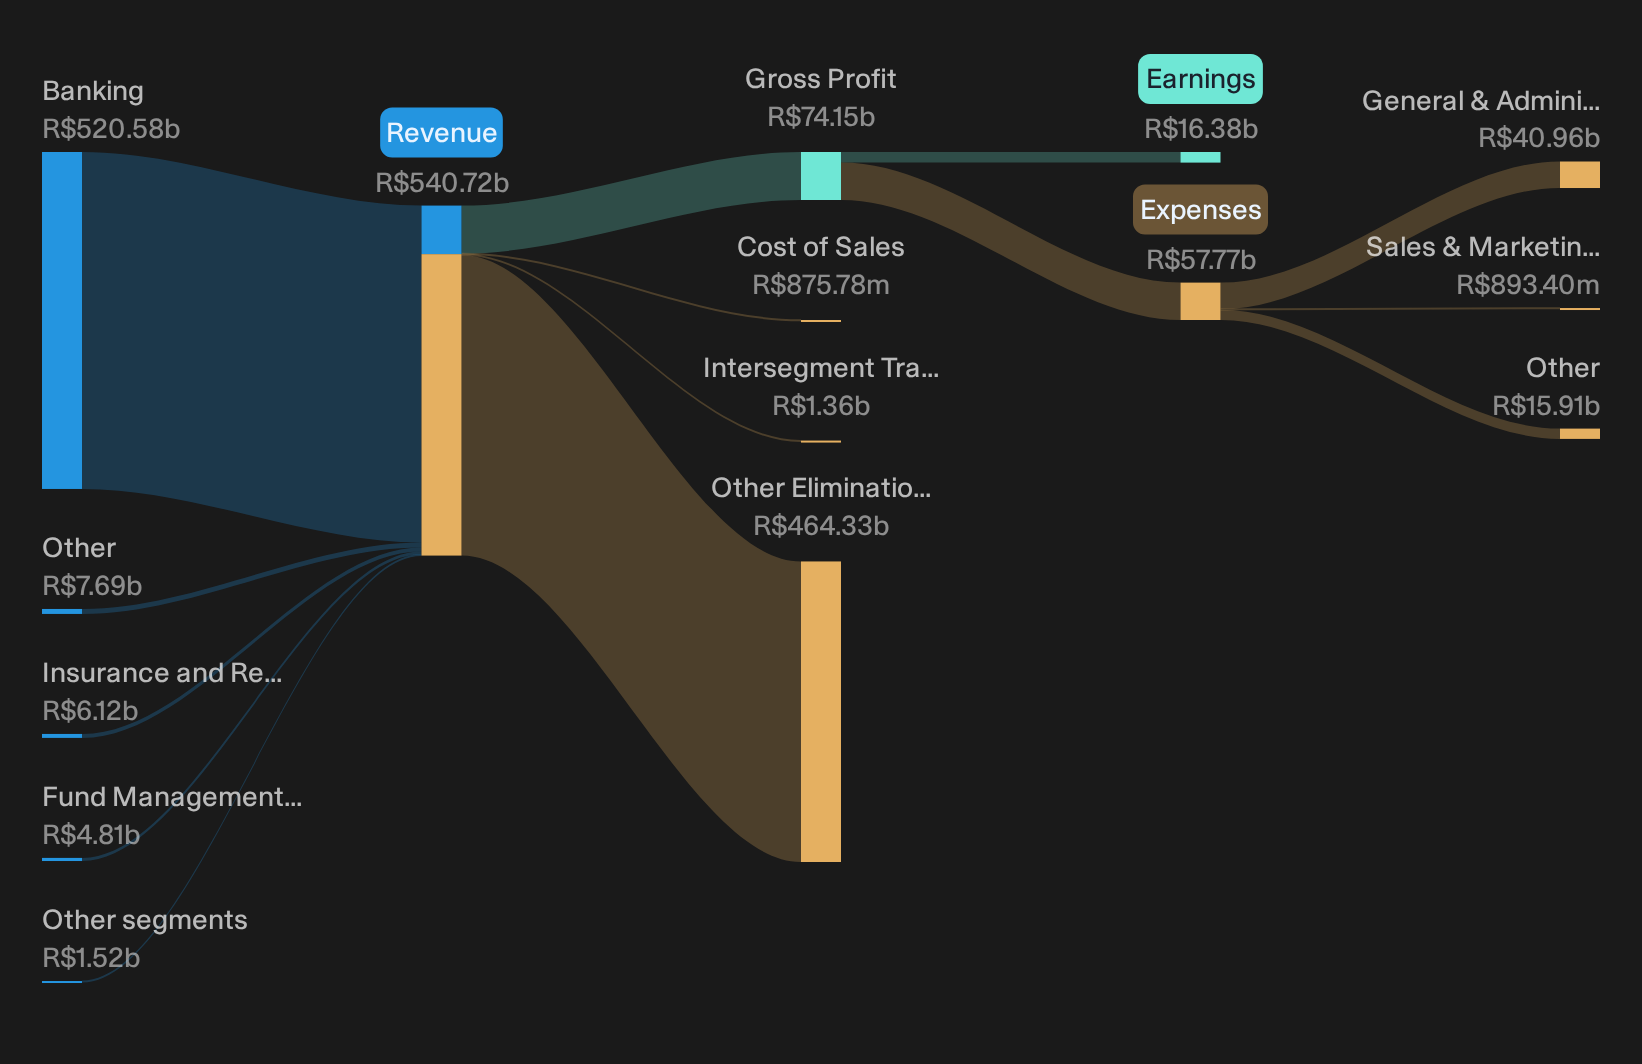
Operations: Banco do Brasil generates roughly R$520.6b from Banking, with smaller contributions from Insurance, Other activities, Fund Management, Investments and Electronic Payments, mostly in Brazil.
Market Cap: R$94.0b
Banco do Brasil sits right in the middle of Brazil’s credit intermediation system, so shifts in interest rates and household finances show up quickly in its loan book and fee income. This is exactly what recent results and analyst debates are trying to unpack.
"Although Banco do Brasil is reallocating growth toward secured payroll and collateral-backed SME lending, the recent spike in credit card and short term individual NPLs linked to household over indebtedness and a mis designed automatic installment feature suggests unsecured retail risk may keep pressuring cost of risk and net margins beyond what current loan mix plans imply."
What happens when one quiet change in how credit is priced and funded starts to bite will matter a lot for Banco do Brasil’s margins.
That inflection point is exactly what the full narrative for Banco do Brasil unpacks, separating short term credit pain from where Banco do Brasil’s earnings power could quietly be rebuilding.
Banco da Amazônia (BOVESPA:BAZA3)
Overview: Banco da Amazônia is a regional lender focused on the Brazilian Amazon, providing banking, credit and insurance solutions for households and businesses.
Operations: Banco da Amazônia generates about R$3.3b in banking revenue, entirely from activities within Brazil.
Market Cap: R$3.6b
Banco da Amazônia is closely linked to Brazilian interest rate and credit conditions, with a regional loan book that helped produce R$997.49 million in net interest income in H1 2026. However, it has a high 10.1% bad loan ratio and a 91% loss allowance, which keeps risk elevated if pressure on funding costs and credit spreads changes direction.
With that risk cushion in mind, review the 1 key reward and 5 important warning signs to see how Banco da Amazônia’s credit profile could evolve if conditions start to ease.
Seeking Alternatives Before Momentum Flies
Fresh opportunities can move from quiet to crowded fast. Before the next breakout gets caught by the crowd and early entry points start dropping away, act now.
- Target dependable cash flows and steady compounding by scanning a curated 220 dividend fortresses that could help you stay invested while markets keep swinging.
- Ride structural shifts in energy and infrastructure by checking a focused group of 16 nuclear energy infrastructure stocks that many investors still overlook.
- Track the picks and shovels of AI growth by reviewing a filtered set of 53 AI infrastructure stocks built to power the next leg of computing demand.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com