
How Investors Are Reacting To Huntsman (HUN) Stronger Q3 Sales And Margins
- Huntsman reported Q3 2026 sales of US$1.72b and a net loss of US$18 million, with adjusted EBITDA reaching US$132 million on higher volumes, stronger margins, and cost savings.
- Advanced Materials and Polyurethanes delivered segment revenue that exceeded analyst expectations, signaling that Huntsman’s shift toward higher value specialty products is gaining operational traction even while headline earnings remain weak.
- The focus now is on how Huntsman’s stronger volumes and improved margins in Q3 may reshape the existing investment narrative around its portfolio shift.
Compare how Huntsman’s Q3 shift toward higher value materials stacks up against peers by reviewing a curated list of 34 high quality undervalued stocks that may be pricing in similar portfolio transitions.
Huntsman Investment Narrative Recap
To own Huntsman, you need to be comfortable with a chemicals group that is still loss making, but leaning harder into higher value materials and cost discipline. Q3 2026 showed that story in miniature. Sales reached US$1.72b while the business still reported a net loss of US$18 million, and adjusted EBITDA of US$132 million relied on better volumes, pricing, and savings.
The near term swing factor is whether these mix and efficiency gains can offset soft demand and competitive pressure in polyurethanes, especially in Europe, without straining the balance sheet further. The biggest risk remains prolonged weak end markets and overcapacity that keep pricing under pressure, which this quarter’s progress helps but does not remove.
The most relevant recent development alongside the earnings print is Huntsman’s planned merger with Olin, which has cleared key shareholder and regulatory hurdles and is expected to close in the first quarter of 2027. For you as a holder, that puts execution risk squarely on how well two complex chemicals portfolios are combined while existing integration and restructuring work is still ongoing.
This potential tie up could reshape the earnings mix, cost base, and exposure to cyclical products, so it sits close to the same catalysts investors are watching today in Advanced Materials and Polyurethanes. The Q3 improvements in adjusted EBITDA and segment performance give a snapshot of what better product mix and cost control look like, but the merged entity would need to carry that through a larger, more complicated platform to justify the extra complexity and leverage.
Huntsman's current analyst storyline points to revenues of US$6.7b and earnings of US$98.0 million by 2029. That path assumes revenue growth of 4.3% per year and an earnings swing of US$266.0 million, from earnings today of a US$168.0 million loss to the projected 2029 profit.
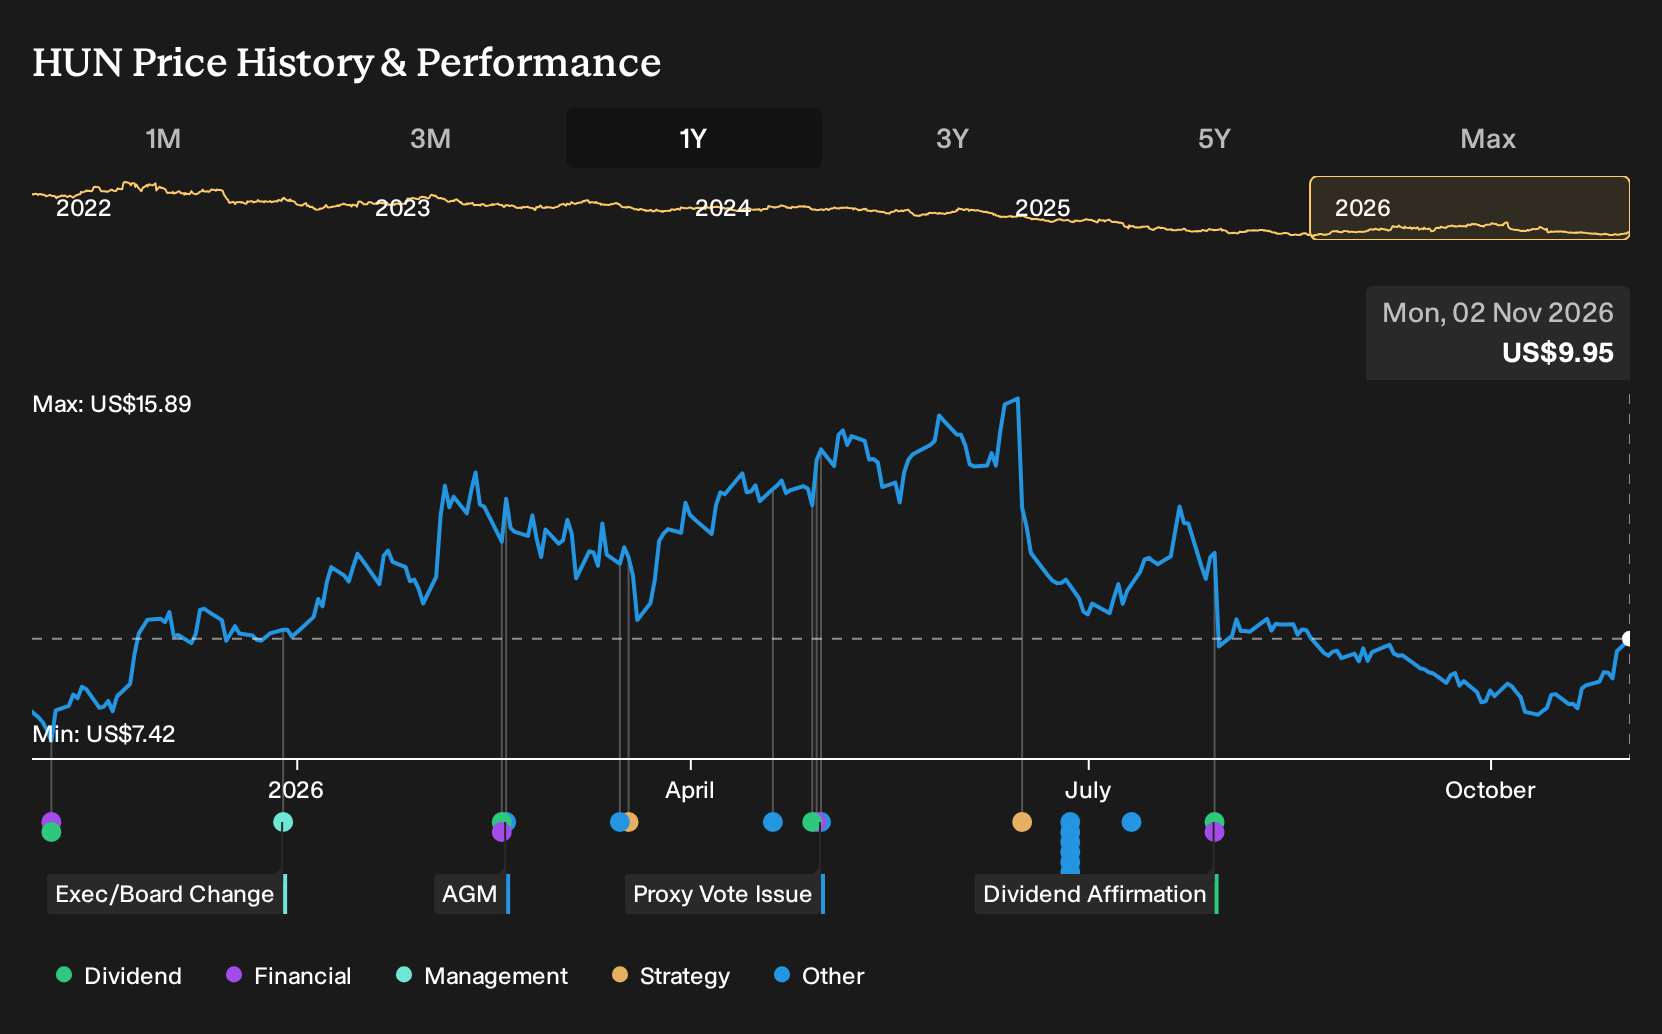
Uncover why Huntsman's fair value indicates a 9% potential upside to its current price before the discount appears to be closing.
Exploring Other Perspectives
For Huntsman, the bullish twist in the story is all about the Olin merger. The most optimistic analysts were already penciling in revenues of about US$7.1b and earnings of US$118.2 million by 2029, before this Q3 update. You can now ask whether these pre news merger and cost synergy assumptions still feel conservative, aggressive, or somewhere in between.
Explore 4 other Huntsman fair value estimates, including one that suggests potential upside of as much as 35% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Huntsman research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Huntsman. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Huntsman's overall financial health at a glance.
Looking For More Investment Ideas Beyond Huntsman?
If Huntsman has helped sharpen your view on cyclical chemicals and portfolio transitions, it can be useful to widen the lens and see how other businesses line up on quality, balance sheet strength, and income potential. The Simply Wall St Screener lets you apply those filters directly so you are not relying only on headline stories.
- For investors who care most about resilience, start with companies that combine steadier fundamentals and lower overall risk by reviewing the 29 resilient stocks with low risk scores.
- If dependable income matters to you, scan for businesses with higher yields that are backed by solid fundamentals through the 4 dividend fortresses.
- To round out your watchlist with less crowded opportunities, look for companies that pair strong financial quality with lower market attention using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com