
After the AI deal was liquidated, Ackman bolstered the growth potential of cloud computing giants: Wall Street overestimated AI infrastructure costs and underestimated the AI profit curve
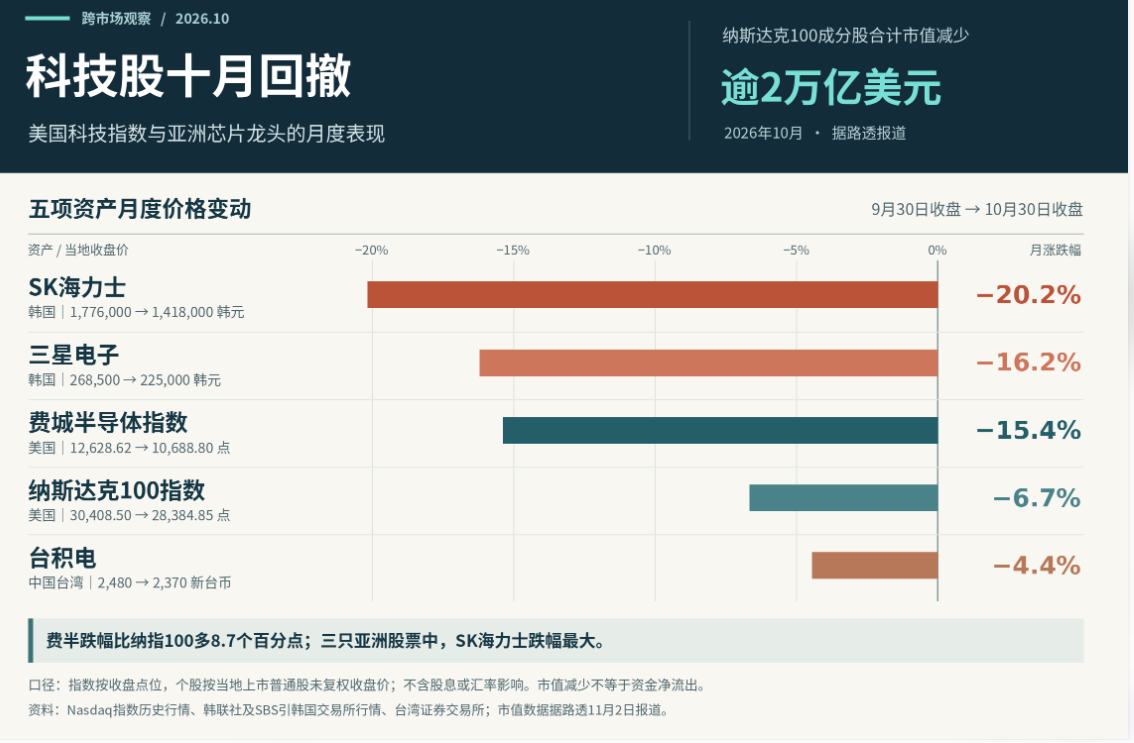
The total market value of the Nasdaq 100 Index, which has the title of a “global technology stock weather vane”, evaporated on a large scale last month by more than $2 trillion as investors re-evaluate AI-related infrastructure investments that may not be able to recoup comprehensive costs and AI-driven economic growth expectations. At a time when global technology stocks are plummeting, the latest shareholder letter to shareholders of Pershing Square Inc. (PS.US), founded by billionaire and hedge fund legend Bill Ackman, shows that Wall Street hedge funds seem to pay too much attention to rising AI computing power infrastructure construction costs and associated AI financing costs, significantly underestimating the future long-term growth potential of large technology companies that invest heavily in artificial intelligence.
The Zhitong Finance App learned that Ackman's latest opinion is basically the same as that of Wall Street strategists who have turned to a bargain buying position when technology stocks have recently plummeted. For example, Gerry Fowler, chief strategist and derivatives director of the European stock market from UBS Group, said in an interview on Monday that the market underestimates the AI supercycle, 2027 may reach an inflection point; according to this strategist, after the recent decline in AI transactions, the valuations of hyperscale cloud computing service providers seem attractive because of the AI reflected in the market's latest pessimistic pricing A supercycle, which appears to last less time than is actually likely to last.
Deutsche Bank has switched back to the theme of bullish technology stocks in the US stock market, focusing on adjusted prices; Mike Wilson, the chief stock strategist from Morgan Stanley, continues to be optimistic about the rebound after risk release, focusing on excessive pricing and absorption paths for AI financing cost pressure, midterm elections, and liquidity pressure. Another Wall Street financial giant Goldman Sachs is based on signals such as S&P 500, NASDAQ 100, US stock options, and hedge fund positions and capital flows in the US market, focusing on the long-term bullish narrative of US technology stocks and AI-related stocks.
According to a recent stock market research report released by Deutsche Bank, the agency suddenly turned bullish on US technology stocks, completely reversing the cautious decision to downgrade the entire US technology sector to “neutral” three weeks ago. The agency's team of strategists said that drastic sell-offs have created attractive buying opportunities, and quite a few of the risks associated with artificial intelligence are already reflected in the price.
Deutsche Bank strategists said that the relative performance of technology stocks has fallen to the bottom of the long-term range. In recent years, this level has marked an attractive time to enter the market. Deutsche Bank's exclusive statistics show that when capital was re-rotated to technology stocks, the sector rose sharply by an average of about 32%, and the performance was about 30 percentage points higher than the rest of the S&P 500 index.
Despite steady long-term profit growth expectations in the US stock technology sector, the overall stock position is still relatively light; the Deutsche Bank strategist team said that if the profits of these technology companies linked to AI remain resilient, investors still have plenty of room to increase their exposure, so Deutsche Bank strategists raised US technology stocks and global technology stocks from “neutral (neutral)” to the most optimistic long-term bullish rating of “increase in holdings.”
Bill Ackman: Wall Street “punishes hyperscale cloud vendors” for construction costs, ignoring their growth potential
Bill Ackman's Pershing Plaza Company mentioned in a letter to shareholders that Wall Street hedge funds underestimate the long-term potential of large technology companies that invest heavily in artificial intelligence, focus too much on rising infrastructure costs, and ignore future revenue growth, stronger cash flow, and return on investment. The investment firm also saw investment opportunities in the broader stock market.
Prior to Tuesday's arrival, Pershing Plaza shares rose more than 2% in overnight trading. Pershing Plaza pointed out in a letter to shareholders in the third quarter that the S&P 500 index rose slightly more than 2% in the third quarter, but the median rise and fall of constituent stocks fell 4%. More than 60% of the constituent stocks closed down during the quarter. As of September 30, the S&P 500 index rose 13% during the year, but the average increase in constituent stocks was only 1%.
Meanwhile, based on changes in earnings expectations per share of S&P 500 companies, the median rose 4% in the quarter, with a cumulative increase of nearly 10% over the first nine months of this year. Pershing Plaza said that this divergence has created buying opportunities: some cloud computing companies and big tech giants that focus on building AI computing power resources have improved their fundamentals, yet their stock prices are still weakening.
Pershing Plaza, founded and headed by Ackman, said in a letter to shareholders that semiconductor and technology hardware vendors have significantly benefited from AI-related expenses. Since this year, the S&P 500 semiconductor index has risen sharply by 44%, and the technology hardware index has risen 36%. However, Wall Street is “punishing hyperscale data center operators” for construction costs while ignoring their strong growth potential.
“Infrastructure construction linked to AI computing power has always been one of the main drivers of stock market performance this year. Among them, companies that provide 'pickaxes and shovels' are the biggest beneficiaries.”
However, large cloud computing and technology companies, including Microsoft (MSFT.US), Facebook's parent company Meta Platforms (META.US), Amazon (AMZN.US), and Google's parent company Alphabet (GOOGL.US), the average share price rose by only 8% despite a 27% increase in profit, which is a sharp decline compared to the semiconductor index.
“The decline in price-earnings ratios of hyperscale cloud vendors is mainly due to investors' concerns about how high returns they can get from a significant increase in capital expenditure.” Pershing Plaza wrote in a letter to shareholders.
Why are hyperscale cloud computing vendors expected to get higher returns from AI investments in Ackman?
Pershing Plaza believes investors are ignoring the long-term benefits of large-scale AI infrastructure spending. The combined capital expenditure of the big four tech companies in 2026 is likely to reach $740 billion, up from $140 billion in 2023. Wall Street analysts agree that this figure will surpass $1 trillion in 2027.
“We believe the capital expenditure of hyperscale cloud vendors is offensive rather than defensive. We believe they are not only investing to protect existing core businesses, but also to accelerate growth and invest capital in a transformative technology that directly leverages their competitive advantage. ”
“These benefits include unrivaled distribution capabilities, long-standing customer relationships, proprietary data and contextual information associated with it, the ability to provide secure and reliable services globally, and strong balance sheet strength. This financial strength allows them to invest on a scale few competitors can attain.”
Pershing Plaza said that Amazon's investment in AI is driving the accelerated growth of AWS, and the business's revenue increased 39% in the third quarter. AI is also improving the accuracy of ad targeting, helping Meta accelerate revenue growth. Meta's Muse Assistant surpassed 10 million downloads in just a few weeks, bringing new opportunities to generate revenue through shopping, services, and business tools. AI is also creating growth opportunities through Azure, Microsoft 365 CoPilot, and GitHub.
Some analysts expect that large technology companies will still invest heavily in AI infrastructure in the next few years, yet they don't think that the revenue growth rate of these companies will accelerate significantly this year and next two years. Pershing Plaza believes that analysts view these expenses as a continuing cost and are not fully aware that they have the potential to drive significant future revenue and profit growth.
“In our opinion, analysts have fully factored in the current construction costs of hyperscale cloud vendors in their predictions, so these companies are 'penalized'; however, they are very limited in their expectations for future long-term growth in terms of significant future revenue and profit growth or even a new round of revalued exponential growth that these investments are likely to bring.”
Pershing Plaza said revenue growth in 2026 was largely due to AI investments made in 2024 and 2025. As a result, the company anticipates that higher current spending will drive stronger growth over the next few years, and performance may significantly exceed analysts' unanimous predictions.
Ackman is betting on three major cloud computing platforms: the market sees this year's bill, but underestimates next year's business
In October, the Nasdaq 100 index fell by about 6.7%, and the Philadelphia Semiconductor Index fell by about 15.4%. In addition, the total market value of the NASDAQ 100 index evaporated on a large scale last month by more than $2 trillion; in addition, last month (that is, October), chip stocks critical to AI computing power infrastructure in the South Korean stock market also experienced a rare large-scale sell-off, especially in the Korean stock market, SK Hynix fell 20.2% — the third-largest monthly decline in nearly a decade.
Ackman's judgment at this point is that one end of the same AI capital expenditure has become revenue for chip and equipment vendors, but the other end will not become revenue from the cloud platform until the computer room is powered up and the customer uses computing power; if analysts immediately raise their spending forecasts but do not assess how much business the additional production capacity can bring, they may systematically underestimate the future profit growth trajectory of the party investing in construction.
At a time when Ackman gave a positive outlook and layout for the cloud computing and technology sector, at a time when global demand for AI computing power continued to grow at a blowout, but the sky-level capital requirements brought about by the procurement of trillion-dollar AI computing power resources and investment in AI infrastructure, combined with AI financing costs for AI new cloud companies such as Coreweave surged and the two major supercloud giants with stable fundamentals for a long time — Google's parent company Alphabet and Amazon's AI-related debt is rising at the same time, it is also driving the market to re-examine AI-related technology companies The cash recovery cycle associated with heavy AI financing costs and huge investment in AI infrastructure.
Demand for AI computing power is still actively expanding, but the ability of enterprises to turn demand into delivery, profit, and free cash flow is becoming the basis for market repricing. The stock price of Google's parent company Alphabet had a record sharp collapse of nearly 13% as of last Thursday, and the stock price of the US CPU and chip manufacturing giant Intel hit the worst single-day decline in more than 40 years until the close of last Friday. It can be said that they all occurred at a time when the cash return on AI investment was being scrutinized more strictly.
Ackman himself can be described as using his positions to express this positive bullish judgment. In an interview published on October 28, he said that Amazon, Meta, and Microsoft together account for about one-third of their investment portfolio. The background of the three purchases is different: Amazon bought after Trump announced the “Liberation Day” tariffs; Meta and Microsoft bought when capital expenditure promises caused market disappointment. This is a disclosure of his existing positions and the reason for the purchase, but there is currently no actual evidence that he added three positions at the same time during the decline at the end of October. On November 2, Ackman and Chief Investment Officer Ryan Israel highlighted the new position layout in a shareholder letter — seven new investments have been made as of the third quarter of this year, and the eighth unspecified position will be established after the quarter.
A bullish research report on the topic of AI computing power and technology released by Nomura Securities on November 2 can be described as actively revealing the potential economic logic behind Ackman's deal — negative free cash flow may come from pre-construction payments and revenue instalments. The time difference between the two cannot be directly identified as a huge loss.
Pershing Plaza quoted Amazon management's explanation: Data center builders need to invest about two years in advance and can be used for more than 30 years after operation; servers and network equipment can be purchased several months before operation, which is closer to customer needs. According to Amazon's estimates, the server payback is slightly less than three years, and the service life is at least five to six years. In the third quarter, AWS revenue increased 39% to US$46 billion, with an operating margin of 38.7%; Google Cloud's revenue increased 103% to US$30.7 billion, and the operating margin rose from 23.7% to 36.2%; and Azure revenue increased 48%. Overall, however, these latest digital dynamics support that computing power demand is being monetized, yet the overall profit margin of the cloud business cannot replace the return rate of a single new construction project. Determining whether the cloud computing giants were “mistakenly killed” in this round of technology stock sell-off depends on whether the utilization rate and fees can allow the project to recoup investment and cover capital costs before the equipment is upgraded after the new computing power is put into operation.
Deutsche Bank resumes “gaining holdings”, Damo awaits buying points: Wall Street is looking for opportunities to bottom out
The “invisible bear market” of the US stock market in October can be described as a sharp rotation of the industry. According to The Kobeissi Letter's combined punch line, AI-related stocks in the US stock market fell by more than 13% in the same month. Excluding AI, the S&P constituent stock portfolio rose by about 8% and reached a new high on October 30.
On October 30, Deutsche Bank restored US technology stocks from “neutral” to “increased holdings”: in the past three weeks, technology and ultra-large capitalization growth stocks fell by about 11%, while the remaining S&P constituents rose nearly 6%. The difference in performance between the two was more than 16 percentage points. Deutsche Bank's basis is that the relative performance of technology stocks is close to the lower end of the long-term range, while profits are still growing. When capital was redirected back to technology stocks in previous rounds, the sector rose by an average of about 32%; however, this is a historical reference given by Deutsche Bank and is not the target for this round of growth.
Morgan Stanley's Mike Wilson is optimistic about the market after uncertainty has subsided. Whichever party wins the midterm elections, he favors the dips, but keeps the S&P 500 path of exploring 7,100 points first, waiting for election results, AI financing pressure, and the liquidity situation to clear before recovering to 8,000 points. Goldman Sachs derivatives strategist Brian Garrett provided a transaction-level test: the net leverage ratio of the US Fundamental Long and Short Fund fell to 47%, at the 7th percentile in the past year; although the fund made a net purchase of US stocks for the first time in four weeks, about 73% of purchases came from macroeconomic products, and it was mainly short recovery. The positions of the three institutions each have their own focus: Deutsche Bank has raised its allocation. Wilson believes that further decline will improve buying points. Goldman Sachs sees room for retail investors and institutional investors to re-increase their positions recently, but the evidence of continued and active purchases of technology stocks is still limited.
The Deutsche Bank strategist team saw an opportunity to reallocate technology stocks amid pessimistic pricing in the market. The agency pointed out that technology and hypercapitalization growth stocks have fallen by about 11% in the past three weeks, while the remaining S&P 500 constituents have risen by nearly 6%. The former has outperformed by more than 16 percentage points and has fallen back to the bottom of the long-term relative performance range. For technology stocks, the most significant change in investment is a significant adjustment in the price relationship between technology stocks and other sectors: the premiums investors were previously willing to pay for AI growth were quickly compressed, and safe-haven rotation also boosted the relative prices of other assets. As a result, Deutsche Bank believes that quite a few AI-related risks have already been overpriced by the market.
In a major media interview on November 1, EST, Wilson further clarified his judgment on long-term bullish US stocks, especially technology stocks linked to AI: midterm elections, AI investment and financing disputes, and liquidity constraints may still constitute three types of events driving the market downward for a short time; however, after these pressures are concentrated and released, they may instead create opportunities for investors to re-establish stock risk exposure. He believes that the S&P 500 may fall back to 7,100 points, down about 9% from the recent all-time high, and then accelerate its recovery to 8,000 points.
Statistics from Goldman Sachs, another Wall Street financial giant, show that the net leverage ratio of US fundamental long and short funds fell to 47%, at the 7th percentile over the past year; in historical regression, such positions are usually accompanied by an index retreat of more than 20%, while currently the S&P 500 is only down about 3% from near the historical high. To a large extent, this also means that most institutional investors have reduced risk to a considerable extent ahead of schedule. Once profits remain resilient and the impact of the incident is mitigated, the room for re-allocation may become a driving force for a rebound. 