
Impinj (PI) Looks Fully Valued As Earnings Beat And Guidance Shift The Story
Impinj earnings beat and fresh guidance shift investor focus
Impinj (PI) just posted third quarter 2026 results that topped revenue expectations, moved from a loss to a profit, and arrived alongside fresh fourth quarter guidance that kept attention on RFID demand.
The trigger was straightforward. Sales for the quarter were US$112.08 million, up from US$96.06 million a year earlier, while net income reached US$4.68 million after a net loss of US$12.81 million in the prior year period.
That swing to profitability came with basic and diluted earnings per share of US$0.15, compared with a basic and diluted loss per share of US$0.44 twelve months before.
For the first nine months of 2026, Impinj recorded revenue of US$294.7 million versus US$268.23 million in the same stretch of 2025, with the business still reporting a net loss of US$8.36 million.
Loss per share for those nine months was US$0.27 basic and diluted, compared with a loss per share of US$0.33 a year earlier, which points to gradual improvement but not a fully profitable year yet.
Management framed the quarter around what it described as solid demand for its RFID endpoint ICs and broad interest across retail and supply chain logistics, while also calling out early progress in its software pipeline.
Beta deployments for that software are expected to begin soon according to the company summary, and Impinj linked that effort to a plan for ongoing capacity investment and a goal of stronger margins as specialty IC revenue returns.
Alongside the third quarter report, Impinj issued new guidance for the fourth quarter ending 31 December 2026, forecasting revenue between US$104.0 million and US$107.0 million.
The firm also projected GAAP net income in a range of US$1.2 million to US$2.7 million for the period, with diluted GAAP earnings per share guided to US$0.04 to US$0.08.
Those figures give investors a clearer view of how management currently sees demand trends and profitability into year end, without implying any outcome beyond the ranges that were set.
Impinj shares traded at US$186.07 at the last close, with a 1-day share price return of 3.57% and a 7-day share price gain of 6.44%. The 90-day share price return of 13.88% and a 3-year total shareholder return of about 17x suggest momentum has been strong over a longer stretch, even though the 30-day share price return slipped 1.87% and the year-to-date gain of 3.51% has been more muted.
Scan how Impinj compares with other fast-moving chip and connectivity plays by checking the hand-picked 53 AI infrastructure stocks that are capturing investor attention after earnings shifts like this.
Impinj just shifted from losses to a quarterly profit while the share price has already surged over several years. Are you seeing the market catch up to business progress, or a swing in sentiment that valuation will need to justify next?
Most Popular Narrative: 6% Undervalued
Impinj closed at US$186.07, while the most followed narrative pegs fair value at US$199. This leaves only a modest valuation gap and puts the emphasis firmly on execution against its RFID roadmap.
Expanding deployment of RFID solutions for food traceability and freshness, especially at the item level with three of the five largest U.S. grocers now running pilots or deployments in bakery, deli and meats, supports the view that Impinj can extend endpoint IC demand beyond apparel into a much larger addressable market and drive future revenue growth.
Broadening adoption of RFID enabled supply chain and logistics solutions, with all time high endpoint IC bookings across apparel, general merchandise and logistics customers, points to further rollouts across multiyear programs that can support growth in tag volumes and more recurring product revenue.
See why 18 investors see Impinj as 6% undervalued.
Result: Fair Value of $199 (UNDERVALUED)
Still, Impinj’s story leans heavily on continued RFID demand and cleaner logistics visibility, so any renewed order volatility or sentiment shift on valuation could quickly test this view that the shares are 6% undervalued.
Find out about the key risks to this Impinj narrative.
Another View on Impinj valuation
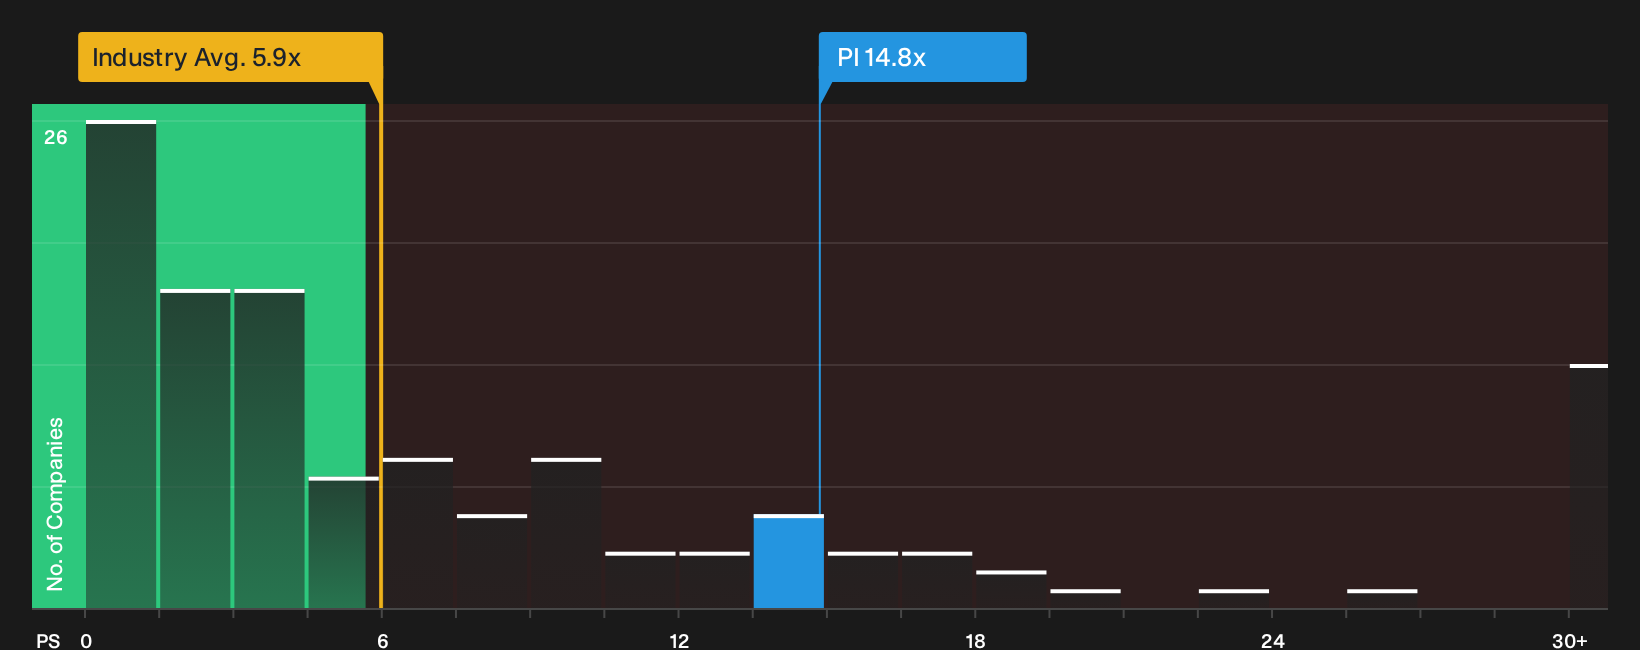
The story looks different when you stop thinking in terms of fair value and focus on what the market is paying for each dollar of Impinj revenue. The stock trades on a P/S ratio of 14.8x, while the US Semiconductor industry sits at 5.9x and direct peers average 5.2x.
The fair ratio for Impinj is 5.3x, which means the current multiple is almost three times what the market could move toward if sentiment cools. That gap can look like upside already priced in rather than headroom that still needs to be filled in by execution and RFID demand. How comfortable are you with paying that kind of premium for this narrative?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The article leans toward cautious optimism around Impinj, yet the real test is how you read the numbers and risk markers for yourself. Take a closer look at the balance of potential upside and trade offs by reviewing the 2 key rewards.
Looking for more investment ideas beyond Impinj?
If Impinj has sharpened your thinking about pricing power and execution risk, do not stop here. Broader opportunities often sit just outside the stocks already on your radar.
- Target resilient compounding by scanning a curated 34 high quality undervalued stocks that combines quality fundamentals with prices that have not already run away.
- Prioritise sleep at night holdings by working through a 29 resilient stocks with low risk scores designed to highlight businesses with sturdier financial profiles and calmer trading histories.
- Hunt for tomorrow's potential standouts by browsing a 19 high quality undiscovered gems that focuses on strong fundamentals before wider attention arrives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com