
What Waste Management Stock's Earnings Beat Means For Shareholders
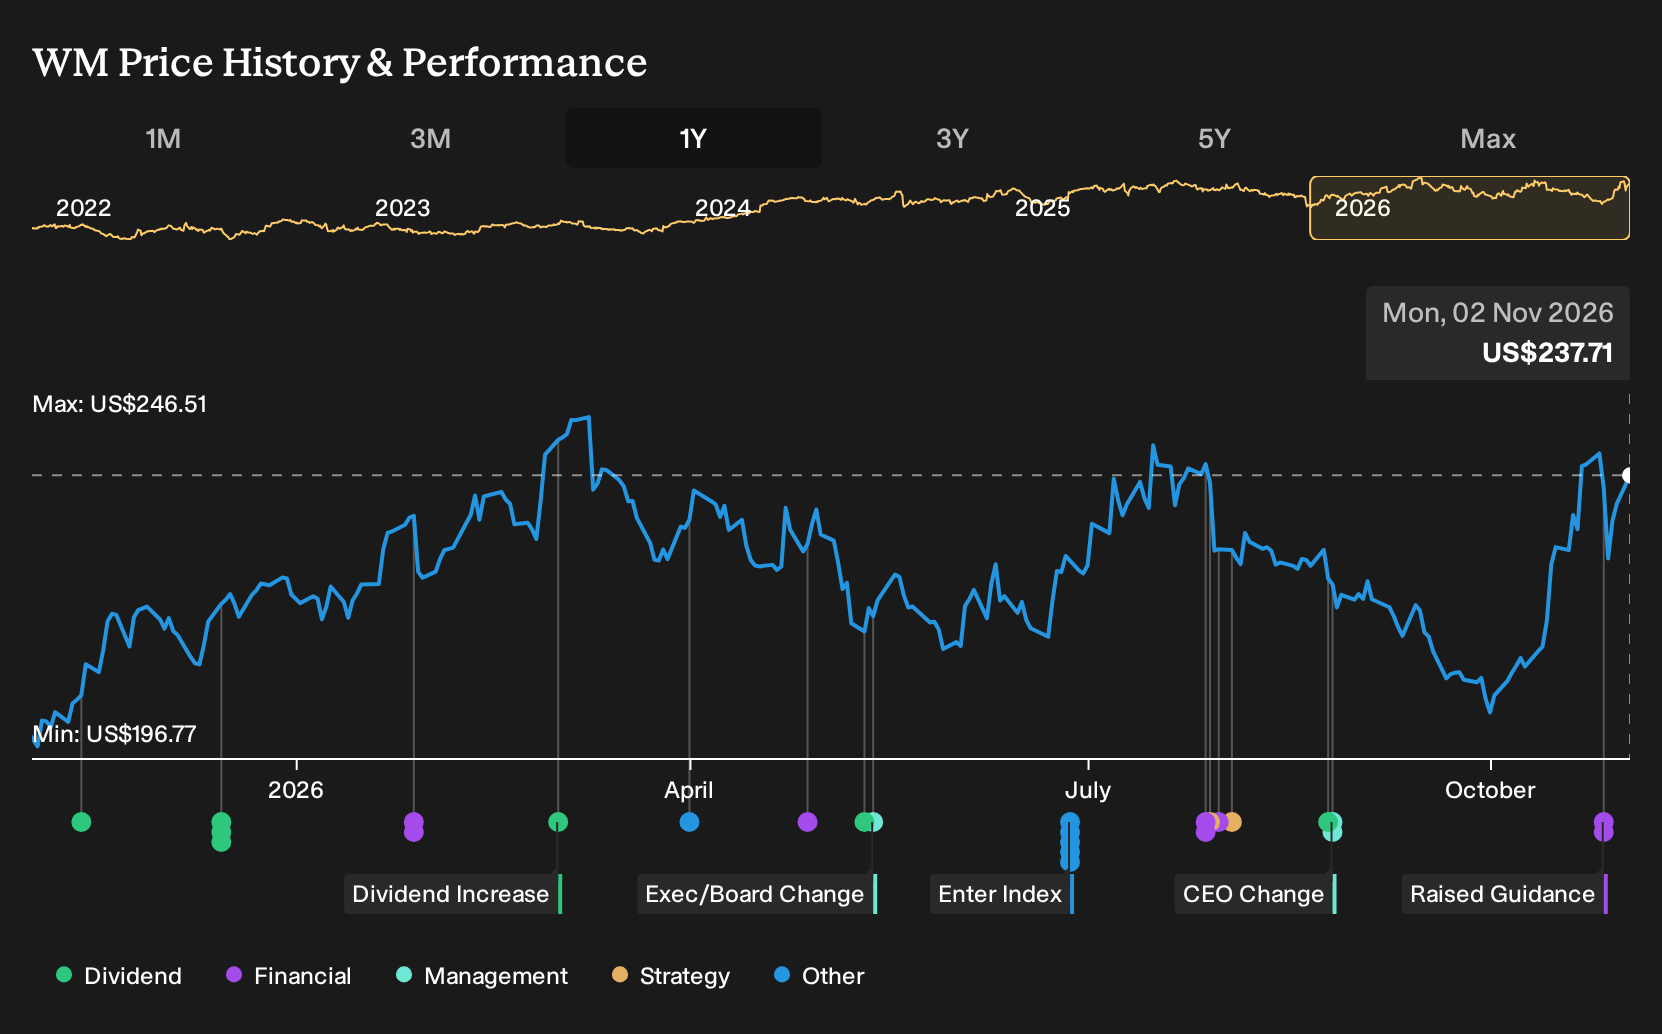
- Waste Management reported Q3 2026 results with US$6.846b in sales, US$820m in net income, and basic EPS from continuing operations of US$2.06, and also issued full year 2026 revenue guidance indicating revenue at the high end of the US$26.275b to US$26.475b range.
- Execution on pricing, technology driven cost control, healthcare growth and share repurchases, including US$580m spent on 2,588,442 shares in Q3, illustrates how Waste Management is relying on both operations and capital allocation to support earnings per share.
- We will look at how Waste Management's raised full year revenue outlook shapes the investment narrative built around margin expansion.
Compare Waste Management’s margin profile with other operators by exploring a hand picked set of list of solid balance sheet and fundamentals (24 results) that could handle tougher conditions without stressing their finances.
Waste Management Investment Narrative Recap
To own Waste Management, you need to believe the business can keep turning pricing power, automation and higher value services like healthcare and renewable energy into a sturdier margin structure. The Q3 report, with US$6.846b in sales and US$820m in net income, reinforces that the current operating playbook is working through a mix of pricing and cost control.
The near term swing factor is whether pricing and efficiency gains can keep offsetting softer volumes in parts of collection and industrial activity. The biggest risk is that volume pressure or a tougher backdrop for tax credits and fuel costs erodes that margin progress faster than healthcare and recycling synergies can support it.
The most relevant update for that thesis is management’s guidance that 2026 revenue is expected to land at the high end of US$26.275b to US$26.475b. For a Waste Management shareholder, that guidance ties directly to the margin story because it effectively underlines confidence in pricing discipline and in the contribution from healthcare solutions and recycling automation.
That said, revenue guidance alone does not reduce the key risks. The renewable natural gas buildout still depends on supportive tax policy and pricing, and Stericycle integration and healthcare synergies need to track against expectations to justify the capital already deployed. Your view on the stock hinges on whether that execution can continue alongside a high but actively managed debt load.
What The Analyst Scenario Implies For Waste Management
Waste Management's analyst narrative ties directly back to the margin story investors are watching. Forecasts assume revenue expands at 5.5% per year, with profit margins moving from 11.1% today to 13.6% in three years as healthcare solutions, recycling automation and renewable natural gas plants scale into the income statement. Under that framework, current earnings of US$2.9b are projected to reach US$4.1b by 2029, an increase of about US$1.2b that analysts link to both higher pricing and richer mix from newer services.
Waste Management's narrative projects US$30.1b revenue and US$4.1b earnings by 2029. This requires 5.5% yearly revenue growth and an earnings increase of about US$1.2b from US$2.9b today.
Those assumptions sit behind the current broker price targets. To line up with that view, you would need to be comfortable with Waste Management earning US$4.1b on US$30.1b of revenue in 2029 and trading on a P/E of 29.9x, compared with 30.2x implied today and 18.8x for the wider US Commercial Services peer group. That set up still bakes in a premium multiple, which puts more weight on execution around healthcare synergies, renewable fuel profitability and the steady 0.78% annual reduction in share count analysts are modelling through buybacks.
Uncover why Waste Management's fair value indicates a 7% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Fair value estimates for Waste Management from 2 Simply Wall St Community members cluster tightly between about US$251.81 and US$253.84, which points to very similar assumptions rather than a wide spread of opinions. Those views do not yet reflect Q3 earnings, raised revenue guidance or the potential impact of fuel tax credits and Stericycle synergies. You should treat this as one slice of sentiment and explore more community viewpoints before forming a stance.
Explore another Waste Management fair value estimate, including one that suggests it could be worth just $251.81.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Waste Management research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Waste Management. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Waste Management's overall financial health at a glance.
Looking For More Investment Ideas Beyond Waste Management?
If Waste Management has helped sharpen your thinking about pricing power, balance sheets and earnings quality, use that momentum to widen your opportunity set with a few targeted screeners on Simply Wall St.
- If you want potential mispriced opportunities with solid fundamentals, start by scanning a 34 high quality undervalued stocks that already filter for quality.
- For readers who care most about income resilience, focus on companies in the 4 dividend fortresses and see which payouts look better supported by cash flows.
- When capital preservation sits near the top of your checklist, concentrate on businesses from the 29 resilient stocks with low risk scores that score well on financial strength and volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com