
Is Reinsurance Group Of America (RGA) Stock Near Fair Value?
Reinsurance Group of America has put in a strong run in recent years, which naturally raises a simple question for anyone looking at the ticker today. Is the current share price at US$267.41 still aligned with what its earnings can reasonably support?
- Over the past 5 years the stock has returned 161.3%, which puts a lot of weight on whether its earnings story has kept pace with the share price.
- As a reinsurer that depends heavily on disciplined underwriting and investment income, the company’s ability to convert premiums into durable profit streams can shape how much investors are willing to pay for each dollar of earnings.
- There is a second opinion on Reinsurance Group of America worth weighing. See what analysts think Reinsurance Group of America's shares could be worth.
The issue now is whether Reinsurance Group of America’s recent share price performance, including a 49.9% return over the last year, is justified by the level and quality of its earnings.
If you want to pressure test whether Reinsurance Group of America’s earnings story justifies its price across a wider set of opportunities, compare it with 34 high quality undervalued stocks.
Where Does Reinsurance Group of America Sit on Earnings?
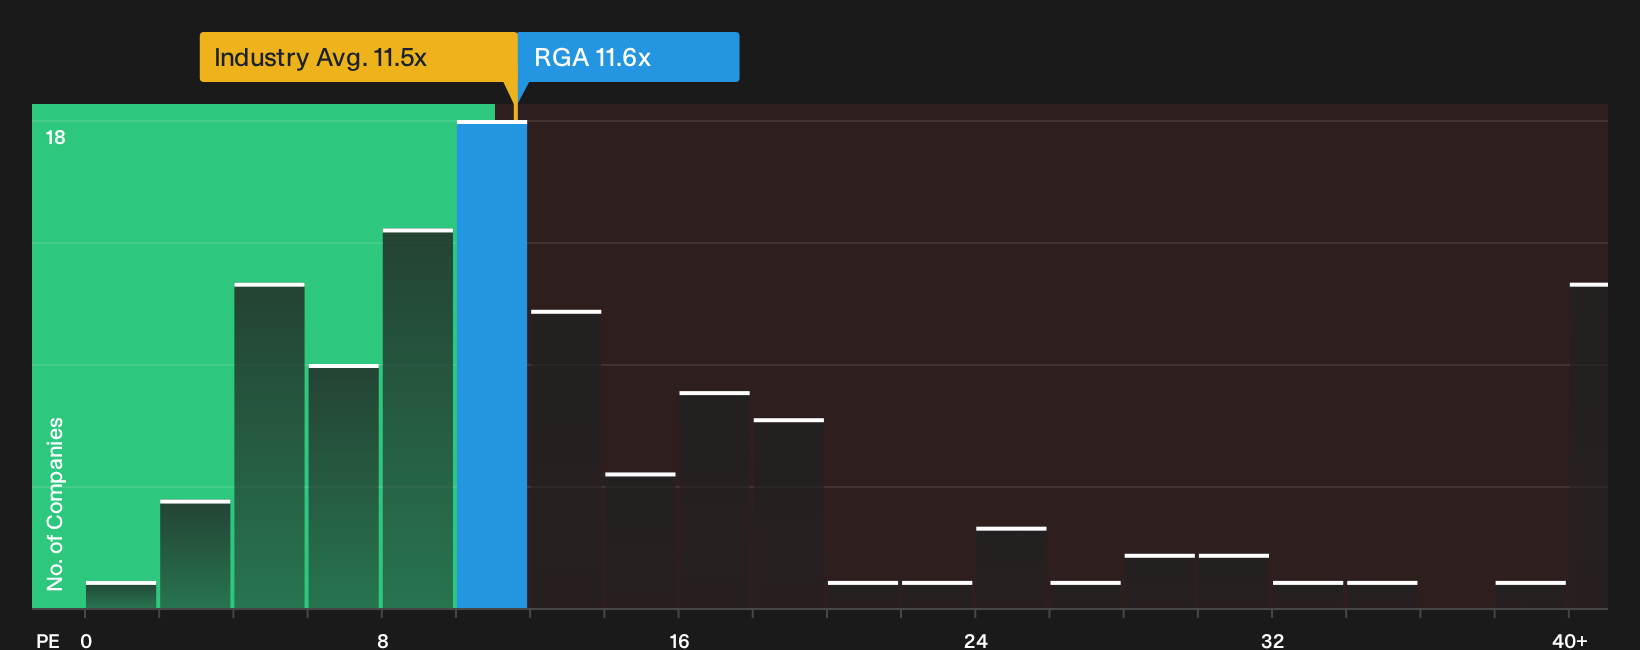
P/E is a useful lens for Reinsurance Group of America because earnings are a central yardstick for an insurer that monetises both underwriting and invested capital. On that metric, the shares trade on a P/E of 11.6x, which is very close to the broader Insurance industry average of 11.5x. Against a peer set on about 8.4x, investors are paying a higher price per dollar of earnings than for many comparable reinsurers.
The fair multiple suggested by a more tailored model that folds in Reinsurance Group of America’s forecast returns on equity, book value profile and risk markers points to a level not far from where the stock trades today. That keeps the P/E signal finely balanced and places more emphasis on how comfortable you are with the quality and stability of those earnings streams over time. Explore the numbers behind Reinsurance Group of America's P/E valuation.
The Reinsurance Group of America Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take Reinsurance Group of America’s valuation puzzle one step further and spell out what kind of future earnings, margins and balance sheet outcomes would need to hold for the stock to be worth materially more or materially less than today’s price on the Community page. Each scenario is framed as a thesis about Reinsurance Group of America's business that can be tracked over time rather than a single frozen estimate.
Community views on Reinsurance Group of America are split between those who see more upside in its biometric and capital story and those who think pension risk transfer headwinds already cap the valuation.
Bull case: roughly fairly valued
"Rising life and health insurance penetration combined with Reinsurance Group of America’s focus on biometric-heavy reinsurance and favorable mortality experience, including economic claims running US$375 million better than expectations since 2023, supports the view that long-run biometric earnings power and return on equity can benefit from these structural demand and risk trends…"
Discover why this Narrative puts Reinsurance Group of America at roughly fairly valued.
Bear case: 14% overvalued
"While Reinsurance Group of America continues to emphasize biometric risk expertise and favorable mortality experience as a support for long term earnings, a sustained slowdown in U.S. and U.K. pension risk transfer activity at roughly half of recent industry volumes could leave this capability underutilized and create a drag on revenue and earnings where large pension deals were expected to contribute…"
Explore why this Narrative puts Reinsurance Group of America at 14% overvalued.
Reinsurance Group of America’s price is only one side of the picture
Before you anchor too firmly on where Reinsurance Group of America trades today, it is worth checking the specific risk flags our research has picked up and weighing how they fit with your own thesis. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com