
Legend Holdings (SEHK:3396) On Low P E Scrutiny, Is The Pullback A Buying Opportunity
Legend Holdings (SEHK:3396) is back in focus after recent commentary highlighted that its P/E is well below the sector average, directing attention to whether current earnings quality justifies the valuation that investors now observe.
Recent trading has been volatile for Legend Holdings, with the share price up 2.18% over the last day but down 41.33% over the past 30 days. At the same time, the year-to-date share price return of 57.14% and a 3-year total shareholder return of 98.34% point to longer term momentum that is now being reassessed in light of its low P/E and the ongoing debate over earnings quality.
Compare Legend Holdings with a curated set of value ideas by scanning the 192 high quality undervalued stocks, which may also pair low P/E ratios with solid fundamentals.
After a sharp 30 day pullback following a strong multi year run, Legend Holdings now combines a low P/E with newly questioned earnings quality. Does that mix still tip the risk reward balance toward buyers?
Price-to-Earnings of 10.9x: Is it justified for Legend Holdings?
On a P/E of 10.9x against a last close of HK$14.08, Legend Holdings screens as inexpensive relative to both its own earnings profile and peers that trade on far richer valuations.
The P/E ratio compares what you pay per share to the earnings that the business produces per share. For a diversified group like Legend Holdings, which spans technology hardware, banking, agriculture, and other assets, that single number effectively blends several different profit streams into one market verdict on earnings quality.
Legend Holdings is flagged as good value when compared with similar companies and the broader Tech sector, where the peer average multiples sit at 67.2x and 17.3x respectively. Relative to the estimated fair P/E of 56.9x from the SWS model, the current 10.9x reading suggests the market is assigning a far lower earnings multiple than the regression based level it could move toward if sentiment on its earnings profile improved.
Explore the SWS fair ratio for Legend Holdings.
Result: Price-to-Earnings of 10.9x (UNDERVALUED)
Still, the complexity of Legend Holdings, with exposure to banking, agriculture and early stage investments, leaves plenty of room for earnings swings and shifting asset values.
Find out about the key risks to this Legend Holdings narrative.
Another View: What the SWS DCF Model Says About Legend Holdings
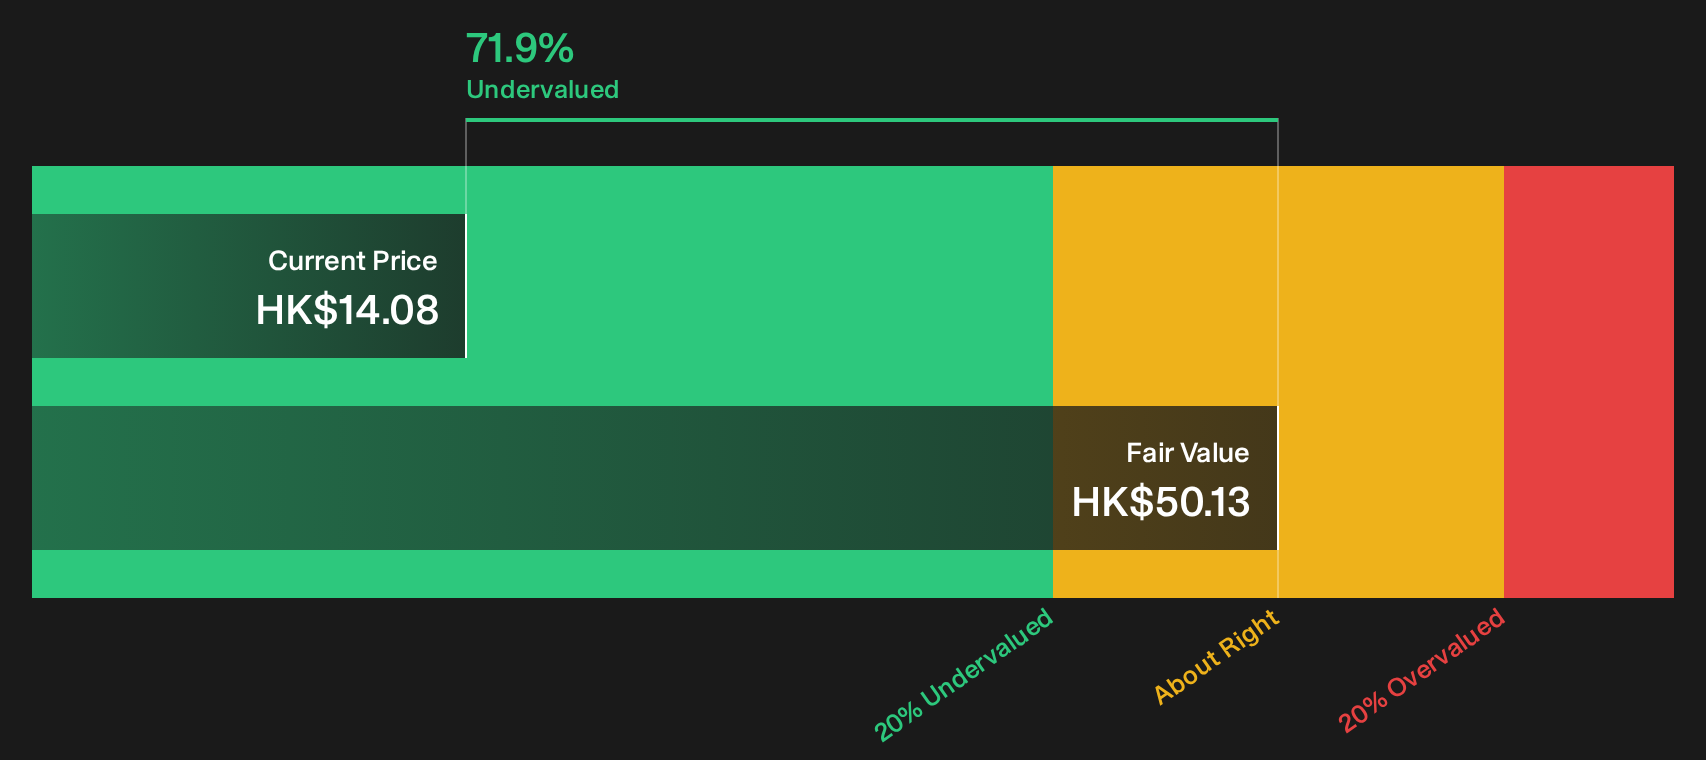
The SWS DCF model points in the same direction as the low P/E. At HK$14.08, Legend Holdings appears to be trading below an estimated future cash flow value of HK$50.13. This indicates a very large gap between the share price and that cash flow-based estimate.
That kind of discount can look appealing on paper, yet it also requires a high level of confidence in long-range cash flow assumptions and a willingness to look past recent volatility. The key question is whether that wide spread reflects opportunity, or whether it is the market’s way of pricing in real business and balance sheet risks.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Legend Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Legend Holdings can tempt you to lean hard in one direction, so move quickly, review the numbers, and decide where you land by weighing its 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Legend Holdings?
If you only stop at Legend Holdings, you risk missing other opportunities that might suit your risk profile or income goals even better.
- Target potential mispricings by scanning the 192 high quality undervalued stocks that blend attractive valuations with solid underlying businesses.
- Build a steadier income stream by reviewing the 223 dividend fortresses that focus on companies with higher yields.
- Guard your capital by checking the 217 resilient stocks with low risk scores that highlight businesses with more resilient risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com