
What L.B. Foster Holders Saw Early
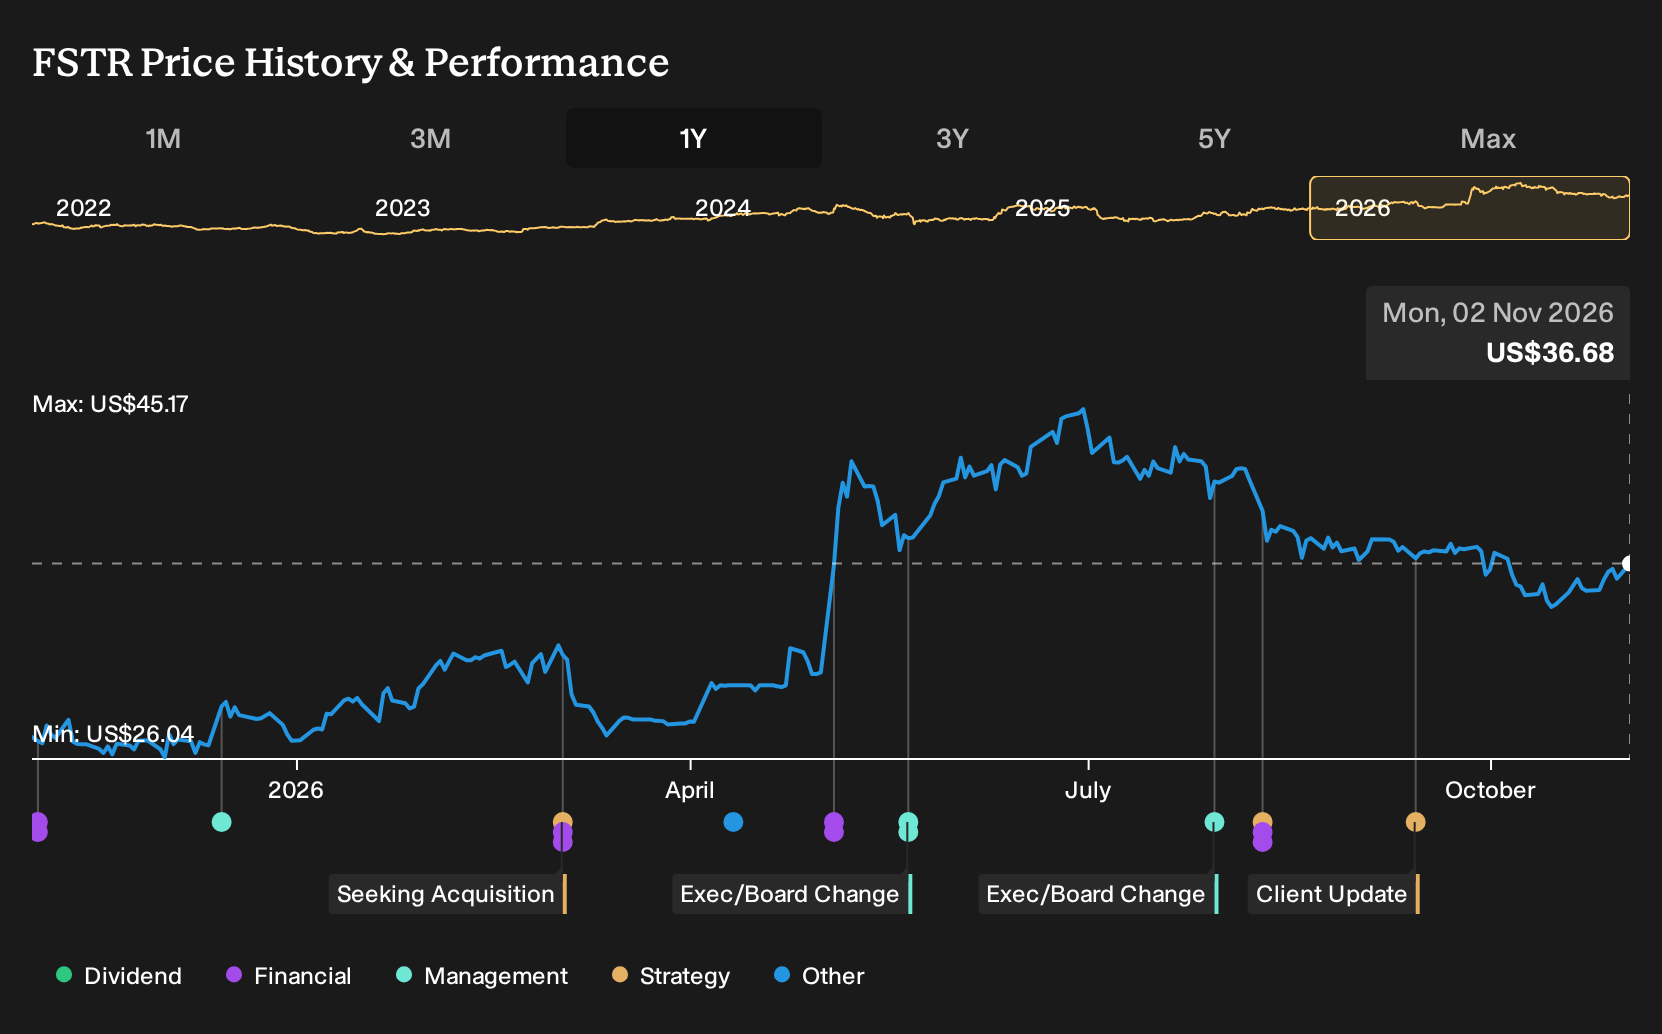
Envirocast wall systems were not a headline product for most investors, yet for L.B. Foster they sat at the center of a push into higher-margin precast concrete backed by government-funded infrastructure work. Investors who held L.B. Foster over the past year are up 36.2%, including dividends. If you were weighing a purchase on 2 November 2025, what would you have needed to believe about that backlog, those new facilities, and rail funding risk to act?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
L.B. Foster has already moved. See which of 34 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing Up On L.B. Foster
The shares cost US$27.33 at the start of the period, so any thesis on L.B. Foster had to explain why that upfront outlay made sense against the funding and rail uncertainties already visible.
The bullish Narrative put Fair Value at US$29, anchored on government infrastructure money keeping Precast Concrete and Rail backlogs healthy, while new Envirocast equipped facilities gained traction.
The bearish case set Fair Value at US$25 and focused on the risk that delayed or weaker public funding for rail projects would keep that segment under pressure and cap margin progress.
What The Results Changed For The L.B. Foster Thesis
L.B. Foster then reported Q2 2026 revenue of US$138.55m versus US$143.56m a year earlier, while net income rose to US$3.11m and net margin edged up to 2.2% from 2.0%. That combination supported the cautious case that focused on funding and rail risk keeping a lid on top-line progress, even as margin work showed some traction. Overall, the evidence cut both ways.
The lesson is that when a story hinges on better backlog quality and pricing, you test it by watching net margin, not just sales, and you track that against any revenue softness quarter by quarter.
What L.B. Foster's Run Now Asks You To Believe
Today L.B. Foster trades at US$36.68, and the selected Narrative places its Fair Value above that level rather than below it.
The argument leans on mix shift toward higher margin rail technologies, precast concrete, and coatings, and on the idea that current pricing still underplays recent cash generation and balance sheet repair.
"The main factor that has to go right is successful execution of the portfolio reshaping and U.K. restructuring so that exits and one time charges translate into the targeted cost savings and a cleaner, higher return business. The current valuation implies the market is not fully pricing in the company’s recent free cash flow generation, lower leverage, and share repurchases, which together support the view that L.B. Foster is undervalued."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking One Step Beyond L.B. Foster
L.B. Foster is tied to physical projects you can see. It is concrete, rail, coatings, real world assets.
Step one layer away and attention lands on data centers. Those facilities face a different bottleneck, keeping dense computing hardware powered and cool enough to run.
A separate specialist handles that problem by designing gear that manages power flows and removes heat. The focus is on keeping racks online while limiting waste, including water.
As more workloads push into those halls, that behind the scenes infrastructure role could matter more than the servers most people watch.
One Narrative has already put a figure on it. → Uncover the company trading 45% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com