
Palomar Holdings (PLMR) Gains On Diversification Narrative, Is The Upside Already Priced In?
Palomar Holdings (PLMR) has drawn fresh attention after its recent share move, with the price closing at $145.02. Investors are weighing that shift against the insurer’s growth profile and return history.
The recent 1 month share price return of 14.65% and 1 day move of 3.35% fit into a broader pattern for Palomar Holdings, where momentum has been positive over both shorter and longer horizons. That near term strength sits alongside a 1 year total shareholder return of 27.97% and a 3 year total shareholder return of about 16x, which signals that investors have been reassessing both the company’s growth prospects and its risk profile over time.
Scan beyond Palomar Holdings and identify other insurers showing similar momentum by using the curated 29 resilient stocks with low risk scores.
After a run that lifted Palomar Holdings and pushed it closer to analyst targets, the debate now shifts: Is most of the easy upside already captured, or do the current valuation markers still leave meaningful room ahead?
Most Popular Narrative: 11% Undervalued
Palomar Holdings is being framed as undervalued in the prevailing thesis, with a fair value of about $163.17 versus the recent $145.02 close. This perspective places more weight on cash flow potential and capital returns than on simple headline multiples.
Deliberate diversification into crop, casualty, and surety, including the Gray Surety acquisition and rapid growth in crop and surety premiums, is shifting Palomar Holdings mix toward businesses that are less tied to traditional P&C cycles. This can support more stable revenue and earnings even as the loss ratio moves higher.
See why 27 investors see Palomar Holdings as 11% undervalued.
Result: Fair Value of $163.17 (UNDERVALUED)
Still, the Palomar Holdings story can be knocked off course if higher loss ratios from crop and casualty lines squeeze margins, or if earthquake pricing pressure persists.
Find out about the key risks to this Palomar Holdings narrative.
Another View: Palomar Holdings Through The P/E Lens
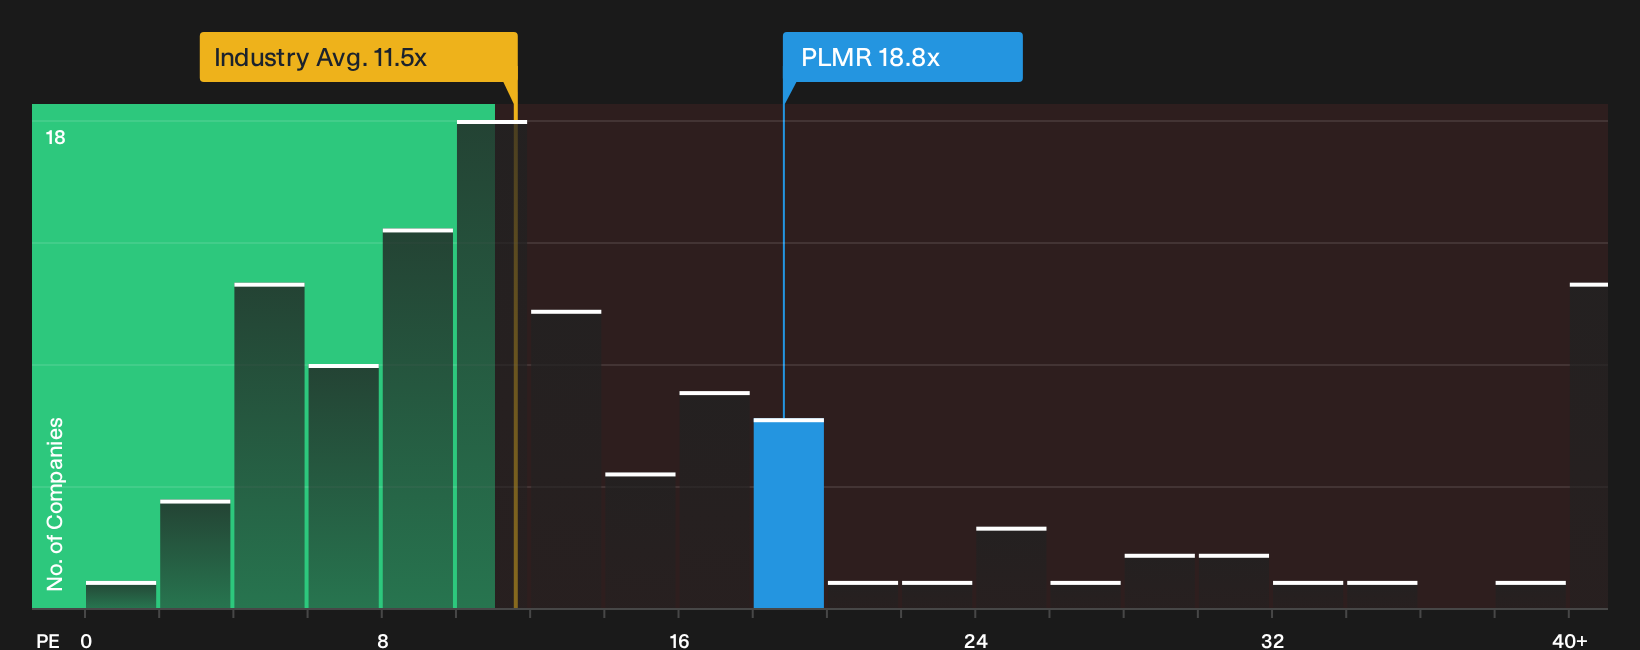
The story shifts once Palomar Holdings is viewed through its P/E ratio rather than cash flow models. The stock trades on 18.8x earnings while the US Insurance industry sits at 11.5x and peers at 8.8x, against a fair ratio of 14.3x that the market could move toward over time.
This gap points to valuation risk if sentiment cools or earnings stumble, even if the cash flow case looks appealing. The question for you is simple: Is this premium a quality signal or a margin of safety in reverse?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Palomar Holdings after reading all this. Act promptly by checking the full breakdown of risks and upsides so you can decide where you stand with the 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Palomar Holdings?
If Palomar Holdings has sharpened your focus, back it up by scouting fresh ideas with the Simply Wall St screener before the next move passes you by.
- Target overlooked potential by scanning a curated set of 19 high quality undiscovered gems that combine strong fundamentals with limited current attention.
- Strengthen portfolio resilience by zeroing in on a list of solid balance sheet and fundamentals (24 results) that can help support more durable business performance.
- Lock in clearer value propositions by filtering for a 34 high quality undervalued stocks that aligns with your return expectations and risk tolerance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com