
What Andersons Doubters Missed
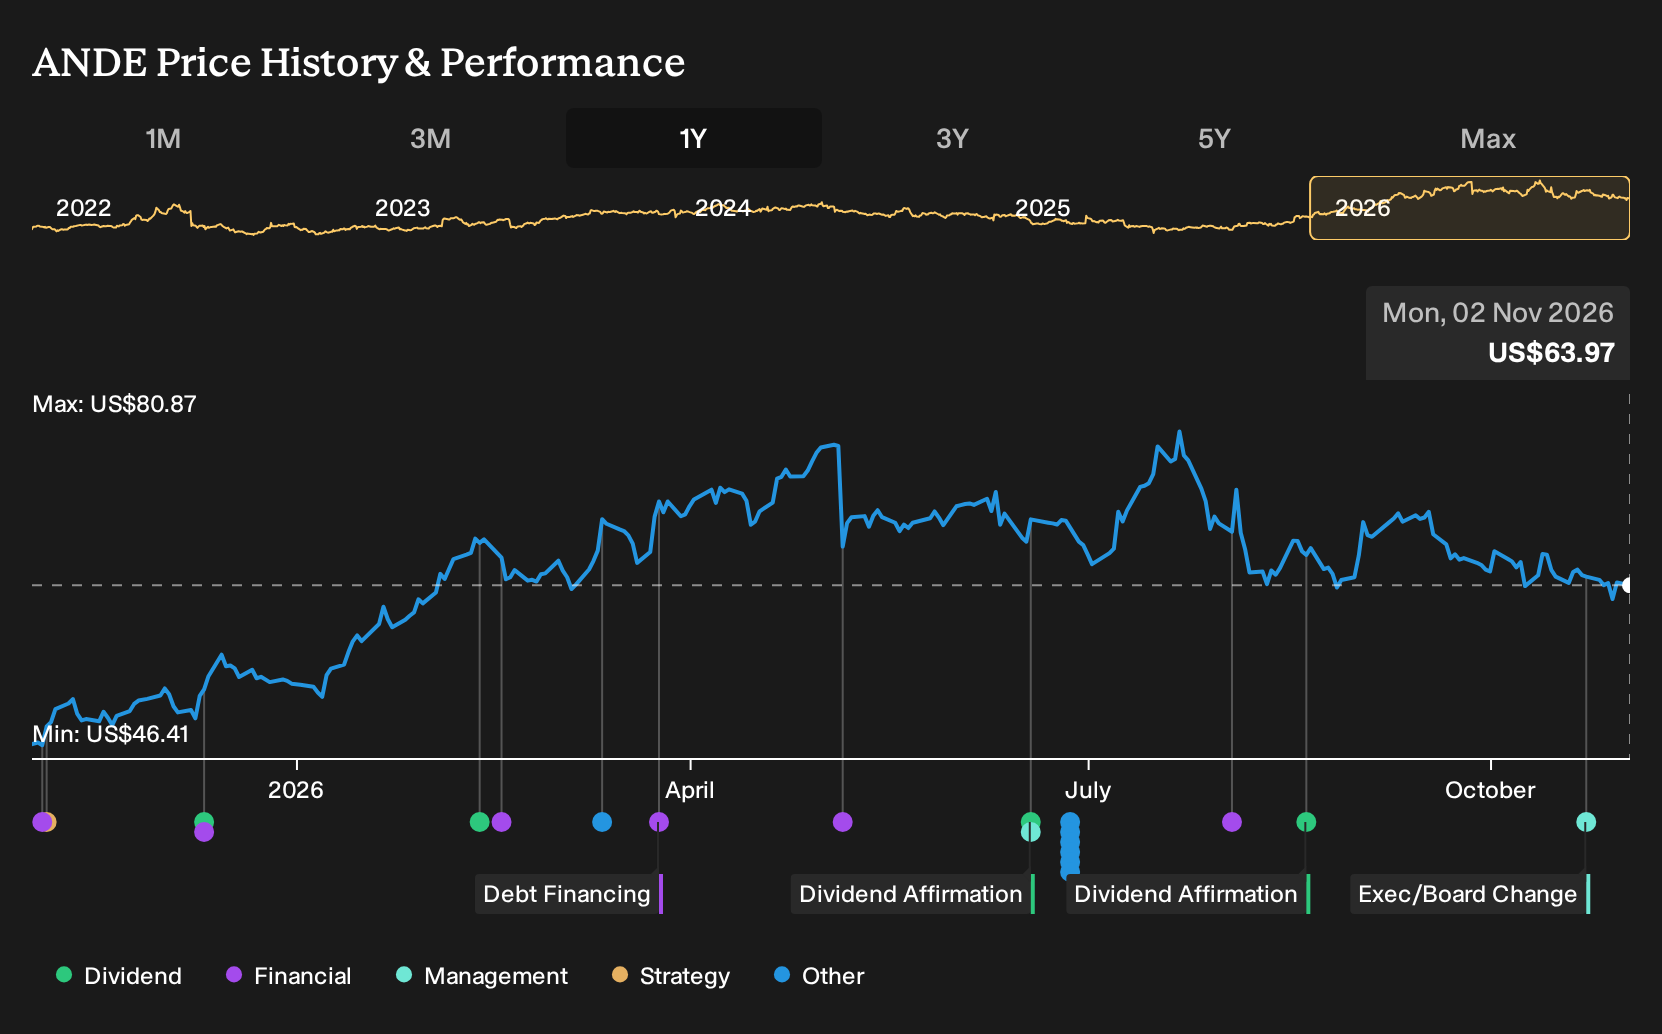
If Andersons sat on your watchlist instead of in your portfolio, the past year might feel like a lesson in hesitation. Holding Andersons over the past year would have returned 38.7%, including dividends. That outcome arrived as record quarterly profit, clean fuel tax credits and fresh analyst coverage landed in the news after your 2025 decision point. The real puzzle is this: could the bet on renewable fuels and agribusiness digitalization have been spotted clearly enough back in November 2025?
The move put Andersons in the middle of this trade. Scan 33 best rare earth metal stocks for other companies exposed to it.
The Argument You Would Have Had To Settle On Andersons
The shares cost US$46.25 at the start of the period, so any view on Andersons had to begin with whether that tag already captured the payoff from renewables and digital tools in grain handling.
The bullish narrative pointed to a Fair Value of US$55. This was a price level they felt reflected what their assumptions implied, built on ethanol plant acquisitions, full Skyland integration and heavier use of clean fuel tax credits in the Renewables segment.
The bearish side worked off a Fair Value of US$40, which their modelled value suggested. This view was anchored in climate volatility, high capital demands and the risk that faster digital competitors would compress merchandising margins over time.
What The Andersons Evidence Actually Tested
Record Q1 2026 profit, driven by Renewables and Agribusiness and helped by US$26 million of Section 45Z tax credits, leaned toward the bullish Andersons case that cleaner fuels and assets could lift earnings quality. Measured results added weight. Net income excluding extra items rose from US$7.9 million in Q2 2025 to US$56.6 million in Q2 2026, even though revenue slipped, and net margin moved from 0.3% to 1.8%. The period cut both ways but broadly backed the optimistic thesis on profitability.
The lesson travels. When a story leans on a tax credit and margin uplift, as Andersons did, track reported net margin and disclosed policy benefits together. That shows whether the business is building a sturdier earnings base or leaning more heavily on incentives that may not last.
What You Are Paying For In Andersons After A 39% Run
Today Andersons trades at US$63.97, after a 38.7% gain over the past year. The selected Narrative argues that its Fair Value sits above that level, tied less to plain ethanol volume and more to renewables income, grain processing projects and a balance sheet kept ready for further spending.
The focus sits on whether policy supported biofuels and premium ingredients can keep lifting earnings quality rather than just headline sales. A buyer today has to judge whether Andersons can keep executing on ethanol decarbonization and Section 45Z tax credit capture at something like the pace the Narrative assumes.
"Key Takeaways: Analysts expect Andersons to continue building on its renewables and agribusiness earnings, supported by policy-driven biofuel demand and ongoing investments in higher return grain and ingredients operations. The key requirement is continued execution on ethanol plant decarbonization, 45Z tax credit capture, and premium ingredients and export projects so that recent gains in adjusted EPS and segment profitability remain durable."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Andersons And A Different Kind Of Traffic
You focused on Andersons and tax credits. One step away sits a retailer wrestling with a different constraint.
Instead of ethanol plants and grain terminals, this business leans on store traffic and online clicks. It spends heavily on remodels, technology and price cuts to keep shoppers moving.
Those investments aim at a clear need. More people must visit more often and choose more profitable baskets when they do.
Here, AI tools, store expansions and same day fulfillment carry most of the load. The unresolved piece is how much of that ambition already sits in the current tag.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 20% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com