
Is Yangzijiang Shipbuilding (Holdings) (SGX:BS6) Undervalued On Its Maritime Ecosystem Shift?
Recent valuation work on Yangzijiang Shipbuilding (Holdings) (SGX:BS6) suggests the share price may sit below estimated intrinsic value, which puts fresh attention on its shift toward a broader maritime ecosystem model.
In the short term, Yangzijiang Shipbuilding (Holdings) has given back some ground with a 7.77% 30-day share price decline after a strong 34.20% year-to-date share price return, while the 5-year total shareholder return above 7x signals momentum built over a longer horizon around its broader maritime pivot.
Scan Yangzijiang Shipbuilding (Holdings) alongside a curated list of 192 high quality undervalued stocks that also trade below estimated intrinsic value based on Simply Wall St's models.
The recent pullback at Yangzijiang Shipbuilding, after a strong multi year climb, raises a simple tension between business progress and cooler sentiment. Do current cash flow estimates suggest the shares still look cheap on an intrinsic value basis?
Most Popular Narrative: 15.2% Undervalued
On the latest narrative work, Yangzijiang Shipbuilding (Holdings) is tagged with a fair value of SGD5.46 against a last close of SGD4.63. This puts fresh focus on how its wider maritime ecosystem ambitions feed into that gap.
The updated thesis is: Yangzijiang is deliberately transforming from a pure shipbuilder into a vertically integrated maritime ecosystem player, trading some valuation simplicity for greater earnings visibility, customer alignment, and long-term strategic optionality.
See why 15 investors see Yangzijiang Shipbuilding (Holdings) as 15% undervalued.
Result: Fair Value of SGD5.46 (UNDERVALUED)
Still, Yangzijiang Shipbuilding’s thesis could be challenged if shipbuilding demand weakens more sharply than expected, or if the Poseidon stake delivers weaker cash returns.
Find out about the key risks to this Yangzijiang Shipbuilding (Holdings) narrative.
Another View: What The P/E Ratio Says About Yangzijiang Shipbuilding
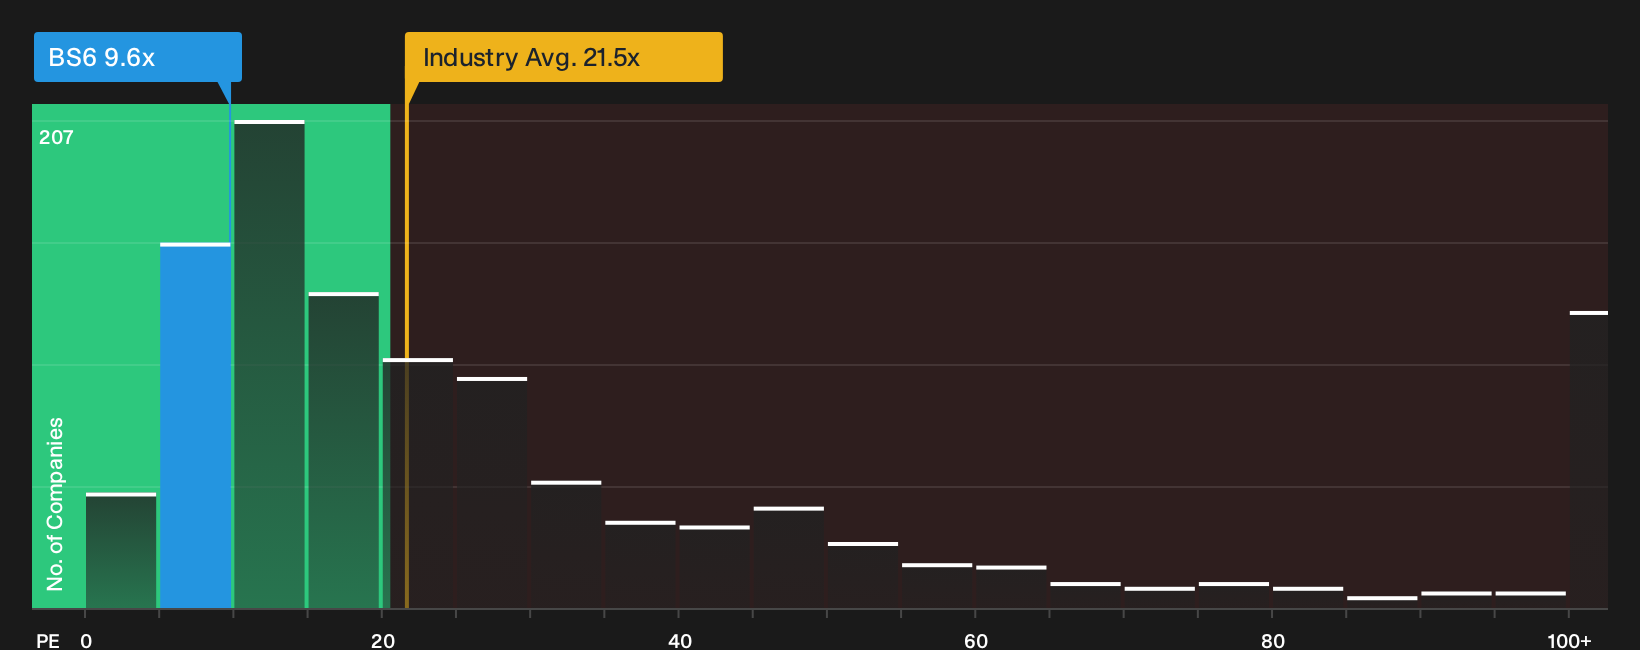
That SWS DCF fair value of SGD5.80 points one way, but the simple earnings multiple paints a more cautious picture. Yangzijiang Shipbuilding trades on a P/E of 9.6x, slightly richer than its closest peer set at 9.2x, yet well below the wider Asian Machinery group at 21.5x.
The fair ratio of 16.8x suggests the market could move significantly before valuations appear stretched. For investors, the key issue is whether that gap indicates additional upside potential or simply reflects the cyclical risks that consensus expectations already factor in.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around Yangzijiang Shipbuilding (Holdings) leave you undecided, move quickly and pressure test the numbers yourself against both the upside case and the risk side. To frame that debate with a structured view of the trade off, start with the 4 key rewards and 2 important warning signs.
Looking for more ideas beyond Yangzijiang Shipbuilding?
Do not stop at Yangzijiang Shipbuilding (Holdings). Use the screener to surface fresh ideas, compare potential setups, and keep your watchlist working harder for you.
- Zero in on value opportunities before the crowd by scanning a curated 192 high quality undervalued stocks filtered for both quality and pricing support.
- Build a sturdier core for your portfolio by focusing on a list of solid balance sheet and fundamentals (197 results) that can better handle tough conditions.
- Get ahead of the market by tracking a 603 high quality undiscovered gems that combine robust fundamentals with relatively low investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com