
Seibu Holdings (TSE:9024) On A 77% Fair Value Gap After Committee Appointment
Why Seibu Holdings Is Back On Investors’ Radar
Seibu Holdings (TSE:9024) has added veteran real estate executive Hitoshi Uemura to its Capital Allocation Review Committee, a move that puts fresh attention on how the group weighs key investment and portfolio choices.
Recent trading has reflected renewed interest in Seibu Holdings. The share price has climbed over the short term, with a 1 month share price return of 6.41% and a 3 month share price return of 12.88%. However, the year-to-date share price return is still down 13.38%, and the 1 year total shareholder return has fallen 29.71%. This comes after very large 3 year and 5 year total shareholder returns of 159.26% and 192.83%, which hints that investors are weighing earlier gains against current questions about capital deployment and risk.
Spot opportunities beyond Seibu Holdings by scanning a handpicked 74 high quality undiscovered gems that investors may not be watching yet.Recent gains and a year of weak returns leave Seibu Holdings looking like either a late cycle laggard or a reset entry point. To judge how much runway is left, the valuation work now matters most.
Price-to-Earnings of 22.7x: Is it justified?
On simple headline metrics, Seibu Holdings looks expensive. The shares last closed at ¥3,769, while the stock trades on a P/E of 22.7x compared with the JP Transportation industry at 11.8x and a peer average of 13.2x.
The P/E ratio compares the current share price to earnings per share. For a group like Seibu Holdings, with multiple segments across transport, hotels, and property, a higher P/E often signals that investors are willing to pay more today for each unit of current profit, usually because they expect steadier or higher earnings ahead compared with more cyclical peers.
Recent fundamentals give that premium a mixed backdrop. Earnings over the past year declined 83.5%, net profit margins tightened from 28.2% to 7.9%, and the 1 year total shareholder return fell 29.71%. Forecasts point to earnings growth of 9.04% per year and revenue growth of 4.3% per year, which is slower than the wider JP market expectations for both earnings at 9.4% and revenue at 6.4%. In other words, the market is paying a higher P/E for Seibu Holdings even though projected growth is not faster than the benchmark and return on equity is expected to remain low at 7.6%.
The premium also looks stretched when stacked against valuation anchors. The SWS estimated fair P/E ratio is 16.3x, well below the current 22.7x multiple. That gap is wide and suggests that if Seibu Holdings were priced closer to the fair ratio, the P/E could compress materially from here. Against both the industry average and this fair level, the current valuation points to investors already baking in a lot of optimism about earnings quality and longer term capital allocation improvements.
Explore the SWS fair ratio for Seibu Holdings.
Result: Price-to-Earnings of 22.7x (OVERVALUED)
Still, if Seibu Holdings disappoints on earnings after an 83.5% profit drop and return on equity remains near 7.6%, sentiment could fade quickly.
Find out about the key risks to this Seibu Holdings narrative.
Another View: What The SWS DCF Model Says About Seibu Holdings
The P/E points to Seibu Holdings looking expensive, and the SWS DCF model goes even further. On that cash flow view, an estimated value of ¥806.1 per share sits well below the current ¥3,769 price, which frames the stock as heavily overvalued on this method. If earnings or cash generation do not catch up, how patient will the market really be?
Look into how the SWS DCF model arrives at its fair value.
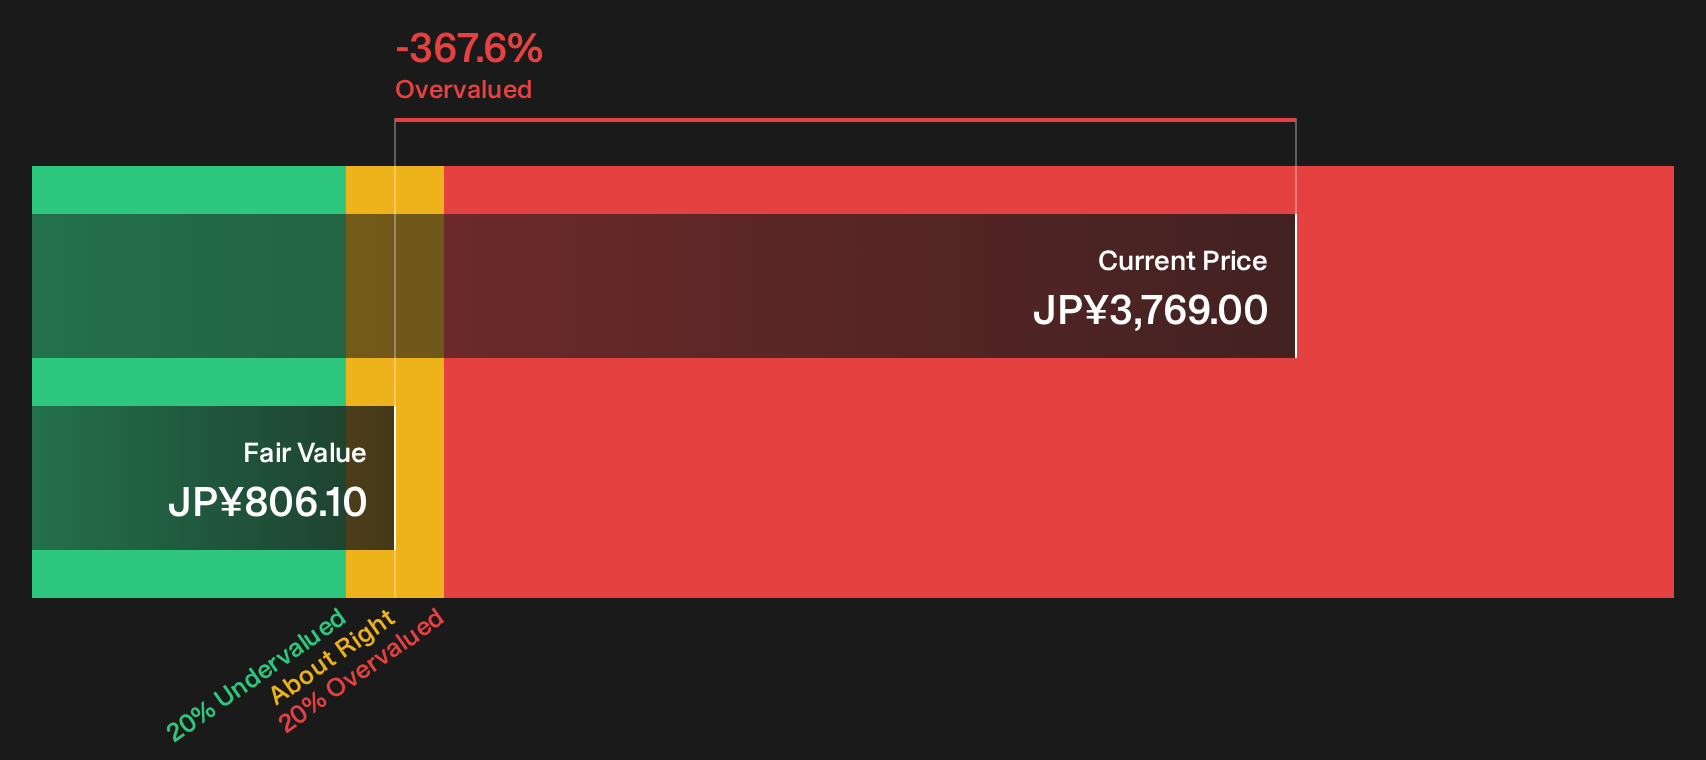
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Seibu Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Seibu Holdings so far. If the combination of richer multiples, flagged risks, and potential rewards leaves you on the fence, move quickly to look through the data, stress test your own assumptions, and weigh the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Seibu Holdings?
If Seibu Holdings is raising questions for you, broaden your watchlist now and let the numbers highlight other potential opportunities before the crowd catches on.
- Target quality at a discount by scanning companies flagged as 15 high quality undervalued stocks that combine stronger fundamentals with more modest pricing multiples.
- Focus on resilience and capital strength through a list of solid balance sheet and fundamentals (22 results) that can help you filter for sturdier financial footing.
- Dial down portfolio stress by filtering a 22 resilient stocks with low risk scores that screens for businesses with fewer red flags on key risk checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com