
UK Stock Market Today: FTSE 100 Futures Edge Up On Brexit Red Tape Easing Hopes
The Morning Bull - UK Market Morning Update Tuesday, 3 Nov 2026
UK stocks look set for a mildly positive open, with FTSE 100 futures slightly higher and volatility gauges softer. The dominant driver is politics turning into policy, as the UK and EU edge toward scrapping Brexit red tape on food exports.
The draft UK EU deal targets checks and paperwork on food shipments, which have weighed on cross channel trade since Brexit. Easing those frictions would signal closer regulatory alignment and clearer trading rules, a shift that usually feeds into calmer FX pricing and steadier equity sentiment.
Cleaner access to the EU market can lower compliance costs for exporters and smooth supply chains, which helps profit visibility. That, in turn, can influence how investors think about earnings resilience and balance sheet strength for companies heavily exposed to European demand.
The open question is how far this cooperation goes beyond food. Investors now have to judge whether this is a one off fix or the start of a broader reset in UK EU economic relations that could reprice country risk for UK assets.
Stocks to Watch Before the Opening Bell
Barclays (BARC)
Rosen Law Firm has started investigating potential securities claims tied to Barclays and its exposure to collapsing UK mortgage provider Market Financial Solutions. The legal group is preparing a class action and is inviting shareholders to inquire about possible recovery of losses with no upfront fees. Readers will be watching for any formal filing and for Barclays response to the allegations.
Rio Tinto Group (RIO)
Rio Tinto has locked in agreements with the Tasmanian and Australian governments to keep the Bell Bay Aluminium smelter running until 2031. The facility produces about 190,000 tonnes of aluminium a year and its current power deal with Hydro Tasmania ends on 31 December 2026. Attention now shifts to the detailed power terms and any future capital plans for the site.
Grainger (GRI)
Grainger has reached the topping out phase at Alloy Apartments, a £75 million build to rent project in Guildford that will add 179 homes. The scheme is part of a combined £116 million commitment in the town and sits within Grainger's wider pipeline. Management links that investment programme to a target of 35% earnings growth by FY29, so delivery milestones here matter.
Top Movers
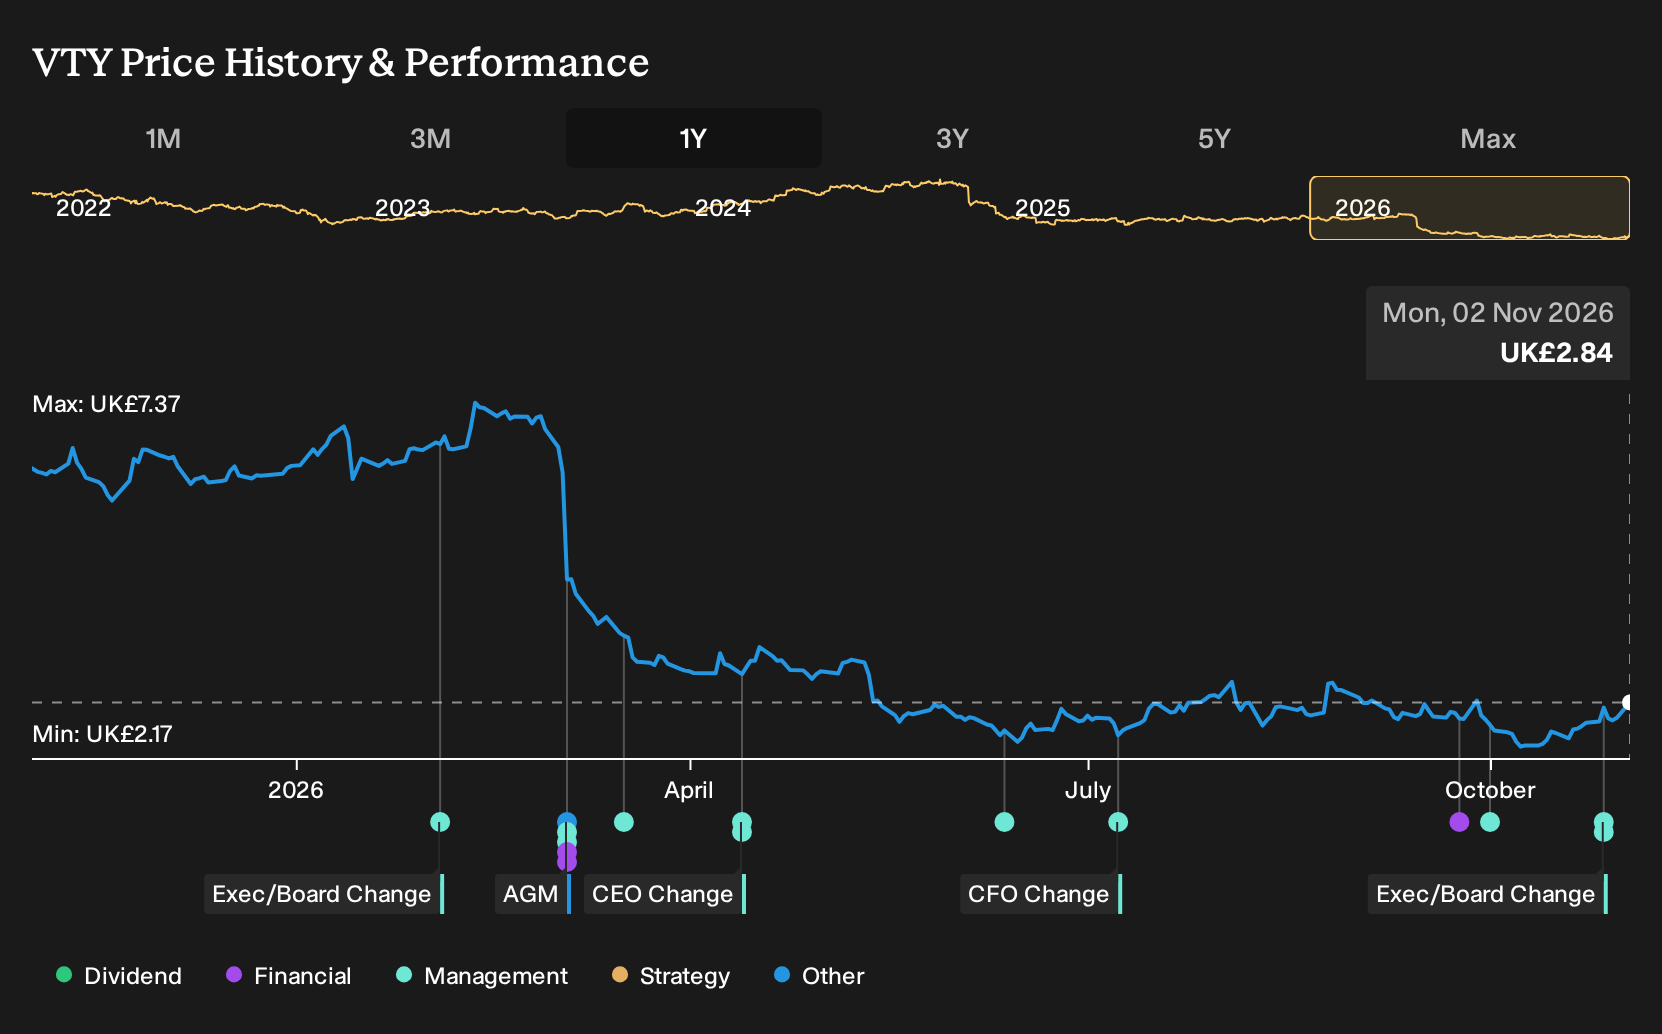
- Vistry Group (LSE:VTY) surged 8.90%.
- FirstGroup (LSE:FGP) jumped 7.10% after agreeing a £109m depot sale and securing new West Yorkshire bus franchises.
- Wizz Air Holdings (LSE:WIZZ) rose 5.28% as investors looked past a resolved bomb threat incident, with the flight continuing.
Top Losers
- ACG Metals (LSE:ACG) declined 8.39% after weaker Q3 production figures and updated guidance focused only on oxide output.
- Polar Capital Holdings (AIM:POLR) declined 7.12%.
- Energean (LSE:ENOG) declined 4.10% as lower oil prices weighed on the wider energy sector and related equities.

On The Radar
The next few sessions pivot around Bank of England policy and a heavy run of FTSE corporate results. These could reshape how you think about UK rates, housing exposure and domestic consumer stocks.
- BoE Interest Rate Decision Thu 5 Nov. The Bank of England meets with the base rate at 3.75% and a consensus and forecast of 4%. A move above or below that level would directly influence UK borrowing costs, gilt pricing and sterling sensitive exporters.
- S&P Global Construction PMI Thu 5 Nov. The October reading follows a previous 46.1 with the consensus also at 46.1 and a forecast of 45.5. A print above that range would ease pressure on UK housebuilders and listed contractors, while a weaker figure would keep the sector under strain.
- Marks and Spencer Group Wed 4 Nov. Half year 2027 numbers land as UK retailers juggle cost pressures. Commentary on margins and store profitability will matter most for how investors treat broader UK high street exposure.
- BT Group Thu 5 Nov. Second quarter 2027 results at 7:00 AM UTC focus attention on cash generation and network investment. Any shift in capex plans or dividend stance could ripple across high yield UK telecom stocks.
- ASOS Thu 5 Nov. Full year 2026 figures put the spotlight on online fashion demand. Revenue trends by region and any guidance on returns costs will feed into views on UK ecommerce business models.
Sector & Industry Watch
Financials: Legal risk and BoE in focus
Financials have come under pressure over the past week, with Banks weakening faster than the wider group as the Barclays class action story adds another layer of concern to existing questions around funding costs. That combination keeps attention on dividends, buybacks and how much capital lenders want to keep back for potential loan losses.
If you hold UK bank heavy funds, the key near term swing factor is still Thursday’s Bank of England interest rate decision and vote split, because that guides expectations for mortgage margins and future payout policies across the sector.
Metals and Mining: Global selloff weighing on UK miners
Metals and Mining have eased over the past seven days and month, even though the group still shows a gain of a little over 20% over 12 months. Reports of around 26% of global mining value being wiped out since February, together with softer sentiment around gold, silver and lithium prices, are affecting UK stocks such as Rio Tinto, Anglo American, Fresnillo and Antofagasta.
If mining companies feature in your portfolio, the key macro signal to watch is Wednesday’s euro area inflation flash reading, because any shift in price pressures can change views on European industrial demand and so revenue expectations for copper, iron ore and precious metal producers.
Energy: Oil and Gas tied to crude swings
Energy and Oil and Gas have moved broadly sideways over the last week after strong 12 month gains of roughly 40%, with sector mood set day to day by moves in Brent alongside company news from groups such as BP, Shell, Diversified Energy and Serica. Deals like Diversified Energy’s US$1.8b Birch purchase and Serica’s new UK drilling plans show capital still flowing into production, even as headlines link recent share price softness to lower oil.
If Energy stocks sit in your ISA, the cleanest external driver to track this week is the run of US crude and gasoline inventory data, because sharp changes in oil prices can quickly influence both your fuel bill and cash generation for London listed producers.
Real Estate: Property gains tested by rate risk
Real Estate has edged higher over the past week and month, with a roughly 1.5% seven day rise adding to a 4.7% move over 12 months helped by news from Grainger, SEGRO and LondonMetric. That recovery comes after weaker earnings in recent years, so higher borrowing costs and refinancing needs remain front of mind for landlords and housing focused groups.
If you own property stocks or REITs, the combination to watch is Thursday’s UK Construction PMI alongside the Bank of England decision, since building activity and the cost of debt together influence both rental income prospects and asset values across offices, warehouses and residential schemes.
Healthcare: Pharma and biotech driven by pipeline
Healthcare, including Pharmaceuticals & Biotech, has been one of the stronger areas over the past week, with gains of roughly 2% to 3% supported by AstraZeneca’s RNA work and contract wins at IXICO. These sectors already show multi year earnings growth and currently trade on P/E multiples in the low 20s, which sit slightly under their three year averages.
If healthcare holdings form part of your pension or ISA, the single most important driver to monitor is company pipeline news such as trial awards and regulatory milestones, because fresh data on drugs and clinical services often moves these shares more than broad macro releases or even central bank decisions.
How To Act On Today's Market
If the Barclays legal headlines and Bank of England rate decision are front of mind, start by stress testing your portfolio against this list of 216 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com