
PriceSmart (PSMT) Just Gave Investors Something To Parse
Why PriceSmart’s latest earnings and expansion matter now
PriceSmart (PSMT) just reported fourth quarter and full year results alongside news of a new warehouse club in Jamaica, giving investors fresh data on both profitability and physical footprint expansion.
Despite the fresh earnings beat and Jamaica expansion, PriceSmart’s share price has cooled in recent months. The 90 day share price return is down 13.76%, while the year to date share price return is up 35.22% and the 3 year total shareholder return is 158.42%. This suggests long term holders have still seen strong compounding while shorter term momentum has faded.
Scan beyond PriceSmart and see how it stacks up against 19 high quality undiscovered gems with similar growth profiles that are still flying under most investors’ radar.
PriceSmart now trades at an 8% discount to the average analyst target, while showing a slight premium to one intrinsic value estimate. Is the recent pullback a sign of excess caution, or fair skepticism on price?
Most Popular Narrative: 8% Undervalued
PriceSmart’s most followed narrative pegs fair value at $181.50, slightly above the last close of $166.77, which frames the recent share pullback as a modest gap rather than a deep disconnect.
The recently opened clubs in high-growth regions and concrete plans for new locations in untapped cities within existing markets, as well as exploration of Chile, a country with a strong, stable middle class, signal an accelerating club rollout strategy poised to widen PriceSmart's addressable market, supporting sustained revenue growth and geographical diversification.
See why 3 investors see PriceSmart as 8% undervalued.
Result: Fair Value of $181.50 (UNDERVALUED)
Still, PriceSmart’s story can shift quickly if foreign currency constraints or higher logistics and technology expenses begin to weigh more heavily on profitability.
Find out about the key risks to this PriceSmart narrative.
Another View: PriceSmart through the earnings multiple lens
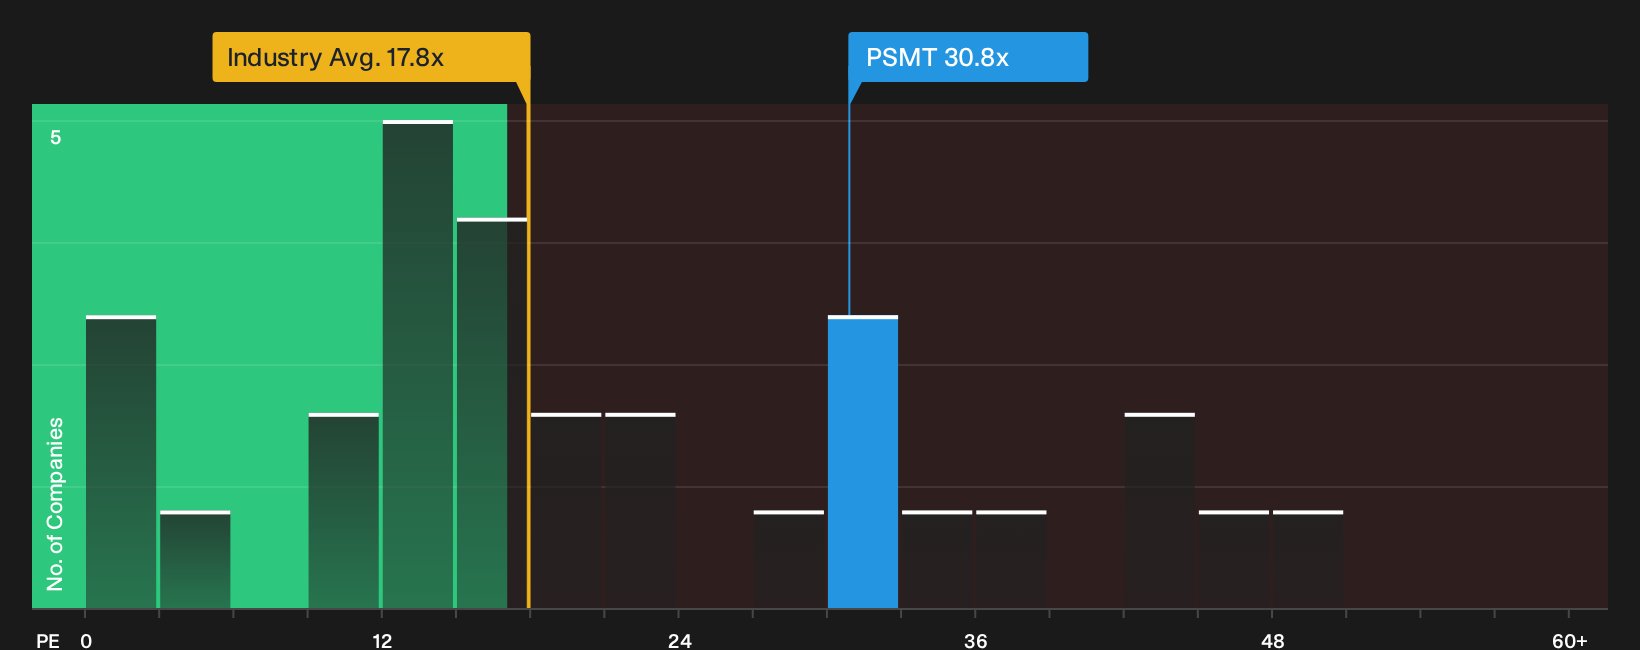
That 8% gap to fair value looks modest once P/E is brought into the picture. PriceSmart trades on 30.8x earnings, while the US Consumer Retailing industry averages 17.8x and peers sit near 18.4x. The fair ratio points to 22.4x. Is the premium justified, or simply expensive?
See what the numbers say about this price in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages in PriceSmart’s story today, with both concerns and bright spots in play, mean your own judgment matters more than ever. Move fast on the numbers and read both sides of the argument in the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond PriceSmart?
If PriceSmart has your attention but you want a broader watchlist, use this moment to line up your next set of potential opportunities before others do.
- Target stronger balance sheets and steadier fundamentals by scanning the list of solid balance sheet and fundamentals (24 results) that could handle tougher conditions without breaking stride.
- Hunt for quality at a discount by reviewing the 34 high quality undervalued stocks that pair solid businesses with price tags that may not fully reflect their fundamentals.
- Prioritize resilience and sleep-better-at-night positions by focusing on the 29 resilient stocks with low risk scores that score well on financial strength and volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com