
How Investors May Respond To Alamo Group (ALG) Earnings Miss
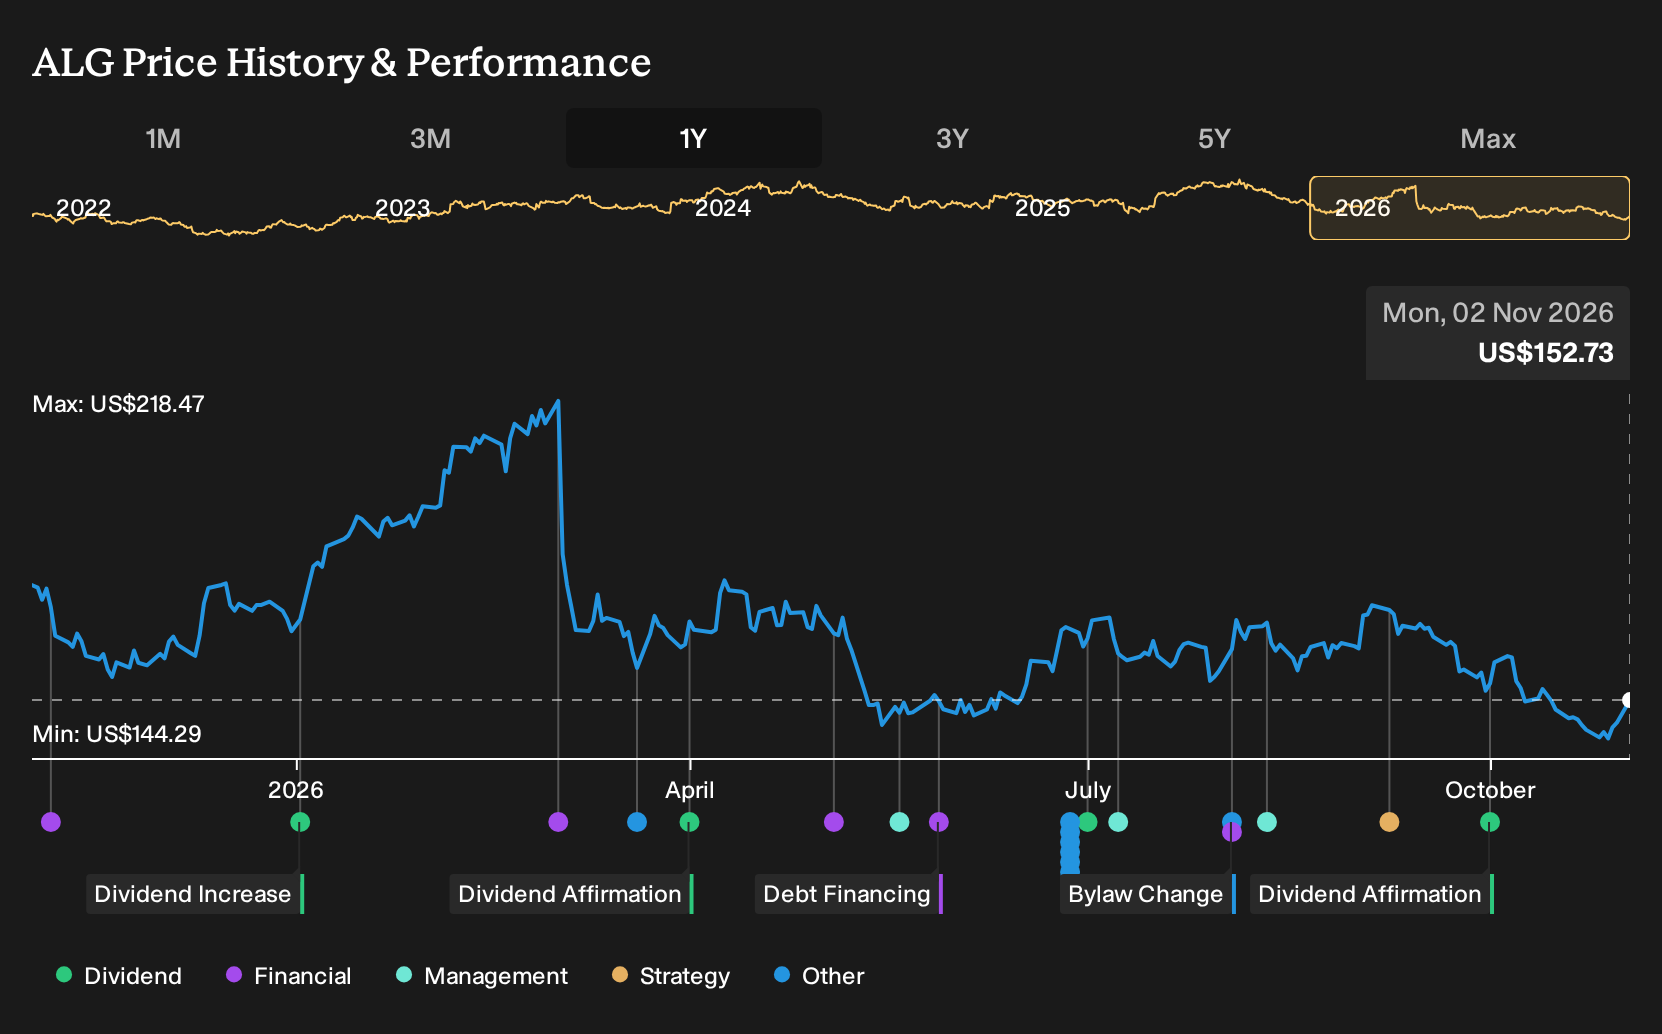
- Alamo Group reported third quarter 2026 revenue of US$403.1 million and net income of US$2.0 million, with adjusted earnings per share of US$2.06 that came in below analyst expectations and prior year results.
- The nine month figures show Alamo Group generating higher sales of US$1.27b but lower net income of US$62.2 million, reflecting pressure on profitability even as management highlights stronger order intake in areas like vacuum trucks and sweepers.
- The focus now is on how Alamo Group's weaker than expected third quarter profitability may influence the longer term investment narrative investors have been using.
Alamo Group Investment Narrative Recap
To own Alamo Group, you need to be comfortable with a story where margin repair is just as important as sales. The latest quarter showed US$403.1 million in revenue but only US$2.0 million in profit, so the near term hinge is whether procurement savings, price increases and aftermarket parts can stabilize earnings. The biggest swing factor remains execution on these cost and mix efforts against inflation and tariff headwinds.
The key risk is that profitability in areas like Vegetation Management and acquired units takes longer to normalize, which could keep group margins subdued even with order strength in vacuum trucks and sweepers. If that happens, the current margin framework and earnings ambitions could prove too optimistic for the medium term.
The acquisition of Econ Engineering Group looks most relevant here because it directly plugs into Alamo Group’s industrial portfolio of vocational trucks. This broadens the product set in categories like snow and road equipment, where the Wide Wing snow system and other offerings already matter for pricing and capacity utilization, tying into the company’s margin and mix goals.
Execution on Econ now sits alongside internal projects such as the hybrid sweeper launch and the procurement program as an important operational catalyst. Integration risk is not theoretical, because prior tuck ins have brought higher interest expense and restructuring costs. Investors will likely watch how quickly this asset tracks toward the kind of margin and cash generation profile management has discussed for previous deals.
Alamo Group's narrative projects US$1.9b revenue and US$206.9 million earnings by 2029. This implies 4.6% yearly revenue growth and roughly a US$105.9 million earnings increase from US$101.0 million today.
Uncover why Alamo Group's fair value indicates a 34% potential upside to its current price before that discount to Alamo Group's shares closes.
Exploring Other Perspectives
The Simply Wall St Community contributes three fair value estimates for Alamo Group, ranging from US$140 to about US$235.59, so private investors are clearly not aligned on what the shares are worth. You can set those views against weaker recent earnings and integration risk around Econ, and then decide which narrative you find more convincing.
Explore 2 other Alamo Group fair value estimates, including one that indicates up to 8% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Alamo Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alamo Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alamo Group's overall financial health at a glance.
Looking for more Alamo Group style investment ideas?
If the situation at Alamo Group has sharpened your focus on quality, use that same lens across the wider market with the Simply Wall St Screener. You can filter by balance sheet strength, income potential or valuation support, then compare each candidate against your own risk tolerance and return goals.
- For investors who care most about resilient finances and staying power, start with a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without stretching the balance sheet.
- If your priority is finding stocks where quality and valuation both matter, scan through 19 high quality undiscovered gems that combine stronger fundamentals with less attention from the crowd.
- Income focused investors can zero in on stability and cash returns by reviewing 4 dividend fortresses that put a 5%+ yield alongside sturdier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com