
Wolfspeed (WOLF) Stock Could Be Overvalued As It Fell 41%
Wolfspeed has seen its share price fall sharply in recent weeks, and that slide puts fresh focus on a basic question for investors who follow the stock: whether today's valuation can still be explained by its sales. With the business pushing into new silicon carbide products and long-term supply deals, the market is being asked to price a lot of future revenue into a share price that has been under pressure.
- The stock has declined 40.9% over the past month. This puts recent expectations for Wolfspeed's revenue potential under a harsher spotlight.
- The commercial launch of transparent silicon carbide technology for uses such as AR hardware and quantum computing may support views of a broader addressable market and potentially higher future sales intensity per customer over time.
- There is a second opinion on Wolfspeed worth weighing. See what analysts think Wolfspeed's shares could be worth.
The issue now is whether the recent share price around US$20.85 is appropriately grounded in Wolfspeed's current sales base and how investors value that revenue stream.
If you are questioning whether Wolfspeed's recent slide leaves the stock pricing in too much future sales, a focused screen of 53 AI infrastructure stocks can give you more ideas for comparison.
Has Wolfspeed Run Too Far on Sales?
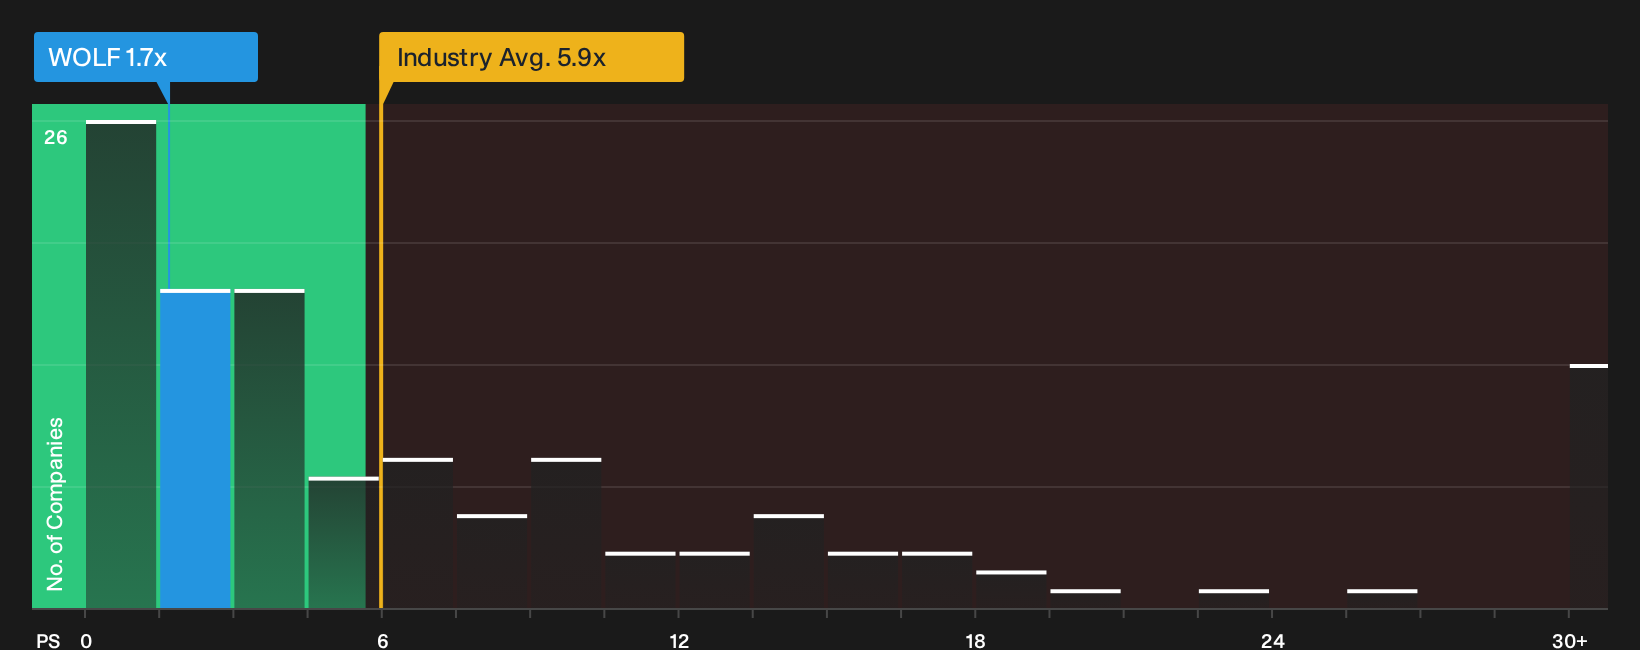
P/S is a useful lens for Wolfspeed because the business is still working through heavy investment and reported free cash flow losses, so the revenue line offers a cleaner anchor than earnings. On this measure, Wolfspeed trades on a P/S of 1.7x, compared with a semiconductor industry average of 5.9x and a peer group around 8.5x. As a result, the stock changes hands at a sizeable discount to revenue multiples elsewhere in the sector.
The fair ratio model, which blends factors such as growth profile, margins, risk and size into a tailored benchmark, sits above Wolfspeed's current P/S. The shares therefore screen overvalued even with that low headline multiple. Because the commercial rollout of transparent silicon carbide for AR and quantum computing has sharpened interest in Wolfspeed's potential opportunity, the market seems to be assigning a full price to each dollar of current sales despite the lower P/S than peers. Readers weighing this setup will need to judge whether that gap to the model is justified by the product pipeline and long term contracts, or whether it points to limited room for error at today's revenue multiple. Explore the numbers behind Wolfspeed's P/S valuation.
The Wolfspeed Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Wolfspeed pick up where the earlier valuation puzzle leaves off, spelling out the specific paths for growth, profitability and earnings that would need to play out for the stock to be worth materially more or less than today’s price. Rather than stopping at a single model output or ratio, they unpack the future Wolfspeed story that number relies on so you can track how real-world developments compare with it over time on the Community page.
One of the top community narratives on Wolfspeed: 17% undervalued
"Wolfspeed is vertically integrated in silicon carbide materials and devices and is guiding to continued growth in its power device business…"
Discover why this Narrative puts Wolfspeed at 17% undervalued.
Wolfspeed’s valuation still leaves one crucial issue unanswered
Price multiples and growth stories only tell part of what matters for Wolfspeed. Our broader checks have raised specific concerns that investors often overlook, and those signals deserve a closer look before you decide what comes next. Take a closer look at 5 warning signs (4 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com