
Did Dividend Hike Just Shift OFG Bancorp (OFG) Investment Narrative?
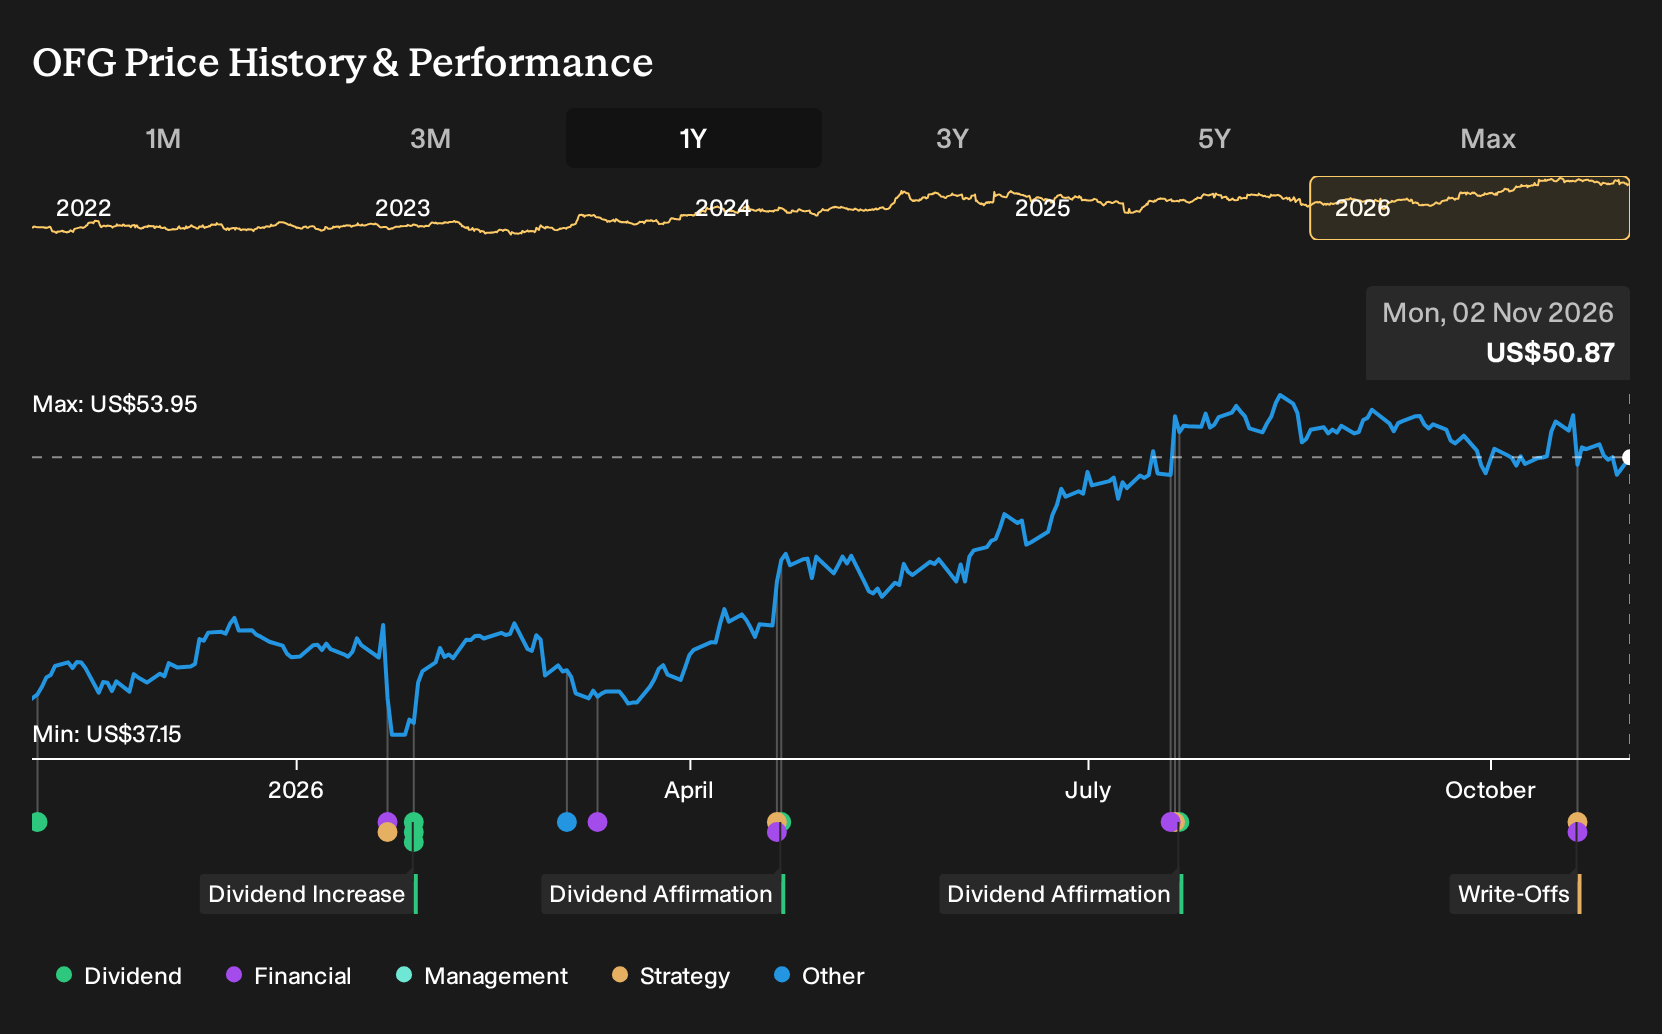
- OFG Bancorp raised its regular quarterly cash dividend by 14% to US$0.40 per share for the quarter ended December 31, 2026, payable January 15, 2027, following third quarter 2026 net income of US$56.61 million and ongoing share repurchases under its 2026 buyback program.
- The higher dividend, combined with net charge offs of US$14.46 million that were lower than a year earlier, indicates a board that appears comfortable returning more capital while the bank manages credit costs and continues to reduce its share count through repurchases.
- The next step is to assess how OFG Bancorp's 14% dividend increase may influence the existing investment narrative built around digital growth.
Scan how OFG Bancorp's dividend move compares with other payout heavyweights by reviewing the hand picked 4 dividend fortresses in the current market.
OFG Bancorp Investment Narrative Recap
To own OFG Bancorp, you need to be comfortable with a Puerto Rico focused lender that leans on digital banking, loan growth and capital return to drive value, while accepting concentrated regional and credit exposure. The recent 14% dividend lift and ongoing buybacks sit against this backdrop and do not materially change the near term story.
The key near term swing factor still sits in net interest income and credit trends. Third quarter 2026 net interest income of US$153.57 million and net charge offs of US$14.46 million frame how OFG Bancorp is managing margin pressure and loan quality. The main risk remains any shock to the Puerto Rican economy that hurts credit costs and funding.
The most relevant data point alongside the dividend move is third quarter 2026 earnings. Net income of US$56.61 million for the quarter and US$169.33 million for the first nine months of 2026 shows the bank funding higher payouts from an active business, not from one off actions. For you, the question is how durable that earnings base feels.
Those results sit next to a buyback program where 418,061 shares, about 0.98% of the float, have been repurchased for US$19.9 million in 2026. If OFG Bancorp keeps combining dividend growth, repurchases and digital user expansion with controlled net charge offs, that could support the existing catalyst narrative, while any reversal in credit or margin trends would test it quickly.
What The OFG Bancorp Forecasts Assume
For anyone tracking OFG Bancorp, the analyst playbook now on the table is fairly clear. The projections tie the dividend story and buybacks to a picture where revenue is expected to rise, while earnings step down from today’s level and margins compress over time.
Analysts are building their models around yearly revenue growth of 8.3% over the next three years. That forecast is paired with an assumed move in profit margins from 33.9% today to 24.8% by 2029, so the top line is expected to be higher but with less profit dropping through on each dollar of income. The key earnings input is current profit of US$220.4 million, which analysts see moving to US$205.4 million by about 2029.
That expected earnings path is tied to a share count that analysts think will decline by 3.84% a year over the coming three years. For you, that means the headline profit pool is forecast to be smaller, but spread over fewer shares. In practice, the digital banking push, Puerto Rico focused loan book and capital return policy all need to work hard just to support that future profit number.
On these assumptions, the analyst framework uses a discount rate of 7.24% from the underlying Simply Wall St work to pull those estimated cash flows back into today’s terms. The implied future P/E in the story is 12.7x on the 2029 earnings estimate, compared with 9.7x today and a current US Banks sector P/E reference point of 11.4x. That gap indicates that the scenario being priced into the target requires investors to accept OFG Bancorp trading at a richer multiple than both its current level and the sector marker.
Across this setup, the core swing variables for your own view are simple. Do you think OFG Bancorp can sustain roughly 8.3% annual revenue expansion while accepting tighter margins, and do you agree that a higher future P/E ratio is reasonable for a regional lender concentrated in Puerto Rico with a digitally focused model and ongoing buybacks?
OFG Bancorp's narrative projects US$826.7 million revenue and US$205.4 million earnings by 2029. This assumes 8.3% yearly revenue growth and an earnings decrease of about US$15 million from US$220.4 million today.
Uncover why OFG Bancorp's fair value indicates an 11% potential upside to its current price that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community range from US$56.50 to about US$121.27. As a result, some members see OFG Bancorp as heavily discounted, while others view it as closer to fully priced. Consider factors such as Puerto Rico concentration risk and net interest margin pressure, then compare these contrasting views to test your own thesis.
Explore another OFG Bancorp fair value estimate, including one that suggests the potential for as much as 138% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your OFG Bancorp research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for OFG Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, which makes it easy to evaluate OFG Bancorp's overall financial health at a glance.
Looking for more investment ideas beyond OFG Bancorp?
If you want to pressure test your thesis on OFG Bancorp against other opportunities, use the Simply Wall St Screener to see how different businesses stack up on income, quality and risk, then decide where fresh capital belongs next.
- If reliable income is a priority, compare OFG Bancorp with other high yield candidates by scanning the 4 dividend fortresses that are built around steady payouts.
- For readers focused on quality at a sensible entry point, weigh OFG Bancorp against a curated 34 high quality undervalued stocks that pair solid fundamentals with compressed valuations.
- If capital protection matters most, stress test your risk tolerance by lining OFG Bancorp up against a 29 resilient stocks with low risk scores designed to keep drawdowns in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com