
Higher Nine Month Earnings Might Change The Case For Investing In Bankinter Stock
- Bankinter reported results for the nine months to 30 September 2026, with net interest income of €1,778.32 million and net income of €900.67 million, alongside basic EPS from continuing operations of €0.97.
- The uplift in both net interest income and earnings per share suggests Bankinter is generating more profit from its existing balance sheet and fee engine, rather than relying solely on new lending growth.
- We will now assess how Bankinter's higher net income for the first nine months of 2026 could reshape the broader investment narrative.
Bankinter Investment Narrative Recap
To own Bankinter, you need to be comfortable with a bank that leans heavily on fee income, digital efficiency and tight risk control, rather than chasing raw loan expansion. The latest nine month figures, with net interest income of €1,778.32m and net income of €900.67m, broadly support that story but do not radically change it.
The near term swing factor remains how well Bankinter manages funding costs and technology spending, while keeping its cost to income ratio moving in the right direction. The key risk is that expenses or credit losses rise faster than fee and interest income, which would challenge the current efficiency and earnings narrative.
The most relevant data point for this earnings update is the basic EPS from continuing operations of €0.97 for the first nine months of 2026, compared with €0.87 a year earlier. That step up builds on the existing view that Bankinter has been growing profit, with earnings reported as having risen 14.1% over the past year.
For you as a shareholder, the link between this EPS progress and the broader catalyst list is straightforward. Consistent profit growth supports the case that digital investment, fee based activities and international operations in Portugal and Ireland are feeding into higher earnings. At the same time, risks such as a low allowance for bad loans at 67% remain key watchpoints in that context.
What The Analyst Framework Implies For Bankinter
Analysts frame Bankinter's next stage around steady top line expansion and only a slight squeeze on profitability, rather than a big shift in the business model. The consensus view points to revenue rising at 10.4% a year over the next three years while profit margins move from 40.6% today to 39.2% in that timeframe. This assumes the bank absorbs extra technology and growth spending without a sharp hit to earnings quality.
On the earnings side, the group of forecasts points to profit of €1.5b by around October 2029 and earnings per share of €1.66, compared with about €1.2b of earnings today. That implies an earnings increase of roughly €300m over that period, based on the analyst numbers provided, with the path supported by expectations for revenue growth, tighter cost control and a gradual reduction in shares outstanding of 3.65% a year.
Valuation work in these reports then links those profit estimates to what investors are currently paying for Bankinter. The scenario assumes a P/E of 11.3x on the projected 2029 earnings, compared with 11.7x today and the 13.1x level cited for the wider GB Banks sector, along with a discount rate of 7.8% to translate that future profile into today's terms.
Bankinter's narrative projects €3.8b revenue and €1.5b earnings by 2029. This assumes 10.4% yearly revenue growth and an earnings increase of about €300m from €1.2b today.
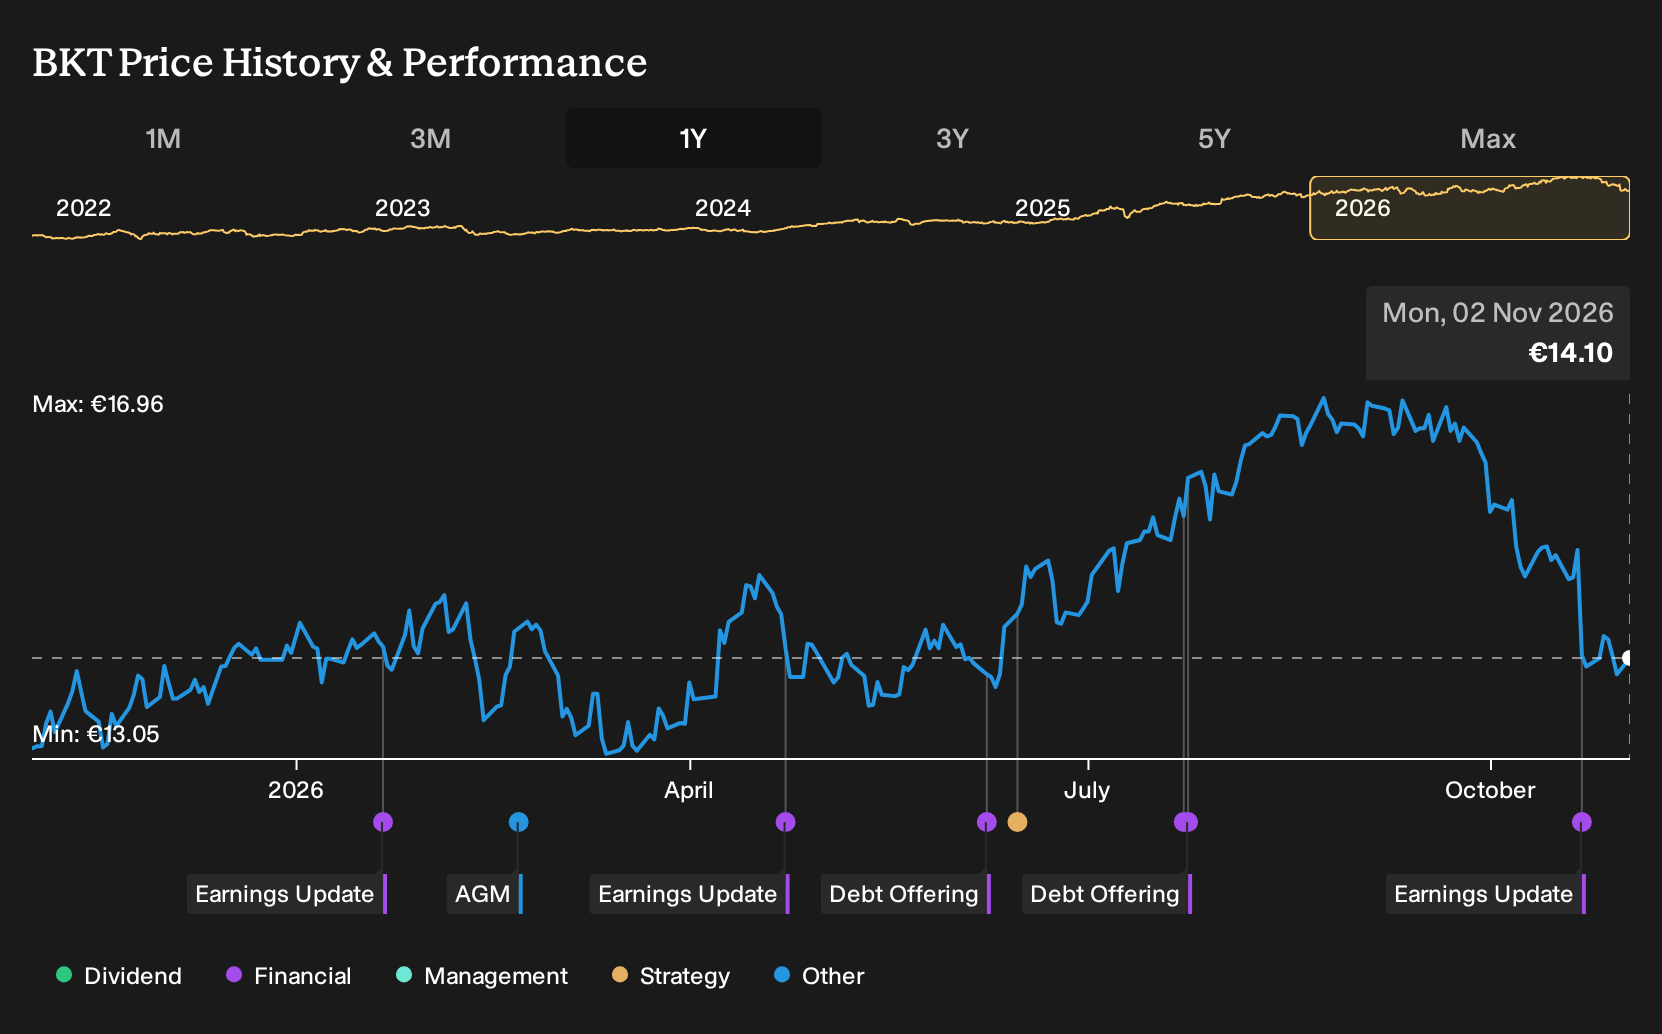
Consensus price targets try to condense all of this into a single number for the stock. The central target sits at €16.71 per share against a current price of €14.99, with the most optimistic estimate at €22.50 and the most cautious at €10.30. That range shows that even with shared assumptions on revenue, earnings and margins, different analysts reach very different conclusions once they factor in risks and required returns.
For you as an investor, the practical test is simple. If you think Bankinter can reach about €3.8b of revenue and €1.5b of profit by 2029 and that the market is comfortable paying around 11.3x earnings at that point, then the consensus framework broadly lines up with your view. If you see a different path for fee growth, credit costs or capital needs, your own assessment of fair value will naturally sit above or below the current analyst targets.
Discover how Bankinter's fair value indicates a 19% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You now have a clear beat to watch. The most optimistic analysts lean on Bankinter’s wealth and alternative investment platforms as a future earnings engine, with pre news forecasts near €4.0b of revenue and €1.6b of profit by 2029. Your job is to decide whether these fresh nine month results shift that story up or down.
Explore 2 other Bankinter fair value estimates, including one that suggests as much as 82% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Bankinter research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Bankinter. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bankinter's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bankinter?
If this update on Bankinter has sharpened your sense of what you want from a financial stock, the next step is to widen the search. The Simply Wall St Screener can help you quickly filter the market by quality, risk and income profile so you can line up a watchlist that fits your own playbook.
- If capital protection comes first for you, start with a focus on resilient businesses that carry fewer red flags by scanning our 216 resilient stocks with low risk scores.
- For investors who care most about strong balance sheets and underlying fundamentals, set your filters around financial strength and cash generation using the list of solid balance sheet and fundamentals (197 results).
- If you are hunting for companies that the crowd has not fully priced yet, cast a wider net across under followed quality stocks through the 603 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com