
Compass (COMP) Bounced In A Sharp 1 Day Move, Is It Still Trading At A Discount?
Compass (COMP) has drawn fresh attention after a recent 1 day move of about 4.7%, breaking from weaker performance over the past 3 months and a softer year to date return.
That sharp 1 day share price return of 4.67% follows a mixed stretch for Compass, with the share price down 21.5% over 3 months and 10.29% year to date. At the same time, the 1 year total shareholder return of 21.08% and 3 year total shareholder return above 3x highlight longer term momentum that has cooled recently.
Scan beyond Compass and see how it compares with other real estate and property platform stocks on our hand picked 19 high quality undiscovered gems.
Compass now combines a recovering real estate platform with a share price that has lagged in recent months. After that sharp one day bounce, is the business still being valued based on its weaker stretch or its recent profitability?
Most Popular Narrative: 34% Undervalued
Compass is trading at $9.42 against a widely followed fair value estimate of about $14.23, so the current quote sits well below that narrative view of what the business could be worth. That gap is grounded in a story about tech driven productivity, profit potential and how far those trends can travel over time.
Rapid adoption and continuous improvement of Compass's AI-powered, end-to-end technology platform is increasing agent productivity, driving higher transaction volumes, improving retention, and is expected to widen margins as AI-driven process efficiencies scale throughout the organization, positively impacting revenue, EBITDA, and net margins.
See why 16 investors see Compass as 34% undervalued.
The most followed narrative applies a 9.6% discount rate and assumes Compass can grow revenue from a base of $10,555.6m while lifting net profit from $67.5m, which reflects its recent move into profitability. Those assumptions feed into a projected earnings profile that, in that framework, supports a higher valuation than where the stock changes hands today.
Analysts contributing to this storyline converge on a fair value of about $14.23 per share, with a future P/E profile of 37.1x tied to their earnings outlook and risk view. That implies investors who accept those inputs are treating the current 34% discount to that estimate as a gap between recent share price pressure, legal uncertainty and the longer term earnings path laid out in the narrative.
Result: Fair Value of $14.23 (UNDERVALUED)
Still, that story can unravel quickly if commission focused revenue comes under pressure from regulatory changes or if ongoing litigation around the Anywhere merger weighs on sentiment.
Find out about the key risks to this Compass narrative.
Another View: What Compass’s P/E Is Telling You
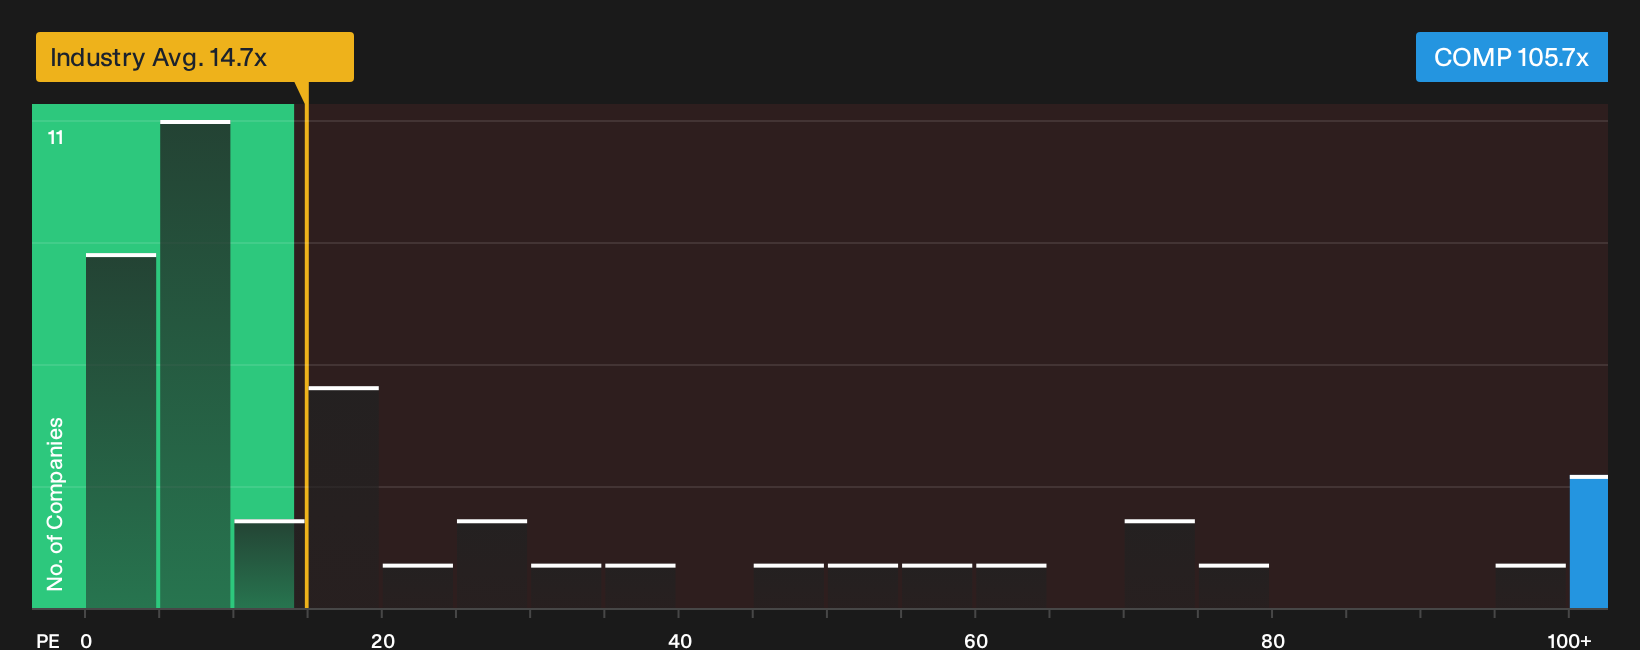
Compass might look cheap against a $14.23 fair value story, yet the market is putting a heavy price on current earnings. The stock trades on a P/E of 105.7x versus a fair ratio of 36.1x, a US real estate industry average of 14.7x and peer levels around 59.1x.
That kind of gap suggests investors are already paying up for a lot of future progress, so any earnings wobble or slower growth could hit sentiment quickly. The question for you is simple: Is that rich multiple the risk you want to take for the potential upside in the story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Compass can make the story feel messy, so move quickly, review the upside and the red flags, and weigh the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Compass?
If Compass has you thinking harder about where to put fresh capital next, use the Simply Wall St Screener to hunt for ideas before the crowd catches on.
- Target higher potential value by scanning a focused set of 34 high quality undervalued stocks that pair strong fundamentals with prices below their estimated worth.
- Prioritise resilience and sleep better at night by filtering for 29 resilient stocks with low risk scores that score well on balance sheet strength and volatility.
- Hunt for underfollowed opportunities by zeroing in on a 19 high quality undiscovered gems that combines quality metrics with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com