
Sabra Health Care REIT (SBRA) Could Be 13% Undervalued After Third Quarter Earnings
How Sabra Health Care REIT’s Latest Earnings Shape the Story
Sabra Health Care REIT (SBRA) put fresh numbers on the table with its third quarter 2026 earnings, giving investors new detail on revenue, profit and earnings per share trends.
For the three months to September 30, sales came in at US$103.18 million, with reported revenue of US$249.57 million. Net income for the quarter was US$28.61 million, and basic and diluted earnings per share from continuing operations were both US$0.11.
The nine month picture looks different. Sabra Health Care REIT reported sales of US$299.54 million and revenue of US$707.18 million for the period. Net income over those nine months was US$44.29 million, with basic earnings per share from continuing operations at US$0.17 and diluted earnings per share also at US$0.17.
Investors now have two timelines to weigh. The quarter shows one pattern for profit and per share earnings, while the year to date figures highlight a separate set of earnings outcomes that matter for anyone tracking this REIT’s income profile.
Recent trading has been mixed for Sabra Health Care REIT, with a 1 day share price return that slipped 0.10%, a 7 day share price gain of 1.39% and a 30 day share price return of 2.92%. Over the last 90 days the share price fell 6.45%, and the stock closed at US$19.72 on the latest trading day.
Across a longer horizon, the picture looks stronger, with a year to date share price return of 2.98%, supported by a 1 year total shareholder return of 16.51%, a 3 year total shareholder return of 74.45% and a 5 year total shareholder return of 100.37%. This performance reflects how investors have been reassessing the company’s risk and earnings profile following recent quarterly results.
Scan Sabra Health Care REIT’s peers with steady earnings stories and see how its latest report stacks up against list of solid balance sheet and fundamentals (24 results) in similar sectors.
Sabra Health Care REIT now trades at a sizeable discount to both analyst targets and some intrinsic value estimates. Is that a simple pricing gap, or a market verdict on the risks in its earnings mix?
Most Popular Narrative: 13% Undervalued
Sabra Health Care REIT is framed as undervalued in the most followed narrative, with a fair value of $22.79 against the recent $19.72 close. That gap rests heavily on how well its senior housing operations perform.
The main factor that has to go as planned is that Sabra successfully executes on SHOP expansion and portfolio recycling so that occupancy, RevPOR, margins, and rent resets translate into internal cash flow growth despite higher operating costs and loan loss provisions.
The current valuation implies the share price does not fully reflect guidance for mid to high single digit normalized FFO and AFFO per share growth in 2026, the SHOP-focused investment pipeline, and the balance sheet profile.
See why 8 investors see Sabra Health Care REIT as 13% undervalued.
Result: Fair Value of $22.79 (UNDERVALUED)
Still, the narrative around Sabra Health Care REIT can crack if operator transitions drag on occupancy and NOI, or if funding that SHOP heavy pipeline strains cash and the balance sheet.
Find out about the key risks to this Sabra Health Care REIT narrative.
Another Way To Look At Sabra Health Care REIT’s Valuation
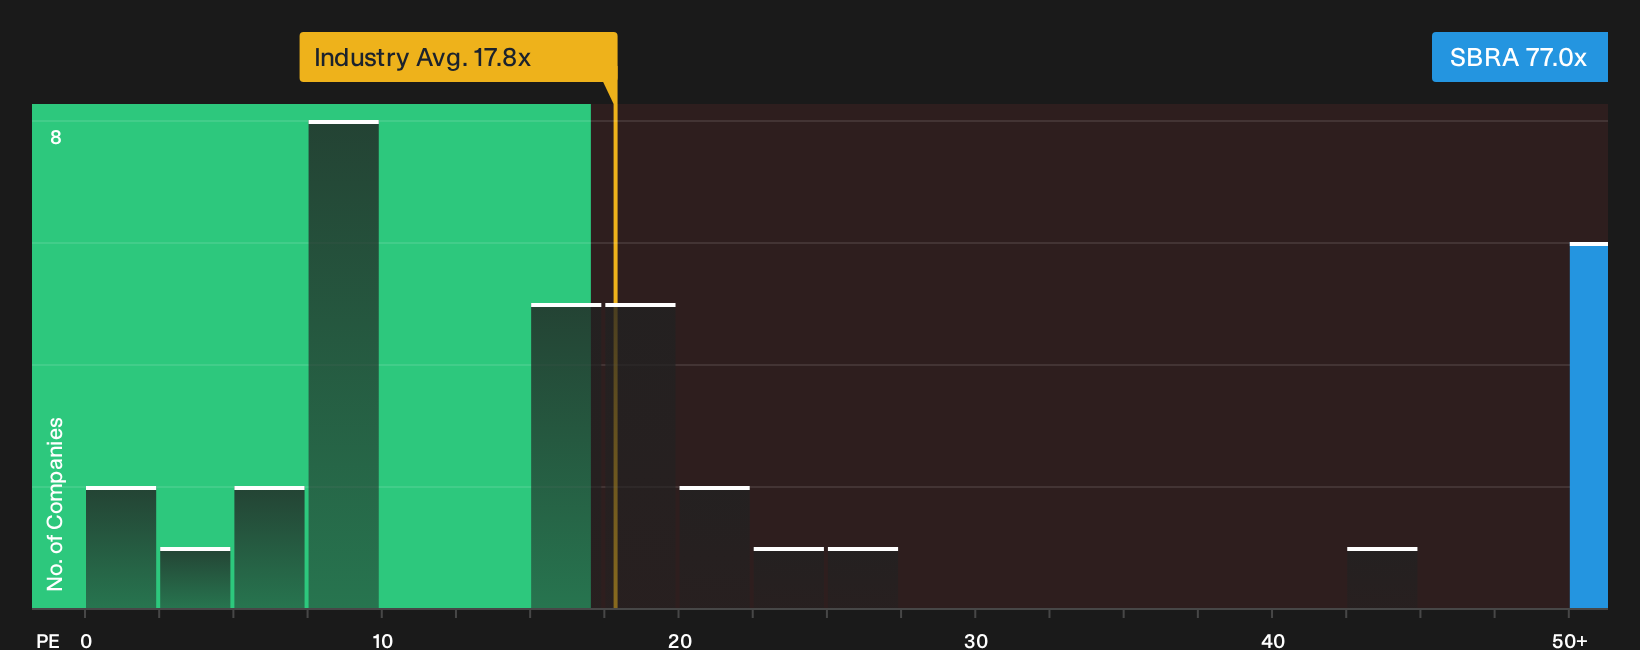
The story changes when you switch from cash flow to earnings multiples. Sabra Health Care REIT trades on a P/E of 77x, compared with a 49.1x peer average, a 17.8x sector level, and a fair ratio estimate of 49.2x. That kind of gap points more toward valuation risk than a potential bargain. Which signal do you trust more?
See what the numbers say about this price with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Sabra Health Care REIT story so far. Act while the data is fresh and weigh both sides of the ledger with 2 key rewards and 4 important warning signs.
Looking For More Investment Ideas Beyond Sabra Health Care REIT?
If Sabra Health Care REIT has sharpened your thinking, do not stop here. Broader ideas often come from comparing fresh opportunities side by side.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (24 results) that keep financial risk in check.
- Hunt for potential value opportunities by scanning 34 high quality undervalued stocks that combine quality metrics with pricing that has not fully caught up.
- Prioritise portfolio durability and income stability by focusing on 29 resilient stocks with low risk scores that aim to keep volatility and financial strain in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com