
Is Aptiv (APTV) Undervalued After Weak Earnings And Lower Full Year Guidance?
Aptiv (APTV) is back in focus after its latest earnings release fell short of investor expectations, with lowered full-year guidance and a high profile exit by Janus Henderson weighing on sentiment.
Short-term trading has been relatively calm for Aptiv, with a 7 day share price return of 1.42% and a 30 day gain of 1.58%. However, momentum has been fading over a longer horizon as the 90 day share price return declined 7.31% and the 1 year total shareholder return fell 36.15%. This reflects how the weaker earnings update and Janus Henderson exit have weighed more heavily on longer term sentiment than on recent price action.
Scan for other auto and AI plays reacting to earnings and guidance shocks by checking the hand picked 95 robotics and automation stocks alongside Aptiv.
Aptiv now trades well below past levels after guidance was cut and a major holder walked away. Do you lean into that reset today, or wait for an even cheaper entry before the valuation work lines up for you?
Most Popular Narrative: 31% Undervalued
Aptiv’s most followed valuation story pegs fair value at $64.33 against a last close of $44.23. This frames a wide gap that analysts are trying to justify through a mix of software ambitions, non-auto expansion and capital returns.
The current valuation and share repurchase plans, including more than $600 million of buybacks targeted in 2026 after a stock price decline of about 64% over five years, suggest that the market is pricing in significant execution risk even though the business continues to generate substantial earnings and cash flow.
See why 31 investors see Aptiv as 31% undervalued.
Analysts in this narrative use a 9.82% discount rate and combine forecasts for declining revenue, rising margins and a future P/E of 11.2x to reach that $64.33 figure. This implies that the current share price reflects a sizeable execution discount to those modeled cash flows. The result hinges on earnings reaching $1.4b by 2029, with share count gradually shrinking and a higher margin mix from software, ADAS and non-automotive work offsetting pressure in traditional auto components.
For you as an investor, the key question is whether that earnings and margin path feels realistic given Aptiv’s recent guidance reset, China exposure and one off items in recent results, or whether the market is correctly skeptical about that trajectory and pricing the stock more cautiously as a result. The discount between the $44.23 share price and the $64.33 narrative fair value leaves room for your own assumptions around autos demand, non auto contributions and buyback impact to shift that conclusion either way.
Result: Fair Value of $64.33 (UNDERVALUED)
Still, weak China demand and repeated guidance resets could easily undercut the Aptiv upside case and keep investors focused on execution risk rather than valuation.
Find out about the key risks to this Aptiv narrative.
Another View: Aptiv On Earnings Multiples
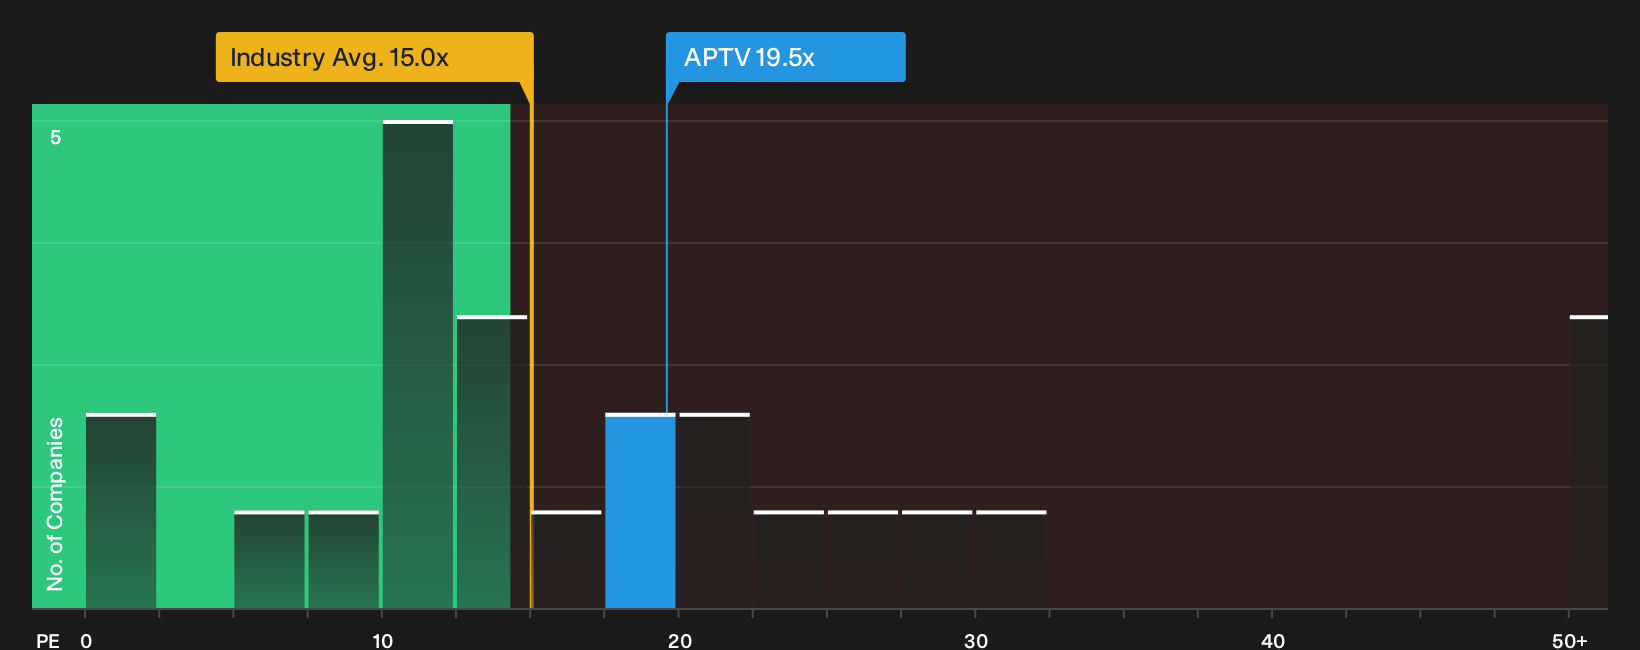
The popular Aptiv story leans on future cash flows and a fair value of $64.33. A quick reality check on today’s pricing tells a different story. On a P/E of 19.5x, the stock trades richer than the US Auto Components industry at 15x and peers at 14x, even though analysts see revenue declining about 11.2% a year and net margin currently sits at 2.3% versus 4.7% last year.
Our fair ratio points to a P/E of 23.3x, which is above where Aptiv changes hands now. That suggests the multiple could move either toward the cheaper industry and peer group, or toward the higher fair ratio, depending on whether earnings growth materializes faster than the forecast revenue decline. Which path do you think the market will reward first?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of concern and optimism around Aptiv feels familiar, use it as a prompt to review the numbers yourself and decide where you stand, then weigh both sides of the story with 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Aptiv?
If Aptiv has you rethinking where risk and reward feel balanced, broaden your watchlist with a few focused screeners built to surface different types of opportunities.
- Target potential bargains by scanning a curated mix of strong fundamentals with 34 high quality undervalued stocks.
- Prioritize resilience by filtering for companies with sturdy finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for underfollowed potential by reviewing the 19 high quality undiscovered gems before the crowd pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com