
Syndax Pharmaceuticals (SNDX) Stock May Trade At A Premium After A 38% Fall
Syndax Pharmaceuticals has had a difficult run in 2026, and the slide in the share price puts fresh focus on what investors are really paying for in terms of its sales profile. With a clinical setback on one side and an award winning leukemia treatment on the other, the question is how well the current valuation lines up with the revenue the business can generate from here.
- The stock is down about 38.5% year to date, which puts extra weight on whether the current market value can still be anchored to its sales base.
- The recent failure of the MAXPIRe Phase 2 trial in idiopathic pulmonary fibrosis, and the follow up securities investigation, may affect how investors think about future sales contributions from axatilimab and the timing of any diversification beyond existing products like Revuforj.
- Your read on Syndax Pharmaceuticals is one view; the desks covering it have another. See what analysts think Syndax Pharmaceuticals's shares could be worth.
The issue now is whether the current Syndax Pharmaceuticals share price is adequately supported by its sales and the revenue potential investors expect from its pipeline.
To put Syndax Pharmaceuticals' sales-based valuation in better context, compare it with other 34 high quality undervalued stocks that also screen for quality and pricing discipline.
Is Syndax Pharmaceuticals Getting Expensive on Sales?
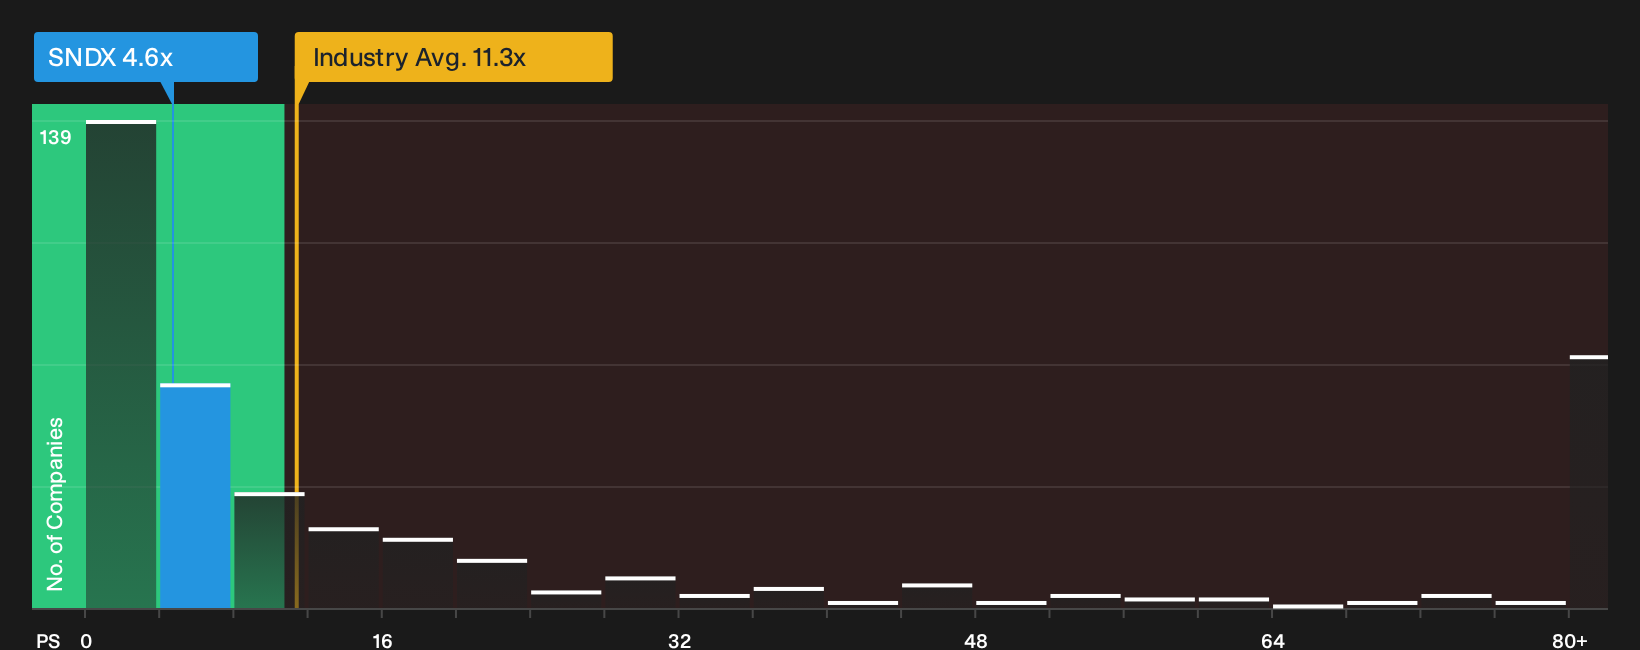
P/S is a more useful metric than P/E for Syndax Pharmaceuticals right now because the focus is on commercial traction and pipeline potential rather than accounting profits. On this basis, the stock trades on a P/S of about 4.6x, compared with a Biotechs industry average of roughly 11.3x and a peer group near 15.1x. That set of benchmarks indicates the shares change hands at a sizeable discount to what investors are paying for sales in similar businesses.
The fair multiple implied by the valuation model, which adjusts for the company’s growth outlook, margins, scale and risk profile, is above the current P/S. As a result, the shares screen as overvalued relative to that tailored yardstick, even though they still appear inexpensive against broader sector and peer averages. Because Revuforj has just received a major award for its impact in rare leukemia, the current discount to broader Biotech sales multiples suggests investors are weighing that recognition against recent trial and legal setbacks. Explore the numbers behind Syndax Pharmaceuticals's P/S valuation.
The Syndax Pharmaceuticals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Syndax Pharmaceuticals pick up where the valuation puzzle stops. They map out which combinations of future growth, profitability and earnings power would need to play out for the current share price to make sense, or for it to look materially too high or too low. Where a single ratio or model gives one output, these scenarios spell out the future that output relies on so you can watch how reality compares over time on the Community page.
One of the top community narratives on Syndax Pharmaceuticals: 65% undervalued
"The current valuation implies the market is still discounting the scale of Revuforj and Niktimvo cash flows and gives limited credit to the pipeline…"
Discover why this Narrative puts Syndax Pharmaceuticals at 65% undervalued.
Before acting on Syndax Pharmaceuticals' valuation, look at who is steering the ship
Price and pipeline only tell part of the story, because the people making capital allocation calls and how they are rewarded can pull your outcome in a very different direction. See who runs Syndax Pharmaceuticals and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com