
Will Raised Guidance Change United Rentals Stock Narrative
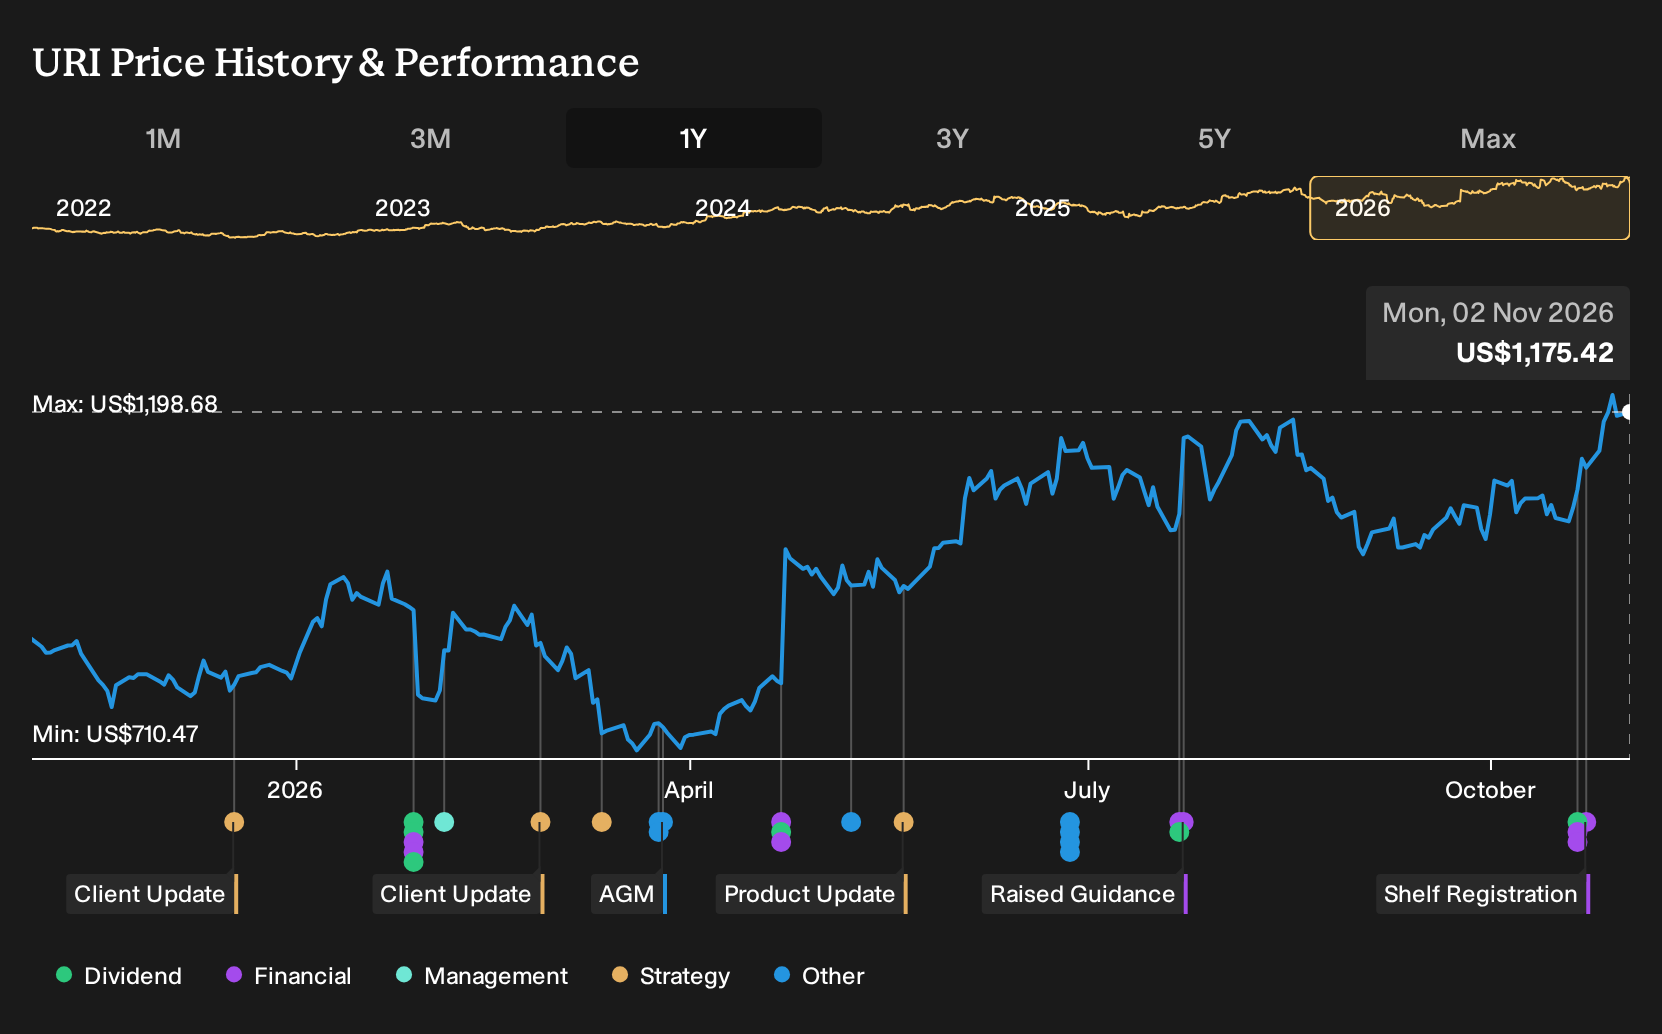
- United Rentals reported third quarter 2026 revenue of US$4,893 million and net income of US$920 million, raised full year 2026 revenue guidance to US$18.0b to US$18.2b, affirmed a quarterly dividend of US$1.97 per share, advanced its buyback program and filed an omnibus shelf registration for common and preferred stock and warrants.
- The combination of higher guidance, active share repurchases totaling US$791.36 million year to date, and a flexible shelf registration points to a capital plan that leans on strong cash generation while keeping room for future financing or acquisitions.
- We will now see how United Rentals' raised 2026 revenue guidance could reshape the existing investment narrative around project driven rental growth.
United Rentals Investment Narrative Recap
Owning United Rentals means believing large infrastructure and specialty projects continue to support high equipment utilization and returns on the current rental fleet. The raised 2026 revenue guidance to US$18.0b to US$18.2b supports that view in the near term. The key short term catalyst is continued conversion of the large project pipeline into sustained rental activity and earnings.
The biggest operational risk is that big project demand or local market activity slows while United Rentals carries heavy CapEx commitments and high debt. Recent results and guidance do not remove that risk. They suggest current project driven demand is supporting the existing investment plan for now.
The most relevant piece of recent news for that thesis is the higher 2026 revenue outlook paired with strong third quarter earnings. Revenue of US$4,893 million and net income of US$920 million for the quarter indicate the rental platform is handling current demand. That matters when the business is focusing on large infrastructure and specialty opportunities.
Raised guidance also interacts directly with catalysts such as fleet expansion, specialty growth and digital tools such as the Equipment Agent. Execution now needs to keep time utilization and margins aligned with the larger revenue base while managing risks from ancillary revenue mix, CapEx intensity and a balance sheet that still carries meaningful borrowing.
United Rentals' current analyst narrative points to 2029 revenue of US$22.4b and earnings of US$4.0b, based on an assumed 10.0% yearly increase in revenue from today and an earnings move from US$2.6b to US$4.0b, which is an increase of about US$1.4b by 2029.
Uncover why United Rentals' fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on long-term margin pressure from lower-margin ancillary and re-rent revenue. Before this latest United Rentals update, the most cautious analysts were working off 2029 earnings of about US$4.0b on roughly US$21.7b in revenue. That group interprets today’s higher guidance and shelf registration as raising the bar, not lowering it. You do not need to agree with that more pessimistic perspective, but it is worth weighing against the consensus to see how your own expectations line up.
Explore another United Rentals fair value estimate, including one that suggests it could be worth just $1,204.
The Verdict Is Yours
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your United Rentals research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for United Rentals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Rentals' overall financial health at a glance.
Looking For More Ideas Beyond United Rentals?
If you want to put United Rentals in context and widen your opportunity set, it helps to scan for other businesses with different risk and return profiles. The Simply Wall St Screener can help you quickly sort through candidates that fit the kind of balance sheet strength, income profile or risk level you want to focus on next.
- For investors who want potential upside with some financial resilience, check out a list of solid balance sheet and fundamentals (24 results) that can complement a position in a capital intensive rental business.
- If you prefer keeping downside risk in sharper focus, use a 29 resilient stocks with low risk scores that filters for companies with more measured risk scores.
- When you are hunting for less crowded opportunities with healthier fundamentals, look through a 19 high quality undiscovered gems that may sit off the usual large cap radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com