
How Investors Are Reacting To First Industrial Realty Trust Stock After Raised Earnings Guidance
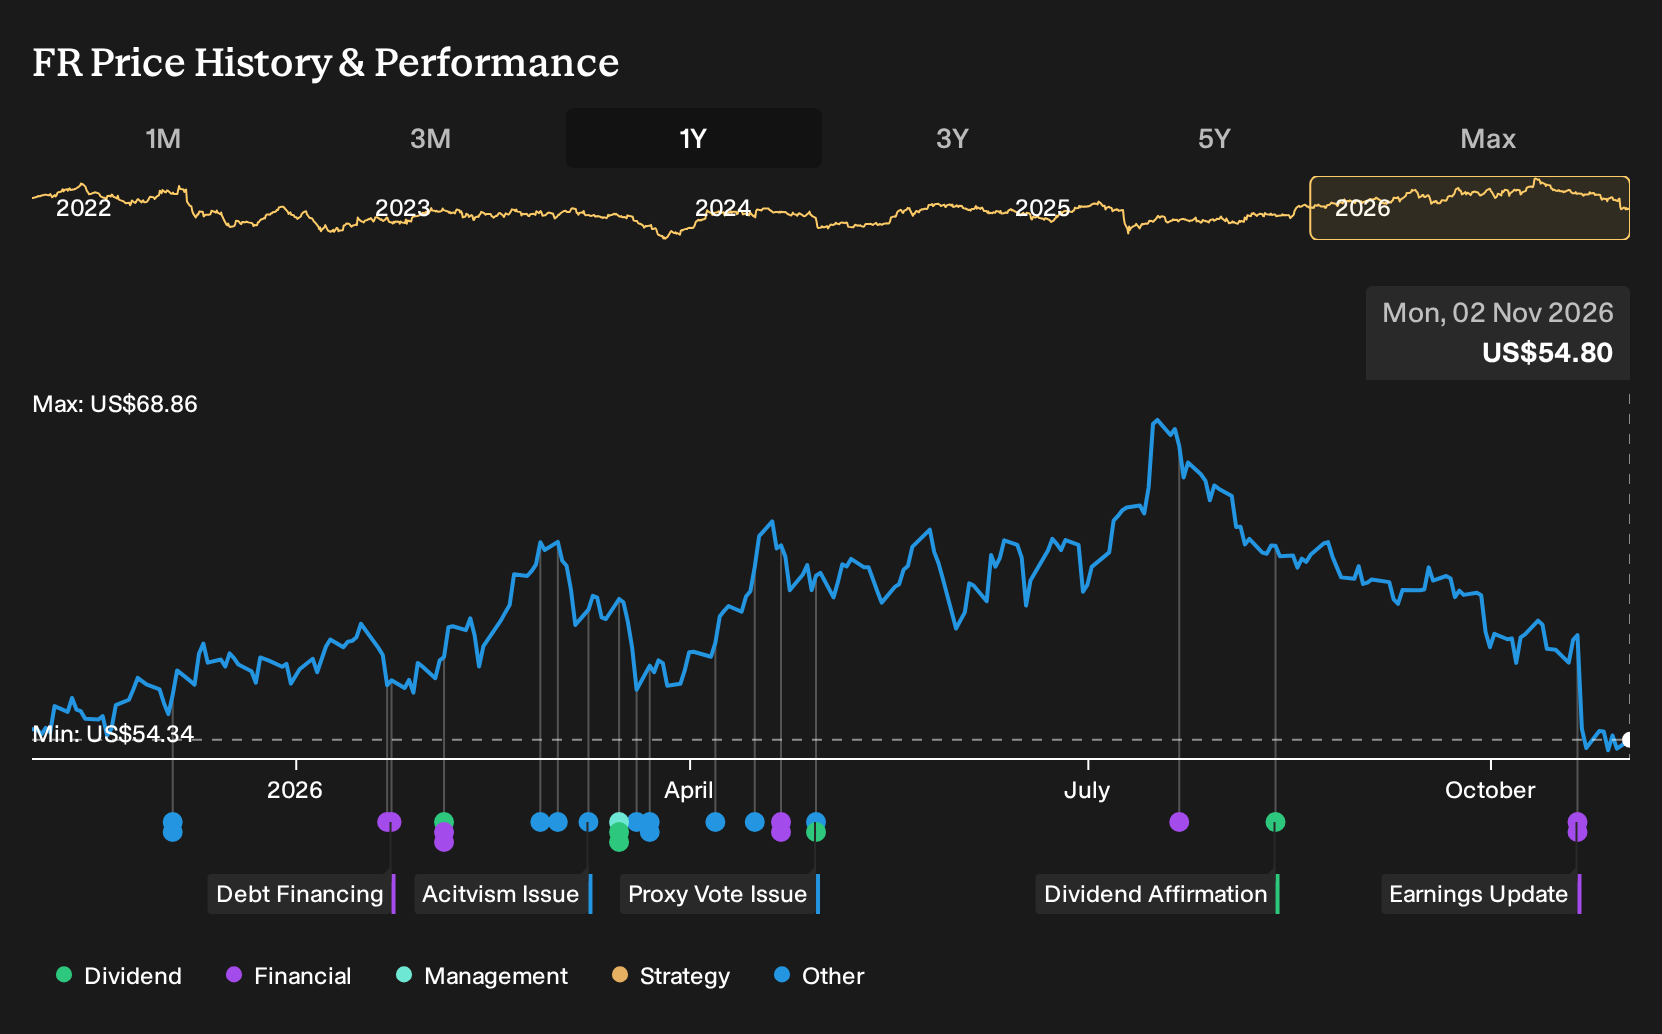
- First Industrial Realty Trust reported third quarter 2026 sales of US$197.12 million and net income of US$58.55 million, and also issued nine month figures with US$586.88 million in sales and US$278.75 million in net income.
- The REIT paired softer quarterly earnings per share with higher full year 2026 net income guidance of US$2.51 to US$2.55 per share, describing this as a sign of management’s confidence in the underlying industrial portfolio.
- We will now assess how First Industrial Realty Trust’s raised 2026 earnings guidance could reshape its investment narrative for long term holders.
First Industrial Realty Trust Investment Narrative Recap
To own First Industrial Realty Trust, you need to be comfortable with an industrial logistics model that leans on rent mark to market and leasing up development projects. The raised 2026 net income guidance to US$2.51 to US$2.55 per share suggests management currently sees enough earnings visibility to support that profile despite softer quarterly EPS.
In the near term, the key swing factor remains occupancy moving toward the guided 94% to 95% range and converting development into income-producing space. The biggest risk still sits with higher land costs and weaker operating cash coverage of debt. This earnings update does not remove those issues, but it also does not materially worsen them.
The most relevant piece of news is the raised 2026 net income guidance alongside the detailed third-quarter and nine-month results. Sales were US$197.12 million in the quarter and US$586.88 million for the nine months, with nine-month net income at US$278.75 million. Basic and diluted EPS from continuing operations were US$0.44 for the quarter.
The guidance range matters because it connects directly to the rent uplift and development catalysts investors already focus on for First Industrial Realty Trust. Higher full-year net income expectations, set against risks such as elevated proxy contest costs and rising land values, put more weight on execution around leasing, expense control and capital allocation over the next few quarters.
Analysts expect First Industrial Realty Trust's revenue to reach US$960.5 million and earnings to come to US$288.8 million by 2029. This aligns with an assumed 7.4% yearly revenue growth rate and an earnings decline of US$68.6 million from the current US$357.4 million level.
Uncover why First Industrial Realty Trust's fair value points to a 27% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$47.88 and US$69.38, which already shows how far opinions on First Industrial Realty Trust can stretch. When you set those against risks like weaker than guided occupancy or prolonged activism costs, you can see why you should compare several viewpoints before relying on any single narrative.
Explore 2 other First Industrial Realty Trust fair value estimates, including one that suggests up to 13% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your First Industrial Realty Trust research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for First Industrial Realty Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Industrial Realty Trust's overall financial health at a glance.
Looking for more investment ideas beyond First Industrial Realty Trust?
If the latest guidance from First Industrial Realty Trust has you rethinking your watchlist, it can help to line it up against other companies with different balance sheet profiles, income streams, and risk levels. The Simply Wall St Screener gives you a way to filter the broader market using fundamentals instead of headlines.
- For investors who want potential upside without ignoring quality, scan a curated group of 19 high quality undiscovered gems that combine strong fundamentals with lower visibility.
- If capital preservation matters just as much as return potential, narrow your search to 29 resilient stocks with low risk scores that score well on resilience and financial stability.
- When balance sheet strength is non negotiable, broaden your research beyond First Industrial Realty Trust by reviewing a list of solid balance sheet and fundamentals (24 results) that already passes strict fundamental filters.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com