
Why Cheniere Energy (LNG) Could Be 2% Below Fair Value Following 2026 Guidance Lift
Cheniere Energy (LNG) has been back in focus after a cluster of updates, including higher 2026 earnings guidance, a quarterly dividend increase of more than 12%, and additional LNG capacity from Corpus Christi’s seventh train.
The share price reaction has been choppy in the very short term, with Cheniere Energy falling around 5.7% on the day to about US$311.67, even though the 1 month share price return of roughly 15.5% and year to date share price gain of about 57.6% point to strong momentum building over 2026. That near term volatility comes on the heels of raised 2026 earnings guidance, a dividend uplift and fresh capacity from Corpus Christi, and sits alongside a 1 year total shareholder return of about 50.2% and a 5 year total shareholder return of roughly 202.3% as investors react to both higher cash generation potential and the added leverage from the new US$1.2b senior notes.
Spot 19 high quality undiscovered gems that share Cheniere Energy’s mix of capacity growth, long term contracts, and rising dividends before they sit on every watchlist.For investors watching Cheniere Energy rip higher then slip on the latest update, the real tension is simple. Pay up after this run or wait and risk never seeing that pullback.
Most Popular Narrative: 2% Undervalued
Cheniere Energy closed at $311.67, while the most followed narrative pegs fair value around $318.71 using a 7.24% discount rate. This puts recent price swings in the context of relatively modest perceived upside.
The highly contracted nature of Cheniere Energy’s LNG platform through 2030 and into 2035, combined with an investment grade credit profile and a capital return program that targets dividend growth and share repurchases, is set to keep a large portion of future EBITDA and distributable cash flow tied to recurring, contracted revenue.
Actions to apply normal purchases and normal sales accounting to a majority of IPM gas supply volumes are intended to reduce the volatility of reported net income that comes from LNG linked derivatives. This can help future earnings more closely reflect the underlying cash generating capacity of the business.
See why 68 investors see Cheniere Energy as 2% undervalued.
Result: Fair Value of $318.71 (UNDERVALUED)
Still, Cheniere Energy’s exposure to large swings in LNG linked derivatives and the federal investigation into a US$370m tax credit could both pressure future cash returns.
Find out about the key risks to this Cheniere Energy narrative.
Another View: What Multiples Say About Cheniere Energy
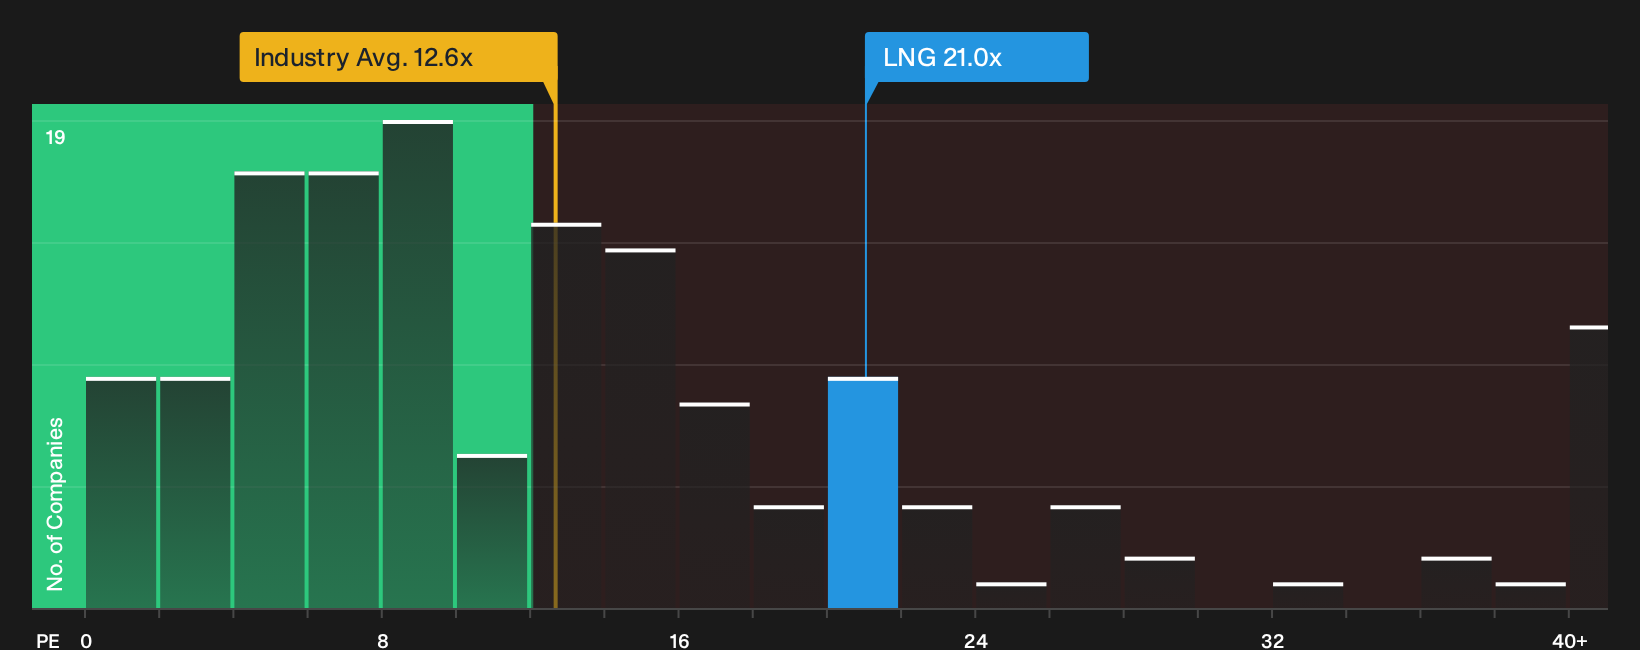
The SWS DCF model points to value, yet Cheniere Energy tells a different story when judged on its P/E ratio. The stock trades on about 21x earnings, compared with roughly 12.6x for the wider US Oil and Gas group and about 18.8x for peers, while the fair ratio is flagged at 20.1x. That richer tag suggests there may be less room for error if LNG contracts, derivative swings, or leverage do not break in your favour.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Cheniere Energy can feel unsettling. Move quickly to review the figures, stress test the story, and weigh both upside and downside using the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Cheniere Energy?
If Cheniere Energy has sharpened your focus on risk, return, and cash flow, broaden your watchlist now so you are not late to the next opportunity.
- Target resilient cash generators by checking out companies on the 34 high quality undervalued stocks that combine quality fundamentals with pricing that still looks reasonable.
- Strengthen your income stream by scanning the 4 dividend fortresses and zero in on businesses offering higher yields backed by solid payout histories.
- Protect your downside by reviewing the 29 resilient stocks with low risk scores and focus on enterprises with sturdier balance sheets and cleaner risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com